NVIDIA (NVDA), Financial Analysis
Insights derived from analysing SEC filings. Independent analysis, not a publication of the SEC.
- Q3 FY2027 (quarter to 25 Oct 2026) revenue $115.84bn, +103.2% year on year and +20.4% on Q2, against an outlook of $108.0bn plus or minus 2%. By market platform as filed: Hyperscale $60.1bn (+71%), AI Clouds, Industrial and Enterprise (ACIE) $47.5bn (+195%), Data Center in total $107.6bn (+110%) and Edge Computing $8.2bn (+42%).
- GAAP gross margin 74.8% against 73.4% a year earlier and 75.0% in Q2; operating margin 66.9%; GAAP diluted EPS $2.70 against $1.30 (+108%). Non GAAP EPS $2.68 against $1.27; net income $65.29bn incl. $1.77bn of net gains from equity securities, after a $1.8bn impairment of private holdings.
- Q4 FY2027 outlook: revenue $130.0bn plus or minus 3%, +12.2% on Q3, in a quarter with an additional week; gross margin 71.0% to 72.0%; GAAP operating expenses about $11.0bn. The outlook assumes no Data Center compute revenue from China; Data Center Hopper shipments to China were $2.4bn in Q3.
- Supply and capacity commitments $390bn at 25 Oct 2026 against $279bn a quarter earlier, mainly multi year memory procurement; total future commitments $518bn plus $32bn of neocloud agreements. Maximum guarantee exposure $118.0bn, incl. $105.0bn for SB Energy's PORTS‑Pike campus leased to OpenAI; no payments made to date. Receivables $81.03bn (DSO 64 days) and inventory $39.72bn.
- Operating cash flow $48.25bn and free cash flow $43.78bn; $28.1bn returned through buybacks ($22.12bn) and dividends ($6.03bn). The Board added $150bn to the buyback authorization in Sep 2026; $227.3bn remained at quarter end, which NVIDIA plans to use through FY2028.
- Forward looking statements in the Q3 release and CFO commentary name 'the ongoing investigation by an independent committee of NVIDIA's board of directors'. No filing describes its subject.
- First results after the CEO change filed on 12 Nov 2026: Jensen Huang resigned as CEO and director on 11 Nov; CFO Colette Kress is interim CEO and CFO; Harvey C. Jones is Chair. The release quotes only Kress, as interim CEO and EVP and CFO. NVDA closed at $155.46 on 17 Nov 2026 before the release, against $166.19 on 12 Nov.
Figures are read from the filings of NVIDIA Corporation (central index key 1045810): the Form 8-K of 17 Nov 2026 (filed 16:20 ET, acc 0001045810-26-000088) with Ex 99.1 press release, Ex 99.2 CFO commentary and Ex 99.3 supplemental financial information for Q3 FY2027 (quarter to 25 Oct 2026); the Form 8-K of 12 Nov 2026 on the CEO transition; the Forms 10-Q for Q2 FY2026, Q3 FY2026, Q1 FY2027 and Q2 FY2027; the Forms 10-K for FY2024, FY2025 and FY2026; the Forms 8-K of the last twelve months with all their exhibits, incl. the earnings releases and CFO commentaries; the 2026 proxy statement (DEF 14A of 12 May 2026); Forms 4; and the filings of the peers used in chapters 2 to 4 and 7. The Q3 FY2027 Form 10-Q was not filed on 17 Nov 2026; the CFO commentary states it will follow in the coming weeks. Chapter 12 reports statements made on the Q3 FY2027 earnings call of 17 Nov 2026, each labelled as said on the call; they are kept apart from filed figures. Accession numbers appear in the Sources appendix.
1 Q3 FY2027 Results, Revenue & Business Model
- Storyline: NVIDIA filed Q3 FY2027 results six days after its CEO resigned, with revenue of $115.84bn, a $130.0bn Q4 outlook and commitments of $518bn. Chapters 2 to 4 cover the three revenue drivers: Hyperscale; AI Clouds, Industrial and Enterprise; Edge Computing. Financial analysis, commitments and guarantees follow in chapter 5, the CFO commentary and outlook in chapter 6, peers in chapter 7, filings of the year incl. the CEO transition in chapter 8, ownership in chapter 9, risk factors in chapter 10 and price scenarios in chapter 11.
- NVIDIA sells accelerated computing platforms: GPUs, CPUs, networking, systems and software, reported as two segments, Compute & Networking ($106.0bn in Q3 FY2027, +108%) and Graphics ($9.8bn, +62%), and as two market platforms, Data Center and Edge Computing. Data Center was 92.9% of Q3 FY2027 revenue against 89.8% a year earlier.
- Revenue FY2022 $26.91bn, FY2024 $60.92bn, FY2026 $215.94bn (+65.5%); TTM Q3 FY2027 $361.81bn. Nine months FY2027 revenue $293.68bn against $147.81bn (+98.7%).
- Revenue by customer headquarters, Q3 FY2027 (Ex 99.3): United States $72.90bn, Taiwan $30.30bn, China incl. Hong Kong $11.05bn against $2.97bn a year earlier, other $1.60bn; customers headquartered outside the US were 37% of revenue. Three direct customers were 14%, 11% and 11% of Q3 revenue; two direct customers held 18% and 17% of receivables.
- Leadership: the 8-K of 12 Nov 2026 reports Huang's resignation as President, CEO and director on 11 Nov 2026, Kress's appointment as interim CEO while she remains EVP and CFO, and Jones's appointment as Chair. Kress signed the CEO transition 8-K; the Q3 release attributes its only quote to her.


| Line | Q3 FY2026 | Q2 FY2027 | Q3 FY2027 | On Q2 (%) | Year on year (%) |
|---|---|---|---|---|---|
| Data Center | 51.2 | 89.0 | 107.6 | 21 | 110 |
| Hyperscale | 35.1 | 48.7 | 60.1 | 23 | 71 |
| AI Clouds, Industrial and Enterprise | 16.1 | 40.3 | 47.5 | 18 | 195 |
| Edge Computing | 5.8 | 7.2 | 8.2 | 14 | 42 |
| Total revenue | 57.0 | 96.2 | 115.8 | 20 | 103 |
| Compute & Networking segment | 50.9 | 88.3 | 106.0 | 20 | 108 |
| Graphics segment | 6.1 | 7.9 | 9.8 | 25 | 62 |
| Line | Q4 FY2025 | Q1 FY2026 | Q2 FY2026 | Q3 FY2026 | Q4 FY2026 | Q1 FY2027 | Q2 FY2027 | Q3 FY2027 |
|---|---|---|---|---|---|---|---|---|
| Revenue ($m) | 39,331 | 44,062 | 46,743 | 57,006 | 68,127 | 81,615 | 96,221 | 115,844 |
| Revenue growth year on year (%) | n/a | n/a | n/a | n/a | 73.2 | 85.2 | 105.9 | 103.2 |
| Data Center ($m) | 35,580 | 39,112 | 41,096 | 51,215 | 62,314 | 75,246 | 89,023 | 107,600 |
| Data Center growth year on year (%) | n/a | n/a | n/a | n/a | 75.1 | 92.4 | 116.6 | 110.1 |
| Edge Computing ($m) | 3,751 | 4,950 | 5,647 | 5,791 | 5,813 | 6,369 | 7,198 | 8,200 |
| Operating income ($m) | 24,034 | 21,638 | 28,440 | 36,010 | 44,299 | 53,536 | 63,734 | 77,520 |
| Operating margin (%) | 61.1 | 49.1 | 60.8 | 63.2 | 65.0 | 65.6 | 66.2 | 66.9 |
| Diluted EPS ($) | 0.89 | 0.76 | 1.08 | 1.30 | 1.76 | 2.39 | 2.46 | 2.70 |
| Free cash flow ($m) | 15,520 | 26,135 | 13,449 | 22,089 | 34,900 | 48,554 | 21,341 | 43,777 |
| Item | Filed content |
|---|---|
| Event date | 11 Nov 2026; Form 8-K filed 12 Nov 2026 before the market opened (acc 0001045810-26-000082) |
| Departure | Jen‑Hsun (Jensen) Huang resigned as President, CEO and member of the Board, effective immediately; no reason stated |
| Interim CEO | Colette M. Kress, 59, EVP and CFO since Sep 2013; remains CFO while interim CEO |
| Board leadership | Harvey C. Jones, 73, director since 1993, appointed Chair of the Board; Ex 99.1 calls him the Board's first Chair |
| Permanent CEO | Board search with internal and external candidates; no timetable filed |
| Q3 FY2027 release, 17 Nov 2026 | Quote attributed to Colette Kress as interim CEO and EVP and CFO; CFO commentary by Kress; no other executive quoted |
| Forward looking statements, 17 Nov 2026 | Name the leadership transition and the search for a new CEO |
2 Hyperscale: $60.1bn in Q3 FY2027, +71%, Against Custom Accelerators
- Hyperscale revenue $60.1bn in Q3 FY2027, +71% year on year and +23% on Q2's $48.7bn, 55.9% of Data Center revenue. Hyperscale covers public clouds and the largest consumer internet companies.
- Products in the quarter (Ex 99.1): Vera Rubin NVL72 general availability on Oracle Cloud Infrastructure; Google Cloud A5X instances on Vera Rubin; Meta planning expanded deployment of Vera Rubin, Vera CPUs, Spectrum X networking and BlueField 4.
- Customer mix: hyperscalers were about 50% of Data Center revenue in Q1 FY2027 (8-K Ex 99.2); in Q3 FY2027 Hyperscale was 56% of Data Center on the filed figures.
- Concentration (Ex 99.3): three direct customers were 14%, 11% and 11% of Q3 FY2027 revenue, all mainly Compute & Networking.
How hyperscale AI spending is changing
- Q3 2026 capital expenditure: Amazon $77.3bn, Alphabet $51.4bn (+114%) and Microsoft $39.4bn (+103%) in their Sep 2026 quarters; Oracle $28.5bn (+235%) in its Aug 2026 quarter (company 10-Q and 8-K filings).
- Amazon guides FY2026 cash capital expenditure to about $220bn (Amazon 8-K, 29 Oct 2026); Microsoft reports $364.6bn of data center leases not yet commenced (Microsoft 10-Q, Sep 2026 quarter).
- Custom accelerators: Broadcom AI semiconductor revenue $16.7bn in the quarter to 2 Aug 2026, +221%, with $21.7bn guided for the next quarter (Broadcom 8-K, 2 Sep 2026).
- Amazon's chips business, incl. Trainium, ran above a $25bn annual revenue rate in Q2 2026 (Amazon 8-K Ex 99.1).
- NVIDIA's own filings: Vera Rubin NVL72 racks running at CoreWeave, Google Cloud, Microsoft Azure, Oracle Cloud Infrastructure and Nebius in Q3 FY2027; Hyperscale rose to $60.1bn from $48.7bn in Q2 FY2027 (8-K Ex 99.1 and Ex 99.2, 17 Nov 2026).
- NVIDIA 10-Q Q1 FY2027 risk factor: some customers develop their own ASICs optimized for certain workloads.


| Company | Line | Period | Revenue | Growth (%) | Margin (%) | Detail |
|---|---|---|---|---|---|---|
| NVIDIA | Hyperscale revenue | Q3 FY2027 | $60.1bn | 71 | n/a | no margin by market platform; growth as filed |
| TSMC (supplier) | HPC platform revenue | Q3 2026 | $31.81bn | 81.5 | n/a | 67.9% of TSMC revenue; NT$1.01tn at NT$31.88 per $1 |
| Broadcom | AI semiconductor revenue | qtr to 2 Aug 2026 | $16.70bn | 221.0 | 53.9 | custom accelerators and Ethernet switching; company GAAP operating margin |
| Marvell | Data center revenue | Jul 2026 qtr | $2.17bn | 45.7 | n/a | 79% of Marvell revenue |
| Arista Networks | Total revenue | Q3 2026 | $3.66bn | 58.5 | 44.9 | GAAP operating margin; AI networking peer |
| Cisco | Networking product revenue | Q1 FY2027 (Oct 2026 qtr) | $11.13bn | 43.3 | n/a | 60.1% of Cisco revenue; FY2026 hyperscaler AI orders $9.3bn |
| Astera Labs | Total revenue | Q3 2026 | $585m | 153.7 | 30.6 | AI rack connectivity; GAAP operating margin; largest direct customer 53% of revenue |
3 AI Clouds, Industrial and Enterprise: $47.5bn, +195%, With $32bn of Neocloud Commitments
- ACIE revenue $47.5bn in Q3 FY2027, +195% year on year from $16.1bn and +18% on Q2's $40.3bn, from AI natives, neoclouds, enterprises, industrial and sovereign customers.
- Neocloud agreements $32bn (formerly AI cloud agreements): NVIDIA's commitments take effect only if the neoclouds secure financing and the capacity is deployed, operational and accepted; NVIDIA earns revenue on the upfront sale and, if criteria are met, a share of the neoclouds' third party revenue (8-K Ex 99.2).
- Credit support: $3.5bn of land, power and shell guarantees for neoclouds, $9.5bn of power and systems credit support and up to $105bn for SB Energy's PORTS‑Pike campus, where OpenAI is tenant for about 4.25 GW.
- Customers named in the release: CoreWeave and Nebius running Vera Rubin NVL72 racks; CoreWeave, Nebius, Nscale, OpenAI and Verda building with Vera CPUs; Anthropic given expanded Grace Blackwell and Vera Rubin capacity through cloud providers.
How AI clouds, sovereign and enterprise demand is changing
- CoreWeave Q3 2026 revenue $3.66bn, +168%, revenue backlog about $132.5bn, contracted power above 4.6 GW and debt $46.9bn (CoreWeave 8-K and 10-Q, Nov 2026).
- Nebius Q3 2026 revenue $980.8m against $146.1m a year earlier; year end 2026 contracted power target 5 GW (Nebius 6-K filings, Aug and Nov 2026).
- Oracle OCI revenue $7.39bn in the Aug 2026 quarter, +120.7%; RPO $664bn (Oracle 10-Q, 11 Sep 2026).
- Contracts set in gigawatts: AMD with OpenAI 6 GW and Meta up to 6 GW; Cerebras with OpenAI 750 MW plus an option on 1.25 GW (AMD 8-K filings; Cerebras 10-Q).
- CoreWeave reports first Vera Rubin NVL72 production workloads at 4.8x the token throughput of GB200 NVL72 (CoreWeave 8-K Ex 99.1, Nov 2026).
- NVIDIA 10-Q Q2 FY2027: AI clouds and model makers lack long term contracts and investment grade financing; NVIDIA signed capital provider MOUs for over $500bn of third party capital.
- NVIDIA Q3 FY2027 CFO commentary: neocloud agreements (formerly AI cloud agreements) of $32bn take effect only if the neoclouds secure financing and the capacity is deployed and accepted; NVIDIA earns revenue on the upfront infrastructure sale and may share in their third party revenue (8-K Ex 99.2, 17 Nov 2026).

| Company | Line | Period | Revenue | Growth (%) | Margin (%) | Detail |
|---|---|---|---|---|---|---|
| NVIDIA | ACIE revenue | Q3 FY2027 | $47.5bn | 195 | n/a | AI clouds, industrial, enterprise, sovereign; growth as filed |
| AMD | Data Center segment revenue | Q3 2026 | $8.55bn | 96.9 | 33.7 | segment operating margin; Instinct and EPYC |
| Intel | DCAI revenue | Q3 2026 | $7.32bn | 77.8 | 41.5 | segment operating margin |
| Cerebras Systems | Revenue | Q3 2026 | $211m | 55.3 | (106.3) | GAAP operating margin; wafer scale systems and cloud |
| CoreWeave (customer) | Revenue | Q3 2026 | $3.66bn | 168.3 | 5.7 | AI cloud; GAAP operating margin |
| Nebius (customer) | Revenue | Q3 2026 | $981m | 571.3 | n/a | AI cloud |
| Oracle (customer) | OCI revenue | Aug 2026 qtr | $7.39bn | 120.7 | n/a | RPO $664bn |
4 Edge Computing: $8.2bn, +42%, as Memory Prices Weigh on Consumer PCs
- Edge Computing revenue $8.2bn in Q3 FY2027, +42% year on year and +14% on Q2, 7.1% of revenue: PCs, game consoles, workstations, AI RAN base stations, robotics and automotive.
- Drivers (8-K Ex 99.2): Blackwell workstation sales and edge compute for physical AI, while higher memory and system prices continue to affect consumer PC demand.
- Graphics segment revenue $9.8bn, +62%; Edge Computing growth in the four quarters to Q3 FY2027 ranged from 27% to 55%.
- Products filed in the release: RTX Spark laptops shipping from ASUS, Dell, HP, Lenovo, Microsoft Surface and MSI; DLSS 5; DGX Spark 64GB; Alpamayo and Halos tools for autonomous driving; expanded partnerships with Mercedes‑Benz and Volvo Cars.
How PC, gaming and automotive markets are changing
- NVIDIA: Q3 FY2027 Edge Computing growth came from Blackwell workstation sales and edge compute for physical AI, while higher memory and system prices continue to affect consumer PC demand (8-K Ex 99.2, 17 Nov 2026).
- PC makers' latest quarters: Dell Client Solutions Group $15.03bn (+20.2%) in the Jul 2026 quarter; HP Personal Systems $11.77bn (+18.5%) in the Jul 2026 quarter (company filings).
- Qualcomm QCT automotive revenue $1.99bn in the Sep 2026 quarter, +89% (Qualcomm 8-K, 4 Nov 2026).
- NVIDIA Q1 FY2027 release: BYD, Geely, Isuzu and Nissan building level 4 ready vehicles on NVIDIA DRIVE Hyperion; Q2 FY2027: RTX Spark Windows PC superchip with Microsoft.
- NVIDIA Q4 FY2026 CFO commentary expected supply constraints to weigh on Gaming in Q1 FY2027 and beyond.


| Company | Line | Period | Revenue | Growth (%) | Margin (%) | Detail |
|---|---|---|---|---|---|---|
| NVIDIA | Edge Computing revenue | Q3 FY2027 | $8.2bn | 42 | n/a | Graphics segment revenue $9.8bn (+62%) |
| AMD | Client and Gaming segment revenue | Q3 2026 | $3.72bn | (8.1) | 15.4 | segment operating margin |
| Intel | CCPG revenue | Q3 2026 | $8.10bn | (5.1) | 28.2 | segment operating margin |
| Qualcomm | QCT automotive revenue | Sep 2026 qtr | $1.99bn | 89.0 | 23.8 | QCT EBT margin |
| Qualcomm | QCT IoT revenue | Sep 2026 qtr | $1.89bn | 4.5 | n/a | includes PC chips |
| Mobileye | Revenue | Sep 2026 qtr | $492m | (2.0) | (17.0) | GAAP operating margin |
5 Financial Analysis & Ratios
- Operating margin TTM 66.1% against 60.4% in FY2026 and 62.4% in FY2025; Q3 FY2027 66.9% against 63.2%. Gross margin 74.8% in Q3 against 73.4%; operating expenses 7.9% of revenue against 10.2%.
- Net income TTM $226.26bn (62.5% of revenue); diluted EPS TTM $9.31. Net gains from equity securities were $30.97bn over the same four quarters; in Q3 $2.8bn of gains on public holdings and a $1.0bn net loss on private holdings, incl. $1.8bn of impairment.
- Free cash flow TTM $148.57bn: operating cash flow $158.86bn less capex $10.29bn. Q3 operating cash flow rose to $48.25bn from $24.08bn in Q2, which included federal tax payments; receivables used $18.05bn and inventory $8.15bn of cash in Q3.
- Balance sheet at 25 Oct 2026: cash and debt securities $53.51bn; marketable equity securities $44.22bn; non marketable securities $65.53bn; debt $32.37bn after $1.0bn of notes repaid in Q3; net cash $21.14bn; equity $266.67bn.
- Capital returns: Q3 buybacks $22.12bn and dividends $6.03bn at $0.25 a share; TTM buybacks $64.98bn and dividends $12.56bn. Next dividend of $0.25 payable 23 Dec 2026 to holders of record on 2 Dec 2026.
| Line item | FY2022 | FY2023 | FY2024 | FY2025 | FY2026 | TTM Q3 FY2027 |
|---|---|---|---|---|---|---|
| Revenue | 26.9 | 27.0 | 60.9 | 130.5 | 215.9 | 361.8 |
| Gross profit | 17.5 | 15.4 | 44.3 | 97.9 | 153.5 | 271.1 |
| Research and development | 5.3 | 7.3 | 8.7 | 12.9 | 18.5 | 26.3 |
| Selling, general and administrative | 2.2 | 2.4 | 2.7 | 3.5 | 4.6 | 5.6 |
| Operating income | 10.0 | 4.2 | 33.0 | 81.5 | 130.4 | 239.1 |
| Net income | 9.8 | 4.4 | 29.8 | 72.9 | 120.1 | 226.3 |
| Diluted EPS ($) | 0.39 | 0.17 | 1.19 | 2.94 | 4.90 | 9.31 |
| Operating cash flow | 9.1 | 5.6 | 28.1 | 64.1 | 102.7 | 158.9 |
| Capital expenditure | (1.1) | (1.9) | (1.1) | (3.4) | (6.1) | (10.3) |
| Free cash flow | 8.0 | 3.8 | 26.9 | 60.7 | 96.6 | 148.6 |
| Stock based compensation | 2.0 | 2.7 | 3.5 | 4.7 | 6.4 | 7.7 |
| Cash and investments | n/a | 13.3 | 26.0 | 43.2 | 49.7 | 53.5 |
| Total debt | n/a | 11.0 | 9.7 | 8.5 | 8.5 | 32.4 |
| Total equity | 26.6 | 22.1 | 43.0 | 79.3 | 157.3 | 266.7 |

| Metric | Q3 FY2026 | Q3 FY2027 | Change |
|---|---|---|---|
| Revenue ($bn) | 57.01 | 115.84 | 103.2% |
| Gross profit ($bn) | 41.85 | 86.68 | 107.1% |
| Operating income ($bn) | 36.01 | 77.52 | 115.3% |
| Net income ($bn) | 31.91 | 65.29 | 104.6% |
| Diluted EPS ($) | 1.30 | 2.70 | 107.7% |
| Operating cash flow ($bn) | 23.75 | 48.25 | 103.2% |
| Free cash flow ($bn) | 22.09 | 43.78 | 98.2% |
| Operating margin (%) | 63.2 | 66.9 | 3.7 pts |
| Net margin (%) | 56.0 | 56.4 | 0.4 pts |
| Ratio | FY2022 | FY2023 | FY2024 | FY2025 | FY2026 | TTM Q3 FY2027 |
|---|---|---|---|---|---|---|
| Growth and margins | ||||||
| Revenue growth (%) | n/a | 0.2 | 125.9 | 114.2 | 65.5 | n/a |
| Gross margin (%) | 64.9 | 56.9 | 72.7 | 75.0 | 71.1 | 74.9 |
| Operating margin (%) | 37.3 | 15.7 | 54.1 | 62.4 | 60.4 | 66.1 |
| Net margin (%) | 36.2 | 16.2 | 48.8 | 55.8 | 55.6 | 62.5 |
| FCF margin (%) | 29.9 | 13.9 | 44.2 | 46.5 | 44.7 | 41.1 |
| Cost and investment intensity | ||||||
| R&D (%) revenue | 19.6 | 27.2 | 14.2 | 9.9 | 8.6 | 7.3 |
| SBC (%) revenue | 7.4 | 10.0 | 5.8 | 3.6 | 3.0 | 2.1 |
| Capex (%) revenue | 3.9 | 7.0 | 1.9 | 2.6 | 2.8 | 2.8 |
| Effective tax rate (%) | 1.9 | (4.5) | 12.0 | 13.3 | 15.1 | 16.5 |
| Returns | ||||||
| ROE (%) | 36.6 | 17.9 | 91.5 | 119.2 | 101.5 | 84.8 |
| ROA (%) | n/a | 10.6 | 55.7 | 82.2 | 75.4 | 60.8 |
| ROIC (%) | 37.0 | 17.5 | 108.7 | 158.5 | 95.3 | 81.4 |
| Asset turnover (x) | n/a | 0.65 | 0.93 | 1.17 | 1.04 | 0.97 |
| Liquidity and leverage | ||||||
| Current ratio (x) | n/a | 3.52 | 4.17 | 4.44 | 3.91 | 4.08 |
| Debt to equity (x) | n/a | 0.50 | 0.23 | 0.11 | 0.05 | 0.12 |
| Net cash ($bn) | n/a | 2.3 | 16.3 | 34.7 | 41.2 | 21.1 |
| Efficiency and cash quality | ||||||
| Days sales outstanding | n/a | 52 | 60 | 65 | 65 | 82 |
| Inventory days | n/a | 162 | 116 | 113 | 125 | 160 |
| Shareholder returns (%) FCF | 5 | 278 | 37 | 57 | 43 | 52 |


| Measure | Value |
|---|---|
| Market cap ($bn) | 3,746.6 |
| Enterprise value ($bn) | 3,725.5 |
| P/E (TTM) (x) | 16.7 |
| EV/Sales (TTM) (x) | 10.3 |
| EV/EBITDA (TTM) (x) | 15.3 |
| FCF yield (%) | 4.0 |
| Price/Book (x) | 14.0 |
Cost structure and profitability
- Gross margin 74.8% in Q3 FY2027 against 73.4%, with gross profit +107.1% against revenue +103.2%; operating margin +3.7 pts year on year and +0.7 pts on Q2.
- Research and development $7.45bn (+58.4%), 6.4% of revenue against 8.3%; sales, general and administrative $1.70bn (+50.1%); stock based compensation $2.09bn.
- Q3 against the Aug 2026 outlook: gross margin 74.8% against 74.0% plus or minus 0.5 pts; GAAP operating expenses $9.16bn against about $9.2bn. Q4 outlook: gross margin 71.0% to 72.0% and GAAP operating expenses about $11.0bn.

| Line | Q3 FY2026 | Q4 FY2026 | Q1 FY2027 | Q2 FY2027 | Q3 FY2027 |
|---|---|---|---|---|---|
| Cost of revenue (% of revenue) | 26.6 | 25.0 | 25.1 | 25.0 | 25.2 |
| Research and development (% of revenue) | 8.3 | 8.1 | 7.7 | 7.3 | 6.4 |
| Sales, general and administrative (% of revenue) | 2.0 | 1.9 | 1.6 | 1.4 | 1.5 |
| Stock based compensation (incl. in lines above) (% of revenue) | 2.9 | 2.4 | 2.4 | 2.1 | 1.8 |
| Operating income (% of revenue) | 63.2 | 65.0 | 65.6 | 66.2 | 66.9 |
| Other income, net (% of revenue) | 3.4 | 9.0 | 20.1 | 8.1 | 1.3 |
| Net income (% of revenue) | 56.0 | 63.1 | 71.5 | 62.0 | 56.4 |
| Line | Q3 FY2026 | Q3 FY2027 | Change |
|---|---|---|---|
| Revenue | 57,006 | 115,844 | 58,838 |
| Gross profit | 41,849 | 86,676 | 44,827 |
| Operating expenses | (5,839) | (9,156) | (3,317) |
| Operating income | 36,010 | 77,520 | 41,510 |
| Other income, net | 1,926 | 1,497 | (429) |
| Income taxes | (6,026) | (13,730) | (7,704) |
| Net income | 31,910 | 65,287 | 33,377 |
Commitments, guarantees, receivables and debt
- Supply and capacity commitments rose from $50.3bn at 26 Oct 2025 to $95.2bn, $119.0bn, $279bn and $390bn at 25 Oct 2026, mainly memory; $69bn falls due in the rest of FY2027 and $203bn in FY2028.
- Cloud service agreements and data center leases not commenced $102bn against $74bn a quarter earlier; the leases run up to 20 years and are expected to commence between Q4 FY2027 and FY2033.
- Guarantees with a maximum gross exposure of $118.0bn, up from $108.5bn at 26 Jul 2026 with the new $9.5bn of power and systems credit support; SB Energy exposure builds from FY2029 as buildings come online and then declines over each 20 year lease.
- Receivables $81.03bn and inventory $39.72bn at 25 Oct 2026 against $33.39bn and $19.78bn a year earlier; debt $32.37bn.

| Commitment | Rest of FY2027 | FY2028 | FY2029 | FY2030 | FY2031 | FY2032 on | Total |
|---|---|---|---|---|---|---|---|
| Supply and capacity | 69 | 203 | 92 | 10 | 8 | 8 | 390 |
| Cloud service agreements | 2 | 7 | 7 | 6 | 4 | 2 | 28 |
| Data center leases not commenced | 0 | 1 | 2 | 4 | 4 | 63 | 74 |
| Equity investments | 5 | 11 | 2 | 2 | 0 | 0 | 20 |
| Capital expenditures | 6 | 0 | 0 | 0 | 0 | 0 | 6 |
| Total | 82 | 222 | 103 | 22 | 16 | 73 | 518 |
| Neocloud agreements (additional) | 0 | 6 | 7 | 6 | 5 | 8 | 32 |
| Guarantee | Exposure |
|---|---|
| Land, power and shell guarantees for neoclouds | 3.5 |
| SB Energy credit support guarantees | 105.0 |
| Power and systems credit support guarantees | 9.5 |
| Total | 118.0 |
6 MD&A & Management Commentary
Q3 FY2027 results: 8-K Ex 99.1, Ex 99.2 and Ex 99.3 of 17 Nov 2026
- Revenue $115.84bn, +103.2% year on year and +20.4% on Q2, +7.3% above the $108.0bn outlook midpoint. CFO commentary: Hyperscale and ACIE grew on the introduction of Rubin infrastructure, described as 'our fastest architecture ramp ever', standalone Vera CPUs and continued Blackwell Ultra growth.
- Profit lines: gross margin 74.8%, up 1.4 pts on Blackwell Ultra mix and down 0.2 pts on Q2 on the initial Rubin ramp; operating income $77.52bn (+115%); other income $1.50bn; tax rate 17.4%; net income $65.29bn (+105%).
- Costs: GAAP operating expenses $9.16bn, +57% year on year and +9% on Q2, on compute infrastructure and employee costs; non GAAP $8.84bn. Inventory provisions $680m against $378m a year earlier.
- Working capital: receivables $81.03bn, DSO 64 days against 60 in Q2, on shipment linearity in the Rubin launch and extended payment terms with investment grade customers; inventory $39.72bn against $31.58bn, of which raw materials $15.80bn and work in process $17.77bn.
- Products filed in the release: Vera Rubin NVL72 racks running at CoreWeave, Google Cloud, Microsoft Azure, Oracle Cloud Infrastructure and Nebius; Vera CPU adoption by CoreWeave, Meta, Nebius, Nscale, OpenAI and Verda; agreement to acquire Hugging Face; expanded capacity access for Anthropic through cloud providers.
| Item | Outlook | Source |
|---|---|---|
| Q4 FY2027 revenue | $130.0bn plus or minus 3%; quarter includes an additional week; no Data Center compute revenue from China assumed | 8-K Ex 99.1 and Ex 99.2, 17 Nov 2026 |
| Q4 FY2027 gross margin | GAAP and non GAAP 71.0% to 72.0% | 8-K Ex 99.2, 17 Nov 2026 |
| Q4 FY2027 operating expenses | GAAP about $11.0bn, non GAAP about $10.7bn | 8-K Ex 99.2, 17 Nov 2026 |
| FY2027 tax rate | 16.0% to 18.0%, unchanged since May 2026 (Feb 2026: 17.0% to 19.0%) | 8-K Ex 99.2 of 25 Feb, 20 May, 26 Aug and 17 Nov 2026 |
| Q3 FY2027 outlook against actual | Outlook $108.0bn plus or minus 2%, actual $115.84bn; gross margin outlook 74.0% plus or minus 0.5 pts, actual 74.8%; GAAP opex outlook about $9.2bn, actual $9.16bn | 8-K Ex 99.2, 26 Aug and 17 Nov 2026 |
| Revenue outlook path | Q4 FY2026 $65.0bn (actual $68.13bn); Q1 FY2027 $78.0bn (actual $81.62bn); Q2 FY2027 $91.0bn (actual $96.22bn); Q3 FY2027 $108.0bn (actual $115.84bn); Q4 FY2027 $130.0bn | 8-K Ex 99.1 and 99.2 releases |
| Buyback authorization | $150bn added in Sep 2026, no expiration; $227.3bn remaining at 25 Oct 2026, planned for use through FY2028 | 8-K Ex 99.2, 17 Nov 2026 |
Management and CFO commentary
- CFO commentary is filed as 8-K Ex 99.2 with each earnings release; the Q3 FY2027 commentary is the first by Colette Kress as interim CEO and EVP and CFO.
- Q3 FY2027 CFO commentary (17 Nov 2026): supply commitments rose to $390bn from $279bn, mainly multi year memory procurement; 'securing land, power and shell for data centers has become the next critical phase'; $28.1bn returned to shareholders, described as a record; 10-Q to follow in the coming weeks.
- Q2 FY2027 CFO commentary (26 Aug 2026): commitments rose to $279bn from $119bn; DSO 60 days on extended terms for investment grade customers; $25.0bn of notes issued.
- CEO transition release (12 Nov 2026), Chair Harvey Jones: the Board expects operations, customer commitments and the product roadmap to continue without interruption.
| Speaker | Date and source | Statement |
|---|---|---|
| Harvey C. Jones, Chair of the Board | 12 Nov 2026, 8-K Ex 99.1 | “The Board has full confidence in Colette and the leadership team” |
| Colette Kress, Interim CEO and CFO | 12 Nov 2026, 8-K Ex 99.1 | “Our focus remains on serving our customers, partners, developers and shareholders.” |
| Colette Kress, Interim CEO and EVP and CFO | 17 Nov 2026, 8-K Ex 99.1 | “Vera Rubin is off to an explosive start, our roadmap is on track” |
| Item | Disclosure |
|---|---|
| 8-K Ex 99.3 Q3 FY2027, investments | Non marketable equity securities $61.65bn at 25 Oct 2026 after $15.43bn of Q3 net additions and $1.85bn of impairments and unrealized losses; $21.0bn of public holdings under short term lock up. |
| 8-K Ex 99.2 Q3 FY2027, neocloud agreements | $32bn; commitments take effect only if the neoclouds secure financing and the capacity is deployed, operational and accepted by NVIDIA; NVIDIA earns revenue on the upfront sale and may share in their revenue. |
| 8-K Ex 99.2 Q3 FY2027, data center leases | Upcoming leases with terms up to 20 years, not commenced, expected to start between Q4 FY2027 and FY2033; NVIDIA may assign some to third parties. |
| 10-K FY2026, customers | Sales to one direct customer were 22% of FY2026 revenue and to another 14%, both mainly Compute & Networking. |
| 10-K FY2026, Item 1A key personnel | States NVIDIA is highly dependent on its longstanding executive team and that failure to ensure succession planning and smooth transitions could hinder strategy and execution; wording near unchanged from FY2025. |
| 10-K FY2026, Item 1A new factor | Commercial arrangements, incl. capacity purchase obligations and financial guarantees, expose NVIDIA to counterparty risk; no financing arrangements had been entered into at filing. |
| 10-K FY2026, Groq | Intellectual property license with Groq required nonrefundable payments; $2.94bn paid to Groq in Q2 FY2027 (cash flow statement). |
| 10-K FY2026, OpenAI | NVIDIA was finalizing an investment and partnership agreement with OpenAI, with no assurance of completion. |
| 10-K FY2026, revenue by billing location | United States $149.62bn, Taiwan $42.35bn, China incl. Hong Kong $19.68bn (FY2025 $25.05bn), other $4.30bn. |
| 10-K FY2026, change of control | Under the Xbox agreement Microsoft may have first and last rights of refusal if someone offers to buy at least 30% of NVIDIA's stock. |
| 10-Q Q2 FY2027, commitments | Supply and capacity commitments $279bn at 26 Jul 2026 against $119bn a quarter earlier, mainly memory; total future commitments $366bn plus $56bn of AI cloud agreements and third party leases. |
| 10-Q Q2 FY2027, guarantees | Maximum gross exposure $108.5bn: $105.0bn SB Energy (OpenAI tenant, first data centers expected in FY2029) and $3.5bn for AI cloud partners. |
| 10-Q Q2 FY2027, investments | Equity investments $99bn and equity investment commitments $25bn at 26 Jul 2026; Q2 net gains from equity securities $7.77bn. |
| 10-Q Q2 FY2027, customers | One direct customer was 16% of Q2 revenue; one AI research and deployment company contributed a meaningful amount of revenue through cloud purchases; revenue from customers headquartered outside the US 38%. |
| 10-Q Q2 FY2027, China | $0.4bn H200 charge in 1H FY2027; H200 shipments under US licenses below 1% of Data Center revenue and subject to a 25% tariff not passed on to customers. |
| 10-Q Q2 FY2027, receivables | Receivables $63.06bn, DSO 60 days against 45, from extended payment terms on large multi quarter agreements with investment grade customers. |
| 10-Q Q2 FY2027, debt | $33.5bn principal of notes at 26 Jul 2026 after $25.0bn issued in Jun 2026; $25.0bn commercial paper program undrawn. |
| 10-Q Q2 FY2027, Item 1A | New factor on commitments, guarantees and other commercial arrangements and new factor on indebtedness; export control factor updated for H200. |
7 Peer Comparison & Sector Summary
- Sector: AI accelerators, foundry, connectivity, networking and chip equipment. NVIDIA's 10-K names competitors incl. suppliers of GPUs, CPUs, DPUs, custom ASICs and networking, and states that some customers develop their own ASICs.
- Growth, latest period year on year: ALAB 153.7% (Q3 2026), NVDA 103.2% (Q3 FY2027), AMAT 53.1% (Q4 FY2026), TSM 50.9% (Q3 2026), AMD 44.7% (Q3 2026), ANET 44.3% (9M 2026), CSCO 24.4% (Q1 FY2027), INTC 20.9% (Q3 2026).
- Operating margin TTM: NVDA 66.1%, TSM 58.0%, ANET 43.8%, AMAT 32.2%, CSCO 26.3%, ALAB 25.5%, AMD 17.7%, INTC 2.9%.
- Scale: NVDA TTM revenue $361.81bn against TSM $155.11bn, CSCO $66.96bn, INTC $59.90bn and AMD $45.40bn; peer valuations are not shown because their closing prices fall on different dates.
| Company | Revenue TTM ($bn) | Revenue growth (%) | Gross margin (%) | Operating margin (%) | Net margin (%) | FCF margin (%) | ROE (%) | Net cash ($bn) |
|---|---|---|---|---|---|---|---|---|
| NVDA | 361.8 | 103.2 | 74.9 | 66.1 | 62.5 | 41.1 | 84.8 | 21.1 |
| AMD | 45.4 | 44.7 | 53.7 | 17.7 | 16.8 | 14.9 | 11.6 | 8.7 |
| TSM | 155.1 | 50.9 | 65.8 | 58.0 | 51.5 | 29.7 | n/a | 93.6 |
| AMAT | 34.5 | 53.1 | 50.0 | 32.2 | 29.3 | 18.0 | 43.4 | 7.6 |
| CSCO | 67.0 | 24.4 | 64.1 | 26.3 | 22.3 | 20.5 | 30.1 | (14.0) |
| ANET | 11.9 | 44.3 | 62.9 | 43.8 | 40.0 | 42.2 | 28.9 | 14.4 |
| ALAB | 1.6 | 153.7 | 73.9 | 25.5 | 29.6 | 22.1 | 27.4 | 1.4 |
| INTC | 59.9 | 20.9 | 39.9 | 2.9 | (20.1) | 2.7 | (10.9) | 3.9 |

8 Material Events, CEO Transition & Contracts
- Fifteen Forms 8-K from 19 Nov 2025 to 17 Nov 2026: five earnings releases with CFO commentaries, six Item 5.02 officer, director and pay filings incl. the CEO transition, the vote results, a $25.0bn notes offering, the SB Energy guaranties and the Hugging Face agreement.
- Q3 FY2027 results (Items 2.02 and 9.01, 17 Nov 2026, 16:20 ET): Ex 99.1 release, Ex 99.2 CFO commentary and Ex 99.3 supplemental financial information with statements, investments, inventory, geography and customer concentration.
- CEO transition (Items 5.02 and 9.01, 12 Nov 2026): Huang resigned as President, CEO and director on 11 Nov 2026; Kress interim CEO and CFO; Jones Chair; no compensation, separation or severance terms filed.
- SB Energy (Items 1.01 and 2.03, 17 Aug 2026): guaranties on leases for about 4.25 GW at the PORTS‑Pike campus in Ohio, tenant OpenAI; exposure capped at $105bn, building by building from FY2029; option on about 3.8 GW more. The Q3 CFO commentary adds $9.5bn of power and systems credit support guarantees.
- Hugging Face (Item 8.01, 3 Sep 2026): purchase price about $11.9bn plus a retention program of up to about $1.0bn; closing expected in 1H 2027 subject to regulatory approvals; still pending in the Q3 release.
| Date | Items | Event |
|---|---|---|
| 19 Nov 2025 | 2.02, 9.01 | Q3 FY2026 results (Ex 99.1, Ex 99.2 CFO commentary): revenue $57.01bn (+62%), Data Center $51.22bn (+66%), GAAP EPS $1.30; Q4 outlook $65.0bn |
| 23 Jan 2026 | 5.02 | Director Persis Drell resigned on 20 Jan 2026 to pursue a new professional opportunity, not because of any disagreement |
| 25 Feb 2026 | 2.02, 9.01 | Q4 and FY2026 results: Q4 revenue $68.13bn (+73%), FY2026 $215.94bn (+65%), FY2026 GAAP EPS $4.90; Q1 FY2027 outlook $78.0bn |
| 6 Mar 2026 | 5.02, 9.01 | FY2027 Variable Compensation Plan (Ex 10.1) tied to FY2027 revenue: target cash awards Huang $4.0m (200% of salary), other named officers $1.5m (150%) |
| 27 Apr 2026 | 5.02 | Chief Accounting Officer Donald Robertson to retire 4 May 2026; Scott Gawel (from Intel) appointed, salary $800,000 and RSUs with target value $12.875m |
| 8 May 2026 | 5.02 | Suzanne Nora Johnson appointed director and Audit Committee member effective 13 Jul 2026; Board raised from 10 to 11 seats |
| 20 May 2026 | 2.02, 9.01 | Q1 FY2027 results: revenue $81.62bn (+85%), GAAP EPS $2.39; quarterly dividend raised to $0.25 from $0.01; $80bn added to buyback authorization; Q2 outlook $91.0bn |
| 18 Jun 2026 | 8.01, 9.01 | $25.0bn of senior notes in seven tranches due 2028 to 2056, coupons 4.250% to 5.625% (Ex 1.1 underwriting agreement, Ex 4.2 officers' certificate, Ex 5.1 legal opinion) |
| 30 Jun 2026 | 5.07 | Annual meeting of 24 Jun 2026: 10 directors elected, say on pay approved, stockholder proposal for simple majority voting approved; three other stockholder proposals rejected |
| 2 Jul 2026 | 5.02 | EVP Worldwide Field Operations Ajay Puri to retire; Nicholas Parker (from Microsoft) appointed from about 24 Aug 2026: salary $1.0m, $5.0m sign on bonus, RSUs $35.0m and PSUs $5.0m target value |
| 17 Aug 2026 | 1.01, 2.03, 7.01, 9.01 | Residual value guaranties with SB Energy for about 4.25 GW at the PORTS campus in Ohio leased to OpenAI; obligation capped at $105bn; option on about 3.8 GW more; $1.5bn investment in SB Energy (Ex 99.1) |
| 26 Aug 2026 | 2.02, 9.01 | Q2 FY2027 results: revenue $96.22bn (+106%), Data Center $89.02bn (+117%), GAAP EPS $2.46; Q3 outlook $108.0bn plus or minus 2%; supply commitments $279bn |
| 3 Sep 2026 | 8.01 | Agreement of 2 Sep 2026 to acquire Hugging Face for about $11.9bn plus a retention program of up to about $1.0bn; closing expected in 1H 2027 subject to regulatory approvals |
| 12 Nov 2026 | 5.02, 9.01 | CEO Jen‑Hsun Huang resigned as President, CEO and director on 11 Nov 2026; CFO Colette Kress interim CEO; Harvey C. Jones appointed first Chair of the Board; search for a permanent CEO (Ex 99.1) |
| 17 Nov 2026 | 2.02, 9.01 | Q3 FY2027 results: revenue $115.84bn (+103%), Data Center $107.6bn (+110%), GAAP EPS $2.70; Q4 outlook $130.0bn plus or minus 3%; supply commitments $390bn; guarantees $118.0bn (Ex 99.1, 99.2, 99.3) |
| Contract | Terms |
|---|---|
| Supply and capacity commitments | $390bn at 25 Oct 2026 against $279bn at 26 Jul 2026, mainly multi year memory; $69bn due in the rest of FY2027 and $203bn in FY2028 (8-K Ex 99.2, 17 Nov 2026). |
| Neocloud agreements | Formerly AI cloud agreements; $32bn, contingent on neocloud financing and accepted deployment; revenue on the upfront sale plus a possible revenue share (8-K Ex 99.2). |
| Cloud services and data center leases | $102bn together against $74bn a quarter earlier: $28bn cloud service agreements and $74bn of leases not commenced, terms up to 20 years (8-K Ex 99.2). |
| Guarantees | Maximum gross exposure $118.0bn: $105.0bn SB Energy (PORTS‑Pike, OpenAI tenant, 20 year leases), $9.5bn power and systems credit support and $3.5bn of land, power and shell guarantees for neoclouds; no payments made (8-K Ex 99.2). |
| Senior notes | $25.0bn issued 18 Jun 2026 in seven tranches, 4.250% due 2028 to 5.625% due 2056; $1.0bn repaid in Q3 FY2027; long term debt $32.37bn at 25 Oct 2026. |
| Hugging Face | Pending acquisition, about $11.9bn plus retention program up to about $1.0bn (8-K Item 8.01, 3 Sep 2026). |
| Effective | Role | Change | Filing |
|---|---|---|---|
| 20 Jan 2026 | Director | Persis Drell resigned from the Board | 8-K Item 5.02 |
| 4 May 2026 | Chief Accounting Officer | Donald Robertson retired; Scott Gawel (from Intel) appointed | 8-K Item 5.02, 27 Apr 2026 |
| 13 Jul 2026 | Director | Suzanne Nora Johnson joined; Board raised to 11 | 8-K Item 5.02, 8 May 2026 |
| 24 Aug 2026 | EVP Worldwide Field Operations | Ajay Puri retiring; Nicholas Parker (from Microsoft) appointed | 8-K Item 5.02, 2 Jul 2026 |
| 11 Nov 2026 | President and CEO; Chair | Jen‑Hsun Huang resigned; Colette Kress interim CEO; Harvey Jones Chair | 8-K Item 5.02, 12 Nov 2026 |
9 Ownership, Pay, Votes & Insiders
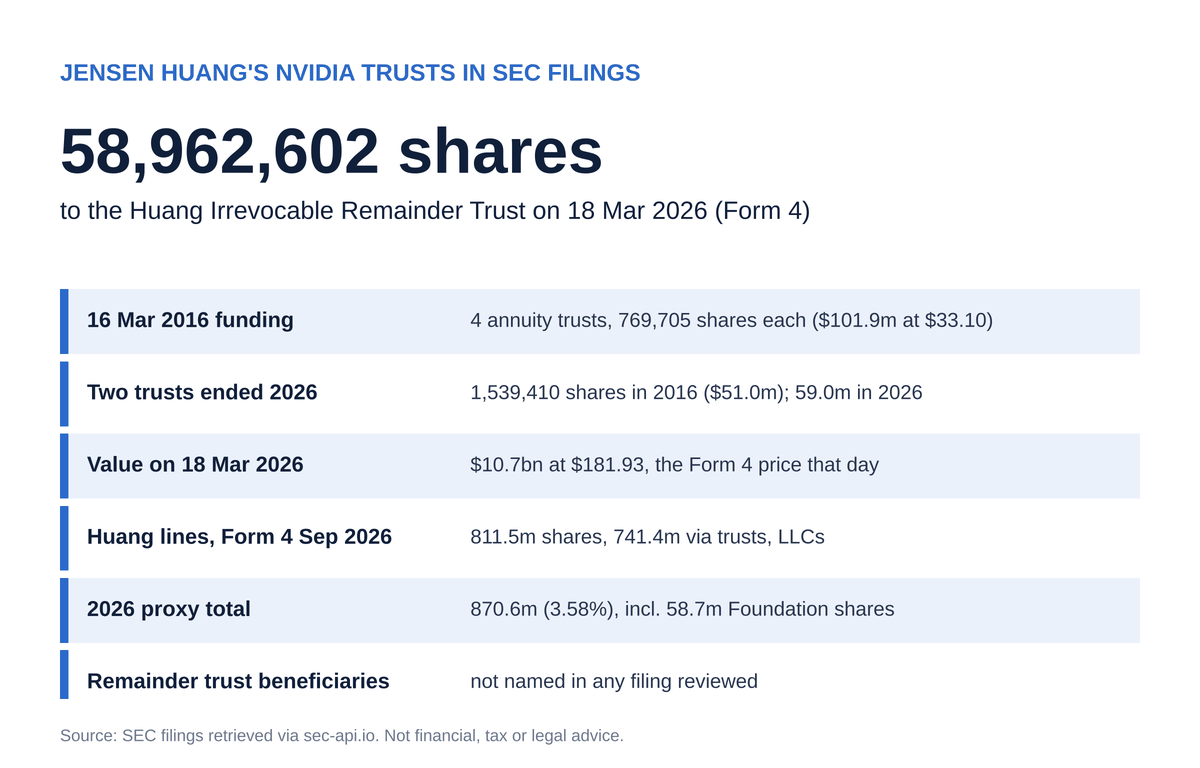
- One class of common stock, one vote per share. BlackRock 7.43% and Vanguard Capital Management 7.31% are the holders above 5% in the 2026 proxy; Huang 3.58% at 23 Mar 2026, incl. 58.7m shares held by the Huang foundation in which he has no pecuniary interest.
- Annual meeting of 24 Jun 2026 (Item 5.07): all ten directors elected; Huang received 99.0% of votes cast, Jones 90.7% and Lead Director Neal 86.7%; say on pay 93.6%; a stockholder proposal to replace supermajority voting with a simple majority passed with 86.8%.
- Pay (2026 proxy): Huang's FY2026 total compensation $36.34m and Kress's $14.34m; no employment, severance or change in control agreements with executive officers. No interim CEO pay arrangement was filed with the 12 Nov or 17 Nov 2026 8-K.
- Insiders, Form 4 transactions 24 Nov 2025 to 4 Nov 2026: no open market purchases; sales of $1.87bn, of which $322m flagged under Rule 10b5‑1 plans and $1.50bn by director Mark Stevens. Huang made no open market sales. Kress sold 243,348 shares for $44.8m and Jones 250,000 for $44.3m.
| Proposal | For (bn votes) | Against (bn votes) | Abstain (bn votes) | For as % of votes cast | Result |
|---|---|---|---|---|---|
| Election: Jen‑Hsun Huang | 16.650 | 0.166 | 0.040 | 99.0 | Elected |
| Election: Harvey C. Jones | 15.241 | 1.570 | 0.046 | 90.7 | Elected |
| Election: Stephen C. Neal (Lead Director) | 14.573 | 2.235 | 0.049 | 86.7 | Elected |
| Say on pay | 15.706 | 1.071 | 0.079 | 93.6 | Approved |
| Ratify PricewaterhouseCoopers | 18.613 | 1.028 | 0.046 | 94.8 | Approved |
| Stockholder: simple majority vote | 14.590 | 2.210 | 0.057 | 86.8 | Approved |
| Stockholder: GHG emissions from product use report | 2.940 | 13.790 | 0.127 | 17.6 | Rejected |
| Stockholder: faith based resource groups report | 0.144 | 16.533 | 0.179 | 0.9 | Rejected |
| Stockholder: civil rights and DEI report | 0.101 | 16.644 | 0.112 | 0.6 | Rejected |
Annual meeting remarks
- No management remarks, presentation or shareholder questions from the meeting of 24 Jun 2026 were filed; the Item 5.07 filing reports vote counts only.
| Holder | Shares (m) | Share of class (%) | Basis |
|---|---|---|---|
| BlackRock, Inc. | 1,805.9 | 7.43 | Schedule 13G/A as of 31 Dec 2023, split adjusted |
| Vanguard Capital Management | 1,777.4 | 7.31 | Schedule 13G as of 31 Mar 2026 |
| Jen‑Hsun Huang (trusts, LLCs and foundation) | 870.6 | 3.58 | DEF 14A, incl. 58.7m foundation shares with no pecuniary interest |
| Person | Shares sold | Value ($m) |
|---|---|---|
| Mark A. Stevens (director) | 6,915,922 | 1,495.9 |
| Ajay K. Puri (EVP) | 1,000,000 | 183.0 |
| Debora Shoquist (EVP) | 309,840 | 56.2 |
| Colette M. Kress (CFO) | 243,348 | 44.8 |
| Harvey C. Jones (director) | 250,000 | 44.3 |
| Donald Robertson (former CAO) | 109,986 | 20.6 |
| Timothy S. Teter (EVP) | 60,460 | 13.3 |
| Aarti Shah (director) | 19,000 | 3.4 |
| Stephen C. Neal (director) | 15,500 | 3.3 |
| A. Brooke Seawell (director) | 12,728 | 2.3 |
| John O. Dabiri (director) | 4,255 | 0.8 |
10 Risk Factors
- Item 1A of the FY2026 10-K holds 24 risk factors against 23 in the FY2025 10-K (16,392 words against 15,867). One factor was added, on counterparty risk from commercial arrangements; none was removed; 6 were materially reworded. The Forms 10-Q for Q1 and Q2 FY2027 add factors on commitments and guarantees and on debt. The Q3 FY2027 10-Q, with any Item 1A update, was not filed on 17 Nov 2026; the Q3 forward looking statements name the leadership transition and the search for a new CEO.
| Risk | Disclosure and change |
|---|---|
| Executives and succession | 10-K FY2026: 'highly dependent on the services of our longstanding executive team'. CEO resigned 11 Nov 2026; interim CEO also CFO; Q3 release lists the ability to identify and integrate a new CEO as a factor. |
| Investigation | Forward looking statements in 8-K Ex 99.1 and Ex 99.2 of 17 Nov 2026 name 'the ongoing investigation by an independent committee of NVIDIA's board of directors'. No filing describes its subject. |
| Commitments and guarantees | Supply commitments $390bn; total commitments $518bn plus $32bn neocloud agreements; guarantees $118.0bn, of which $105.0bn for the OpenAI leased SB Energy campus (8-K Ex 99.2, 17 Nov 2026). |
| Customer concentration | Three direct customers 14%, 11% and 11% of Q3 FY2027 revenue; two direct customers 18% and 17% of receivables; DSO 64 days on extended terms. |
| Export controls and China | China incl. Hong Kong $11.05bn of Q3 revenue by customer headquarters; Data Center Hopper shipments to China $2.4bn; Q4 outlook assumes no China Data Center compute revenue. |
| Competition | Customers develop their own ASICs; Broadcom AI semiconductor revenue $16.7bn (+221%) and AMD Data Center $8.55bn (+97%) in their latest filed quarters. |
| Investments | Non marketable securities $65.53bn and marketable equity $44.22bn at 25 Oct 2026; Q3 impairment of $1.8bn on private holdings; TTM equity gains of $30.97bn are part of net income. |
How risk factors changed
- Comparison: 10-K FY2026 filed 25 Feb 2026 acc 0001045810-26-000021 against 10-K FY2025 filed 26 Feb 2025 acc 0001045810-25-000023.
- Item 1A grew to 24 factors and 16,392 words from 23 and 15,867.
- The factor on attracting and retaining executives is near unchanged (body similarity 0.98): it states NVIDIA is highly dependent on its longstanding executive team and that failure to ensure succession planning and smooth transitions could hinder execution; no factor names the CEO.
- Factors on guarantees, commitments and debt were added across the 10-K and the Forms 10-Q for Q1 and Q2 FY2027 as supply commitments rose to $279bn and guarantees to $108.5bn.

| Measure | 10-K FY2025 | 10-K FY2026 |
|---|---|---|
| Risk factors (count) | 23 | 24 |
| Words in Item 1A | 15,867 | 16,392 |
| Change | Risk factor | What changed |
|---|---|---|
| Added | Commercial arrangements expose us to counterparty risks | Capacity purchase obligations and financial guarantees create counterparty risk; at filing NVIDIA had been asked to offer financing and had entered into none. |
| Reworded | Complex laws, regulations and export restrictions | Adds the H20 license requirement of Apr 2025 and the $4.5bn H20 charge, about $60m of H20 revenue under Aug 2025 licenses, and China's preliminary antitrust finding of 15 Sep 2025 on the Mellanox approval. |
| Reworded | Failure to meet evolving industry needs | Adds the Groq IP license with nonrefundable payments and multi year cloud service agreements for research and development (0.86). |
| Reworded | Lead times, supply and demand mismatches | Adds customers' access to energy and capital for data center buildouts and non binding public purchase announcements (0.91). |
| Reworded | Business investments and acquisitions | Adds investment gains and losses, ecosystem investments in unprofitable companies and the OpenAI investment then being finalized (0.93). |
| Reworded | Customer concentration | Updates to FY2026: one direct customer 22% and another 14% of revenue (0.90). |
| Reworded | Product defects | Removes the FY2023 example of a defect in a third party component in certain Data Center products and the related warranty liability (0.91). |
| Filing | Change disclosed |
|---|---|
| 10-Q Q1 FY2027 filed 20 May 2026 | Updates competition, supply and demand (Rubin shipping from 2H FY2027) and export control factors; H200 licenses granted from Feb 2026 with a 25% tariff on inspected shipments. |
| 10-Q Q2 FY2027 filed 26 Aug 2026 | Adds a factor on commitments, guarantees and commercial arrangements (SB Energy, AI cloud capacity purchase commitments, $500bn financing MOUs) and a factor on $33.5bn of notes; export factor adds a $0.4bn H200 charge. |
| 8-K 3 Sep 2026 | Supplementary risk factor: government restrictions on open source models could affect the Hugging Face platform and NVIDIA. |
11 Stock Price, Scenarios & Sensitivity
- NVDA closed at $155.46 on 17 Nov 2026, the session before the Q3 release at 16:20 ET, against $166.19 on 12 Nov (the day of the CEO transition 8-K) and $206.69 on 3 Nov 2026. That close is the 52 week closing low; the 52 week closing high is $239.24 (6 Oct 2026). Highest month end close in five years $228.38 in Sep 2026.
- Valuation at the 17 Nov 2026 close: market value $3.75tn on 24.10bn shares (Q2 10-Q cover, 21 Aug 2026); enterprise value $3.73tn after net cash of $21.14bn. P/E 16.7x TTM GAAP EPS of $9.31; excluding equity securities gains taxed at 16.5% about 18.8x; EV/Sales 10.3x.
- Scenario method: implied price equals TTM Q3 FY2030 GAAP EPS times an exit P/E. EPS is revenue times operating margin plus $2.0bn a year of net interest and other income, taxed at 17%, over 23.62bn shares (24.10bn less 2% for buybacks net of awards). Revenue grows from TTM Q3 FY2027 $361.81bn for three years; equity securities gains are excluded.

Critical factors and core assumptions
| Factor | Current value | Best case requires | Evidence in filings |
|---|---|---|---|
| Data Center growth | +110% in Q3 FY2027; Q4 outlook $130.0bn total revenue | Vera Rubin ramp keeps growth above 25% a year | 8-K Ex 99.1 and Ex 99.2, 17 Nov 2026 |
| Gross margin | 74.8% in Q3; 71.0% to 72.0% guided for Q4 | return to the mid 70s after the initial Rubin ramp | 8-K Ex 99.2 |
| Commitments | $390bn supply, $518bn total, $118.0bn guarantees | converted to shipments without write downs or guarantee payments | 8-K Ex 99.2, 17 Nov 2026 |
| Customer credit | DSO 64 days; $32bn neocloud agreements | neoclouds and OpenAI meet financing, lease and payment terms | 8-K Ex 99.2 |
| Leadership and governance | Interim CEO who is also EVP and CFO; permanent CEO search under way | permanent CEO named without change to roadmap or commitments | 8-K of 12 Nov and 17 Nov 2026 |
| Competition | Broadcom AI semiconductors +221%; AMD Data Center +97% | share held against custom accelerators | peer 8-K filings |
- Revenue base TTM Q3 FY2027 $361.81bn; operating margin TTM 66.1% and Q3 FY2027 66.9%; Q4 FY2027 outlook $130.0bn incl. an additional week.
- Best case: 25% revenue CAGR as Vera Rubin ramps and commitments convert into shipments; operating margin 64%; exit P/E 26x.
- Base case: 12% revenue CAGR, with growth slowing over FY2028 to FY2030 as custom accelerators gain share; operating margin 60%; exit P/E 20x.
- Worst case: revenue falls 8% a year as AI infrastructure spending pauses, commitments lead to write downs and guarantees are called; operating margin 45%; exit P/E 13x.
- Shares down 2% from 24.10bn through buybacks net of stock awards; dividends ($1.00 a year at the current rate) excluded from implied prices.
Scenarios, three years forward
| Measure | Worst case | Base case | Best case |
|---|---|---|---|
| Revenue CAGR, 3 years (%) | (8.0) | 12.0 | 25.0 |
| Revenue, TTM Q3 FY2030 ($bn) | 281.7 | 508.3 | 706.7 |
| Operating margin, TTM Q3 FY2030 (%) | 45.0 | 60.0 | 64.0 |
| Net income, TTM Q3 FY2030 ($bn) | 106.9 | 254.8 | 377.0 |
| EPS, TTM Q3 FY2030 ($) | 4.53 | 10.79 | 15.96 |
| Exit P/E (x) | 13.0 | 20.0 | 26.0 |
| Implied price ($) | 59 | 216 | 415 |
| Change against $155.46 (%) | (62) | 39 | 167 |
| Implied annual return (%) | (27.7) | 11.5 | 38.7 |
| Description | Spending pause, write downs | Growth slows, margin near 60% | Rubin ramp, commitments convert |

Sensitivity analysis
| Revenue CAGR \ Operating margin | 45% | 50% | 55% | 60% | 64% |
|---|---|---|---|---|---|
| (8%) | $91 | $100 | $110 | $120 | $128 |
| 0% | $116 | $129 | $141 | $154 | $164 |
| 12% | $162 | $180 | $198 | $216 | $230 |
| 18% | $189 | $210 | $231 | $252 | $269 |
| 25% | $225 | $250 | $275 | $299 | $319 |
| Exit P/E \ Operating margin | 45% | 50% | 55% | 60% | 64% |
|---|---|---|---|---|---|
| 13x | $105 | $117 | $129 | $140 | $150 |
| 16x | $130 | $144 | $158 | $173 | $184 |
| 20x | $162 | $180 | $198 | $216 | $230 |
| 23x | $187 | $207 | $228 | $248 | $265 |
| 26x | $211 | $234 | $257 | $280 | $299 |
12 What Management Said on the Q3 FY2027 Earnings Call
- Every point in this chapter was said on the Q3 FY2027 earnings call of 17 Nov 2026. Figures stated only on the call are call statements, not filed figures; filed figures are in chapters 1 to 6.
- Speakers: Toshiya Hari of investor relations hosted; Harvey C. Jones spoke as Chair of the Board; Colette Kress was introduced as interim CEO and EVP and CFO. Huang did not speak. Analysts from eight firms asked questions, all answered by Kress except one part answered by Jones.
CEO transition and the committee, as said on the call
- Jones said on the call that the Board has started a search for a permanent CEO, with internal and external candidates. The 12 Nov 2026 8-K states no reason for the resignation, and this post reports none.
- Jones said on the call that the Board established a national security and export control oversight committee of independent directors.
- Jones said the company would take no questions on the circumstances of the resignation or "the ongoing investigation", and that the Board would communicate further when appropriate. He did not say who conducts the investigation or what it concerns.
- None of these call statements appears in an SEC filing. The 8-K of 12 Nov 2026 states no reason for the resignation; the Q3 exhibits name an ongoing investigation by an independent committee and describe no subject.
Demand, Rubin ramp, supply, margin, China and outlook, as said on the call
- Rubin (Kress, call statement): the Rubin platform generated nearly $20bn of revenue in its initial quarter of production shipments; Kress called it the fastest product ramp in NVIDIA's history. NVIDIA filings give no Rubin revenue figure.
- Demand and supply (Kress): she said demand continues to outpace supply and that NVIDIA is working with suppliers to add capacity; she said Vera Rubin Ultra launches next year and Feynman in 2028.
- Gross margin (Kress): she said Q4 FY2027 should "mark the bottom of gross margins", with FY2028 gross margin in the 72% to 73% range (call statement; the filed Q4 outlook is 71.0% to 72.0%).
- China (Kress): she said NVIDIA is "no longer shipping licensed Hopper data center products to China" and that new US Commerce Department export controls were released that week.
- Outlook (Kress, call statement): she said NVIDIA now expects FY2028 revenue growth of about 75%, against about 70% before. The Q4 FY2027 outlook given on the call matches the filed $130.0bn plus or minus 3%.
- Capital returns (Kress): she said NVIDIA plans to use its buyback authorization by the end of FY2028, as the CFO commentary also states.
Questions and answers on the call
| Analyst firm | Question theme | Answer as said on the call |
|---|---|---|
| Morgan Stanley | FY2028 growth outlook under new export rules | Kress: outlook raised to about 75% growth on demand and secured supply; new rules still under review |
| Bank of America | Talent and the leadership transition | Kress: employees are the first priority; Jones: the CEO search will be thorough |
| UBS | Pricing and margins against custom ASICs | Kress: Q4 FY2027 is the bottom for gross margin; 72% to 73% expected for FY2028 |
| Cantor Fitzgerald | Financing support for neoclouds | Kress: selective support, with land, power and shell among top priorities |
| Bernstein | Whether neocloud guarantees are a new approach | Kress: the approach is unchanged from what NVIDIA had communicated |
| Melius Research | Demand in 2028 and policy changes | Kress: demand expected to continue; NVIDIA stays engaged with the government |
| TD Cowen | Capacity allocation across customer groups | Kress: allocation goes to customers ready with land, power, capital and offtake; same pricing for all |
| Goldman Sachs | Capital allocation priorities | Kress: supplier commitments and the buyback authorization through FY2028 among priorities |
Disclaimer
This analysis is for information only and is not financial advice. It is derived from public SEC filings retrieved via sec-api.io and is not a publication of the U.S. Securities and Exchange Commission. Scenario values are model outputs under stated assumptions and are not forecasts. Data as of 17 November 2026.
Sources
All company and peer figures are read from SEC filings retrieved through the sec-api.io MCP server. Chapter 12 statements are from the Q3 FY2027 earnings call, 17 Nov 2026, which is not an SEC filing.
| Form | Period | Filed | Accession number |
|---|---|---|---|
| 8-K Ex 99.1, Ex 99.2, Ex 99.3 | Q3 FY2027 | 17 Nov 2026 | 0001045810-26-000088 |
| 8-K Ex 99.1 | CEO transition | 12 Nov 2026 | 0001045810-26-000082 |
| 8-K Ex 99.1, Ex 99.2 | Q2 FY2027 | 26 Aug 2026 | 0001045810-26-000073 |
| 10-Q | Q2 FY2027 | 26 Aug 2026 | 0001045810-26-000075 |
| 10-Q | Q1 FY2027 | 20 May 2026 | 0001045810-26-000052 |
| 8-K Ex 99.1, Ex 99.2 | Q1 FY2027 | 20 May 2026 | 0001045810-26-000051 |
| 10-K | FY2026 | 25 Feb 2026 | 0001045810-26-000021 |
| 8-K Ex 99.1, Ex 99.2 | Q4 FY2026 | 25 Feb 2026 | 0001045810-26-000019 |
| 10-Q | Q3 FY2026 | 19 Nov 2025 | 0001045810-25-000230 |
| 8-K Ex 99.1, Ex 99.2 | Q3 FY2026 | 19 Nov 2025 | 0001045810-25-000228 |
| 10-Q | Q2 FY2026 | 27 Aug 2025 | 0001045810-25-000209 |
| 10-K | FY2025 | 26 Feb 2025 | 0001045810-25-000023 |
| 10-K | FY2024 | 21 Feb 2024 | 0001045810-24-000029 |
| DEF 14A | 2026 annual meeting | 12 May 2026 | 0001045810-26-000036 |
| 8-K Item 5.07 | 2026 annual meeting | 30 Jun 2026 | 0001045810-26-000056 |
| 8-K Items 1.01, 2.03, 7.01 | SB Energy | 17 Aug 2026 | 0001045810-26-000069 |
| 8-K Item 8.01 | Hugging Face | 3 Sep 2026 | 0001045810-26-000078 |
| 8-K Item 8.01 | Senior notes | 18 Jun 2026 | 0001193125-26-275783 |
| Company | Form | Filed | Accession number |
|---|---|---|---|
| AMD | 8-K Ex 99.1 | 3 Nov 2026 | 0000002488-26-000188 |
| Arista Networks | 8-K Ex 99.1 | 3 Nov 2026 | 0001596532-26-000252 |
| Astera Labs | 8-K Ex 99.1 | 3 Nov 2026 | 0001736297-26-000044 |
| Broadcom | 8-K Ex 99.1 | 2 Sep 2026 | 0001730168-26-000076 |
| Cerebras Systems | 8-K Ex 99.1 | 12 Nov 2026 | 0001628280-26-073366 |
| Cisco | 8-K Ex 99.1 | 12 Nov 2026 | 0000858877-26-000170 |
| CoreWeave | 8-K Ex 99.1 | 10 Nov 2026 | 0001769628-26-000461 |
| Intel | 8-K Ex 99.1 | 29 Oct 2026 | 0000050863-26-000188 |
| Marvell | 8-K Ex 99.1 | 27 Aug 2026 | 0001835632-26-000022 |
| Mobileye | 8-K Ex 99.1 | 29 Oct 2026 | 0001104659-26-119830 |
| Nebius | 6-K | 12 Nov 2026 | 0001104659-26-126008 |
| Oracle | 10-Q | 11 Sep 2026 | 0001193125-26-389274 |
| Qualcomm | 8-K Ex 99.1 | 4 Nov 2026 | 0000804328-26-000127 |
| TSMC | 6-K Ex 99.1 | 13 Nov 2026 | 0001046179-26-000801 |
| NVIDIA | Q3 FY2027 earnings call (not an SEC filing) | 17 Nov 2026 | n/a |
| Filed | Exhibit | Document | Content |
|---|---|---|---|
| 19 Nov 2025 | Ex 99.1 | Q3 FY2026 results release | Revenue $57.0bn, +62%; Data Center $51.2bn, +66%; GAAP EPS $1.30; $37.0bn returned to shareholders in 9M FY2026 |
| 19 Nov 2025 | Ex 99.2 | Q3 FY2026 CFO commentary | Data Center compute $43.0bn (+56%), networking $8.2bn (+162%); Supply related commitments $50.3bn; multi year cloud service agreements $26.0bn |
| 25 Feb 2026 | Ex 99.1 | Q4 and FY2026 results release | Q4 revenue $68.1bn, +73%; FY2026 $215.9bn, +65%; FY2026 GAAP EPS $4.90; $41.1bn returned to shareholders |
| 25 Feb 2026 | Ex 99.2 | Q4 FY2026 CFO commentary | Networking $11.0bn, +263%; hyperscalers slightly over 50% of Data Center revenue; Supply related commitments $95.2bn; cloud service agreements $27.0bn |
| 6 Mar 2026 | Ex 10.1 | FY2027 Variable Compensation Plan | Cash awards tied to FY2027 revenue goals at threshold, base and stretch levels; Target awards: Huang $4.0m (200% of salary); Kress, Puri, Shoquist, Teter $1.5m each (150%) |
| 20 May 2026 | Ex 99.1 | Q1 FY2027 results release | Revenue $81.6bn, +85%; Data Center $75.2bn, +92%; GAAP EPS $2.39; Quarterly dividend to $0.25 from $0.01; $80.0bn added to buyback authorization |
| 20 May 2026 | Ex 99.2 | Q1 FY2027 CFO commentary | Hyperscale about 50% of Data Center revenue; no Hopper shipments to China against $4.6bn a year earlier; Supply related commitments $119.0bn; cloud service commitments $30.0bn |
| 18 Jun 2026 | Ex 1.1 | Underwriting agreement for $25.0bn of notes | Dated 15 Jun 2026 with Goldman Sachs, J.P. Morgan and Morgan Stanley as representatives; Seven tranches due 2028, 2029, 2031, 2033, 2036, 2046 and 2056 |
| 18 Jun 2026 | Ex 4.2 | Officers' certificate setting note terms | Coupons 4.250% (2028) to 5.625% (2056); Issued under the 2016 indenture with Computershare Trust Company as trustee |
| 18 Jun 2026 | Ex 5.1 | Legal opinion on the notes | Opinion on validity of the notes issued under the Form S-3 shelf registration |
| 17 Aug 2026 | Ex 99.1 | SB Energy PORTS‑Pike release | Credit support for an initial 4.25 IT GW with an option on a further 3.75 IT GW; OpenAI the customer for 8 IT GW; NVIDIA to invest $1.5bn in SB Energy; capacity online in phases from 2028 |
| 26 Aug 2026 | Ex 99.1 | Q2 FY2027 results release | Revenue $96.2bn, +106%; Data Center $89.0bn, +117%; GAAP EPS $2.46; About $26.0bn returned to shareholders; $99.0bn buyback authorization remaining |
| 26 Aug 2026 | Ex 99.2 | Q2 FY2027 CFO commentary | Hyperscale $48.7bn (+102%), ACIE $40.3bn (+138%), Edge Computing $7.2bn (+27%); Commitments $279bn supply, $366bn in total; guarantees $108.5bn incl. $105bn SB Energy |
| 12 Nov 2026 | Ex 99.1 | NVIDIA announces CEO transition | Jensen Huang resigned as President, CEO and director, effective immediately; CFO Colette Kress interim CEO while continuing as CFO; search for a permanent CEO with internal and external candidates |
| 17 Nov 2026 | Ex 99.1 | Q3 FY2027 results press release | Revenue $115.84bn (+103%), Data Center $107.6bn (+110%), Edge Computing $8.2bn (+42%); GAAP EPS $2.70; Q4 outlook $130.0bn plus or minus 3% incl. an additional week; quote attributed to Colette Kress as interim CEO and EVP and CFO |
| 17 Nov 2026 | Ex 99.2 | Q3 FY2027 CFO commentary | Hyperscale $60.1bn (+71%), ACIE $47.5bn (+195%); Hopper shipments to China $2.4bn; Supply commitments $390bn against $279bn; total commitments $518bn; neocloud agreements $32bn; guarantees $118.0bn |
| 17 Nov 2026 | Ex 99.3 | Q3 FY2027 supplemental financial information | Revenue by customer headquarters: US $72.90bn, Taiwan $30.30bn, China incl. Hong Kong $11.05bn; Three direct customers 14%, 11% and 11% of Q3 revenue |