TeraWulf Inc. (WULF), Financial Analysis
Insights derived from analysing SEC filings. Independent analysis, not a publication of the SEC.
- Revenue $76.2m in Q3 2026, +50.7% year on year and +70.3% on Q2 2026; HPC lease revenue $63.0m was 82.6% of revenue against 14.2% a year earlier. Rent was $46.0m, up 71% on Q2 2026 rent of $26.9m (Q3 2026 presentation); the rest is power pass through ($5.4m), tenant fit out ($11.3m) and maintenance. Digital asset revenue fell to $13.2m from $43.4m (Q3 2026 10-Q).
- Operating loss $88.2m (115.7% of revenue) against $24.7m a year earlier; costs and expenses $164.5m, +118.5%. Net income $709.9m includes a $728.4m non cash gain on the Google warrants and a $95.0m gain on the Abernathy sale; diluted EPS ($0.03). Adjusted EBITDA, a non GAAP measure, ($12.8m) against $18.1m.
- 102 MW of critical IT capacity generating revenue at 30 Sep 2026, against 18 MW of HPC leasing capacity at 31 Dec 2025 (10-K; the Q4 2025 release counted 39 MW of HPC capacity online); 839 MW contracted with about $27bn of contracted revenue. Lake Mariner: 438 MW for Core42 (60 MW) and Fluidstack (378 MW) with Google backstop, CB‑4 (168 MW) phased in Q4 2026 and CB‑5 (168 MW) targeted for Q1 2027. Justified: about 401 MW leased to Anthropic for 20 years, about $19bn, delivery late 2027 to Q2 2028.
- Google credit support for the Anthropic leases and a Fluor EPC agreement were signed on 4 Nov 2026; Muskie contracted power rose to 1 GW under amended Kentucky Power agreements of Oct 2026, effective upon approval by the Kentucky Public Service Commission. The 50.1% Abernathy stake was sold for about $530m: $250m received in Jul 2026, $150m due by 31 Dec 2026 and about $130m by 30 Apr 2027.
- Debt principal $5.73bn at 30 Sep 2026: $3.20bn of 7.75% WULF Compute secured notes and $2.53bn of convertible notes; cash $1.60bn plus $753m restricted. Q3 2026 interest expense $53.6m against $9.8m; 9M 2026 cash capex $2.23bn against operating cash flow ($178.9m). Revolver raised to about $400m on 23 Oct 2026.
- Shares closed at $12.62 on 13 Nov 2026, 56.5% below the 52 week closing high of $28.98 (18 Jun 2026); EV/Sales 52.2x TTM revenue. Insiders sold $36.1m of stock from 13 Nov 2025 to 30 Sep 2026 and bought $0.44m (Forms 4). Scenario prices three years forward on exit EV/Sales, using the report's assumptions of $4.41bn of Justified build debt and a 611.3m share base: base $16.14, best $38.12, worst $2.22.
Figures are read from the Q3 2026 earnings release and investor presentation (8-K Ex 99.1 and Ex 99.2 of 6 Nov 2026), the Q3 2026 10-Q filed on 6 Nov 2026, the Forms 10-Q for Q1 2025 to Q2 2026, the FY2025 and FY2024 Forms 10-K, the Forms 8-K with all their exhibits, incl. the earnings releases and investor presentations for Q4 2025 to Q3 2026, the Flash Compute presentation and indenture, the Google credit support agreement form, the underwriting agreement and the bridge and revolving credit filings, the 2026 proxy statement, the Item 5.07 vote results and Forms 4 for central index key 1083301, and the filings of the peers used in chapters 2 to 5. TeraWulf files no separate CFO commentary document; CFO points come from the releases. Quarterly cash flows are derived from year to date statements, and Q4 2025 equals FY2025 less 9M 2025. Share price $12.62 is the regular session close of 13 Nov 2026. Accession numbers appear in the Sources appendix.
1 Revenue & Business Model
- Storyline: TeraWulf is moving from bitcoin mining to leasing data center capacity for AI workloads, with construction funded by $5.7bn of debt principal and $1.2bn of 2026 equity raised before most of the rent starts. HPC leasing passed half of revenue in Q1 2026; contracted capacity is 839 MW, of which 102 MW generated revenue at 30 Sep 2026. Chapters 2 to 4 cover the three revenue drivers: Lake Mariner HPC leasing, the Kentucky campuses, and bitcoin mining.
- TeraWulf owns and operates data center campuses and leases critical IT capacity to tenants under 10 to 20 year leases; tenants bring their own computing hardware. Lease revenue includes rent plus power passed through without markup and tenant fit out passed through with a markup (Q3 2026 10-Q). Two segments are reported: HPC leasing and digital asset mining. All operations are in the US.
- Revenue FY2023 $69.2m, FY2024 $140.1m, FY2025 $168.5m, of which HPC lease revenue $16.9m (first leases commenced Jul 2025); TTM Q3 2026 $190.8m. 9M 2026 revenue $155.0m, of which HPC $115.9m (75%).
- Segment profit Q3 2026 (revenue less cost of revenue and operating expenses, before SG&A and depreciation): HPC leasing $10.6m against $5.2m; digital asset mining $1.0m against $23.8m (Note 17).
- Customers: HPC lease revenue came from two customers in 9M 2026 (one in 9M 2025); Core42 and Fluidstack are the Lake Mariner tenants and Anthropic is the contracted Justified tenant. Google backstops Fluidstack and, once each lease's final data hall commences, Anthropic (Q3 2026 10-Q).

| Line | Q1 2025 | Q2 2025 | Q3 2025 | Q4 2025 | Q1 2026 | Q2 2026 | Q3 2026 |
|---|---|---|---|---|---|---|---|
| Revenue ($m) | 34.4 | 47.6 | 50.6 | 35.8 | 34.0 | 44.8 | 76.2 |
| HPC lease revenue ($m) | 0.0 | 0.0 | 7.2 | 9.7 | 21.0 | 31.9 | 63.0 |
| Digital asset revenue ($m) | 34.4 | 47.6 | 43.4 | 26.1 | 13.0 | 12.8 | 13.2 |
| HPC share of revenue (%) | 0.0 | 0.0 | 14.2 | 27.1 | 61.8 | 71.3 | 82.6 |
| Revenue generating critical IT (MW) | n/a | n/a | 18 | 18 | 60 | 81 | 102 |
| Operating income (loss) ($m) | (59.6) | (15.6) | (24.7) | (86.3) | (162.1) | (140.5) | (88.2) |
| Adjusted EBITDA ($m) | (4.7) | 14.5 | 18.1 | (51.1) | (4.1) | (18.3) | (12.8) |
| Net income (loss) ($m) | (61.4) | (18.4) | (455.1) | (126.6) | (427.6) | (939.9) | 709.9 |
2 Lake Mariner HPC Leasing: 102 MW Live, $63.0m of Lease Revenue in Q3 2026
- HPC lease revenue $63.0m in Q3 2026 against $31.9m in Q2 2026 and $7.2m in Q3 2025; 9M 2026 $115.9m. Rent $46.0m, power pass through $5.4m, tenant fit out $11.3m, maintenance and other $0.3m (MD&A).
- Capacity: revenue generating critical IT rose from 18 MW at 31 Dec 2025 to 60 MW (31 Mar 2026), 81 MW (30 Jun 2026) and 102 MW (30 Sep 2026) across WULF Den, CB‑1, CB‑2A, CB‑2B and CB‑3; Core42's 60 MW are fully in service and one Fluidstack lease has commenced. Lake Mariner also had 145 MW of bitcoin mining capacity.
- Two year end 2025 figures as filed: the FY2025 10-K gives 18 critical IT MW of HPC capacity and the Q3 2026 10-Q 18 MW of HPC leasing capacity at 31 Dec 2025, the capacity generating lease revenue; the Q4 2025 release gives 39 critical IT MW of HPC capacity online, listing WULF Den (2 MW), CB‑1 (16 MW) and CB‑2A as operational. This report uses 18 MW.
- Next deliveries: CB‑4 (168 MW) phased in Nov and Dec 2026 and CB‑5 (168 MW) targeted for Q1 2027; the campus targets about 500 MW of gross capacity by early 2027 and about 750 MW under an approved NYISO study. About 97% of WULF Compute construction capex is secured (Q3 2026 presentation).
- Economics as filed: Lake Mariner carries about $8bn of contracted revenue over 10 year leases and about $700m of average annualized NOI once operational; Google backstops about $3.2bn at WULF Compute (Q3 2026 presentation). HPC segment profit was $10.6m in Q3 2026 after development and pre revenue costs.
How demand for leased AI capacity is changing
- Hyperscaler capex in the Sep 2026 quarter: Microsoft $39.4bn (+103%), Alphabet $51.4bn (+114%), Amazon $77.3bn; Oracle $28.5bn (+235%) in its Aug 2026 quarter (company filings).
- Contracted backlogs: Microsoft commercial RPO $677bn (+73%) and Google Cloud backlog $560.8bn at 30 Sep 2026; Oracle RPO $664bn at 31 Aug 2026 (Forms 10-Q).
- AI labs as tenants: Anthropic's S-1 shows 48% of its 6M 2026 revenue came through cloud provider marketplaces; Anthropic is the Justified tenant and Fluidstack the main Lake Mariner tenant.
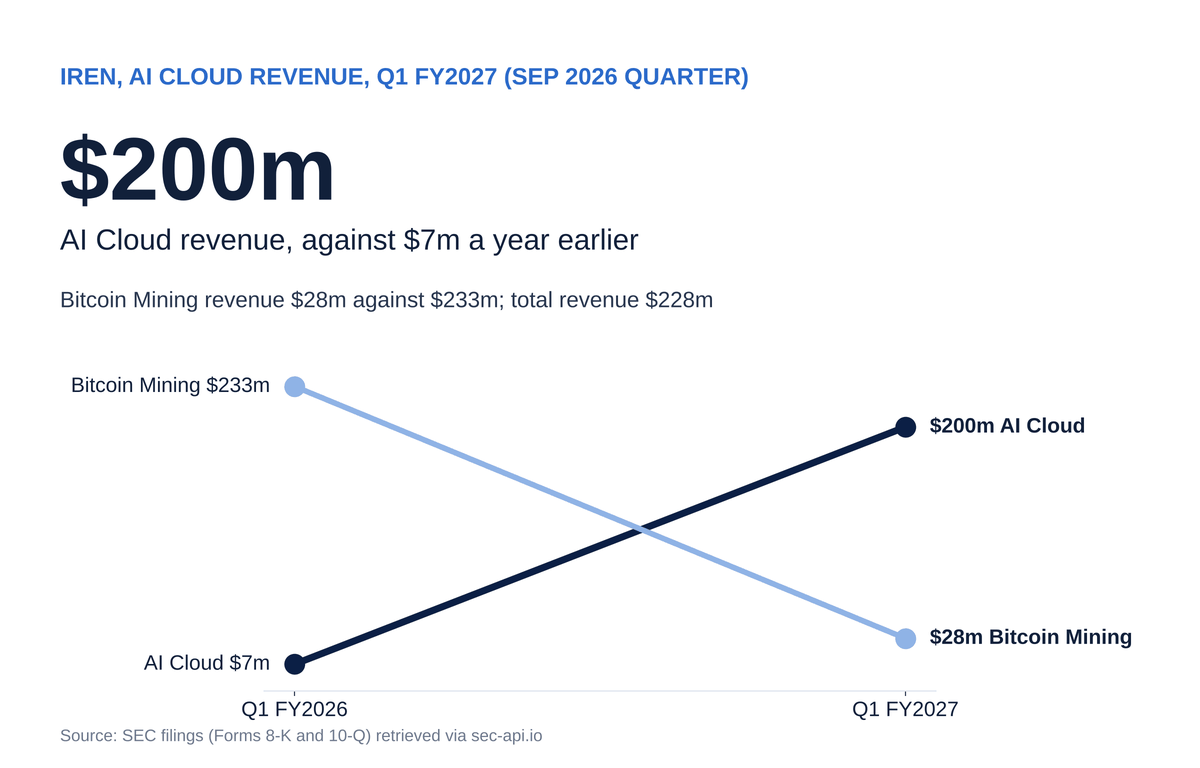
- Miners turned landlords: Core Scientific had about 485 MW of 590 MW for CoreWeave billing at 30 Sep 2026; IREN's AI Cloud was $200m of $228m of revenue in its Sep 2026 quarter.


| Company | Period | Revenue line | Detail |
|---|---|---|---|
| TeraWulf | Q3 2026 | HPC lease revenue $63.0m | 102 MW generating revenue; 438 MW contracted at Lake Mariner |
| Core Scientific | Q3 2026 | Colocation revenue $215.4m | about 485 MW of 590 MW for CoreWeave billing at 30 Sep 2026 |
| IREN | Sep 2026 quarter | AI Cloud revenue $200m | services $135m, lease $65m; Microsoft contract live at Horizon 1 |
| Applied Digital | Aug 2026 quarter | HPC Hosting revenue $262.6m | segment margin 12.7%; leases for about 1.41 GW |
| Hut 8 | Q3 2026 | HPC colocation and cloud $68.4m | $1.07bn revolving credit facility, Sep 2026 |
| Riot Platforms | Q3 2026 | Data center revenue $18.4m | 910 MW Corsicana lease announced Nov 2026 |
| Cipher Digital | Q3 2026 | HPC leasing revenue $5.9m | first lease revenue Aug 2026 |
| CoreWeave (tenant side) | Q3 2026 | Revenue $3.66bn | backlog about $132.5bn; active power above 1.7 GW |
3 Kentucky Campuses: 401 MW Anthropic Lease, Google Backstop and 1 GW of Contracted Power
- Justified (Hawesville, MISO): bought in Feb 2026 for total consideration of about $301.9m incl. a 6.8% minority interest; Kentucky PSC approved up to 482 MW of electric service in Aug 2026. Anthropic leased about 401 MW for 20 years in Jul 2026: about $19bn over the initial term and up to about $33bn with both extensions.
- Delivery: CB‑1 137.6 MW (Q4 2027), CB‑2 137.6 MW (Q1 2028) and CB‑3 125.6 MW (Q2 2028) under the Fluor EPC agreement; about $800m of average annualized NOI once operational (Q3 2026 presentation). At the illustrative $10m to $12m per MW in the presentation's capital formation example, 401 MW implies $4.0bn to $4.8bn of construction cost (derived; report assumption).
- Google credit support (4 Nov 2026): effective at commencement of the final data hall of each lease; on a payment default Google may pay rent and assume the lease, or pay an amortizing termination fee and acquire equity in the landlord. On a payment default Google may also defer its election for a set period while paying unpaid rent (8-K, 4 Nov 2026). The 2025 Fluidstack backstop at Lake Mariner was paid for with 73.58m Google warrants at $0.01.
- Muskie (Grayson, PJM): acquired in May 2026, with all 308 acres owned after the optional parcels were bought in Q3 2026; amended Kentucky Power agreements of Oct 2026 raise contracted power from 500 MW to 1,000 MW, effective upon approval by the Kentucky Public Service Commission, with the original 500 MW agreement in effect until then (10-Q Note 3); the first 500 MW ramps from Q4 2028 and the second by Oct 2029. Pipeline beyond contracts: Lake Mariner expansion 162 MW, Lake Hawkeye about 320 MW, Muskie about 800 MW and Chesapeake (Morgantown, acquisition pending) about 800 MW of critical IT.
How power and site supply is changing
- Contracted power across the sector: CoreWeave above 4.6 GW contracted, Nebius more than 4 GW with a 5 GW year end target, IREN more than 5 GW secured, Applied Digital about 1.41 GW leased (company filings, Q3 2026).
- Large leases at former mining sites: Riot announced a 910 MW Corsicana lease in Nov 2026 with delivery from Jun 2027 to Jul 2028; CleanSpark signed a 20 year, 175 MW lease at Sandersville in Jul 2026 (Forms 10-Q).
- Grid access and regulation: Texas directed PUCT and ERCOT on 3 Aug 2026 to audit data center projects in the interconnection queue (MARA 10-Q); New York paused certain discretionary permits for covered data center projects in Jul 2026 (TeraWulf Q2 2026 10-Q).
- Utility terms: TeraWulf's amended Muskie service agreement requires $435.9m of collateral after approval, $100m of residential bill credits and carrying charges on a planned generating plant (10-Q Note 3).


| Company | Date | Capacity | Detail |
|---|---|---|---|
| TeraWulf | 30 Sep 2026 | 839 MW contracted; about $27bn contracted revenue | Muskie 1 GW of contracted power, pending Kentucky PSC approval; no lease signed |
| IREN | 30 Sep 2026 | more than 5 GW of secured power | property, plant and equipment $12.34bn |
| Applied Digital | 7 Oct 2026 | leases for about 1.41 GW worth about $36bn | Polaris Forge 1 leased to CoreWeave, 250 MW live |
| CoreWeave | 30 Sep 2026 | contracted power above 4.6 GW | active power above 1.7 GW |
| Nebius | Q3 2026 | contracted power more than 4 GW, target 5 GW at end 2026 | Q3 2026 capex $7.30bn |
| Riot Platforms | Nov 2026 | 910 MW Corsicana lease | delivery Jun 2027 to Jul 2028 |
| CleanSpark | 10 Jul 2026 | 175 MW lease at Sandersville, 20 years | 1,817 MW of contracted power |
4 Bitcoin Mining: 186 BTC in Q3 2026, Cash Cost 74% of Value Mined
- Digital asset revenue $13.2m in Q3 2026 against $43.4m, (69.5%); 186 bitcoin mined against 377 and 534 in 9M 2026 against 1,234. Two miner buildings were repurposed or shut for HPC in 9M 2026 (MD&A).
- Unit economics (MD&A): value per bitcoin mined $71,204 against $115,053; cash cost to mine $52,774 against $44,729, or 74.1% of value against 38.9%; power cost $0.060 per kWh against $0.047. Depreciation would add $50,790 per bitcoin in Q3 2026.
- Fleet: about 48,700 miners owned, 33,300 operational; operational hashrate 5.7 EH/s against 8.5 EH/s, 0.6% of a 931 EH/s global network. Mining segment profit $1.0m against $23.8m. TeraWulf mines where it remains economic and does not conflict with HPC development.
How bitcoin mining economics are changing
- Halving: block subsidy 3.125 BTC since Apr 2024, next halving expected around Apr 2028 (MARA 10-K FY2025).
- Price: bitcoin at quarter ends $114,068 (Sep 2025), $87,498 (Dec 2025), $68,222 (Mar 2026), $58,524 (Jun 2026) and $83,556 (Sep 2026) (MARA filings); TeraWulf's average value per bitcoin mined was $71,204 in Q3 2026.
- Network: global hashrate 931 EH/s at 30 Sep 2026 against 1,139 EH/s a year earlier (TeraWulf Q3 2026 10-Q).
- Exits from mining: IREN plans to substantially complete its transition from bitcoin mining by 31 Dec 2026; Cipher stopped mining at Black Pearl in Feb 2026; Core Scientific self mining revenue fell to $12.3m in Q3 2026 (Forms 10-Q).


| Company | Period | Mining revenue ($m) | Growth (%) | Detail |
|---|---|---|---|---|
| MARA | Q3 2026 | 159.0 | (34.3) | 2,247 BTC mined; 71.2 EH/s energized |
| CleanSpark | Jun 2026 quarter | 138.0 | (30.5) | 42.6 EH/s average in Jun 2026 |
| Riot Platforms | Q3 2026 | 116.0 | n/a | 1,637 BTC mined; cost to mine $39,265 per BTC |
| IREN | Sep 2026 quarter | 28.0 | (88.0) | 402 BTC mined; 8.8 EH/s average |
| Cipher Digital | Q3 2026 | 20.8 | (70.9) | mining only at Odessa after Black Pearl conversion |
| TeraWulf | Q3 2026 | 13.2 | (69.5) | 186 BTC mined; 5.7 EH/s operational |
| Core Scientific | Q3 2026 | 12.3 | (78.6) | self mining; $266.5m mining impairment in 9M 2026 |
5 Financial Analysis & Ratios
- GAAP operating margin TTM (250.0%) against (110.5%) in FY2025 and (54.4%) in FY2024. Operating loss TTM $477.1m; SG&A $378.5m, of which stock based compensation $222.0m. Adjusted EBITDA TTM ($86.3m).
- Net loss TTM $784.2m. Quarterly net results move with the fair value of the Google warrants (73.58m shares at $0.01): losses of $216.3m in Q1 2026 and $755.7m in Q2 2026, a gain of $728.4m in Q3 2026 as the share price fell from $24.70 to $14.80 over the quarter.
- Free cash flow TTM ($3.11bn): operating cash flow ($267.1m) less cash capex $2.85bn. 9M 2026 cash interest paid $136.1m against $7.1m in 9M 2025; interest income $86.9m on cash balances (Q3 2026 release).
- Balance sheet at 30 Sep 2026: cash $1.60bn, restricted cash $753.2m, property, plant and equipment $4.58bn ($1.51bn at 31 Dec 2025); debt at carrying value $5.23bn; warrant liabilities $1.09bn; equity $870.5m. Working capital ($79.2m).
- Capital returns and equity: no dividends; no buybacks in 2026 ($200m authorization unused). Equity raised in 2026: 54.51m shares at $19.00 in Apr 2026 (net $1.00bn) and 10.88m shares under the at the market program (net $196.0m, now fully used).
| Line item | FY2023 | FY2024 | FY2025 | TTM Q3 2026 |
|---|---|---|---|---|
| Revenue | 69.2 | 140.1 | 168.5 | 190.8 |
| Gross profit | 41.9 | 77.4 | 85.8 | 132.0 |
| Selling, general and administrative | 37.0 | 70.6 | 147.8 | 378.5 |
| Operating income | (29.4) | (76.2) | (186.2) | (477.1) |
| Net income | (73.4) | (72.4) | (661.4) | (784.2) |
| Diluted EPS ($) | (0.35) | (0.21) | (1.66) | (1.70) |
| Operating cash flow | 4.3 | (24.4) | (123.2) | (267.1) |
| Capital expenditure | (75.2) | (267.9) | (1,060.2) | (2,845.8) |
| Free cash flow | (70.9) | (292.4) | (1,183.4) | (3,112.9) |
| Stock based compensation | 5.9 | 30.9 | 50.9 | 222.0 |
| Cash and investments | 54.4 | 274.1 | 3,266.4 | 1,602.1 |
| Total debt | 123.5 | 487.5 | 5,171.1 | 5,232.3 |
| Total equity | 222.5 | 244.4 | 140.4 | 870.5 |

| Metric | Q3 2025 | Q3 2026 | Change |
|---|---|---|---|
| Revenue ($m) | 50.6 | 76.2 | 50.7% |
| Gross profit ($m) | 33.5 | 51.0 | 52.6% |
| Operating income ($m) | (24.7) | (88.2) | (257.6%) |
| Net income ($m) | (455.1) | 709.9 | n/a |
| Diluted EPS ($) | (1.13) | (0.03) | 97.3% |
| Operating cash flow ($m) | (36.7) | (24.6) | 32.8% |
| Free cash flow ($m) | (268.3) | (876.9) | (226.9%) |
| Operating margin (%) | (48.8) | (115.7) | (67.0 pts) |
| Net margin (%) | (899.7) | 931.3 | 1,831.0 pts |
| Ratio | FY2023 | FY2024 | FY2025 | TTM Q3 2026 |
|---|---|---|---|---|
| Growth and margins | ||||
| Revenue growth (%) | n/a | 102.3 | 20.3 | n/a |
| Gross margin (%) | 60.5 | 55.3 | 50.9 | 69.2 |
| Operating margin (%) | (42.5) | (54.4) | (110.5) | (250.0) |
| Net margin (%) | (106.1) | (51.7) | (392.6) | (410.9) |
| FCF margin (%) | (102.4) | (208.8) | (702.5) | (1,631.1) |
| Cost and investment intensity | ||||
| SBC (%) revenue | 8.5 | 22.1 | 30.2 | 116.3 |
| Capex (%) revenue | 108.6 | 191.3 | 629.4 | 1,491.1 |
| Returns | ||||
| ROE (%) | (33.0) | (31.0) | (343.7) | (90.1) |
| ROA (%) | (19.4) | (12.4) | (18.0) | (9.6) |
| Asset turnover (x) | 0.18 | 0.18 | 0.03 | 0.02 |
| Liquidity and leverage | ||||
| Current ratio (x) | 0.40 | 5.43 | 2.00 | 0.97 |
| Debt to equity (x) | 0.56 | 1.99 | 36.82 | 6.01 |
| Net cash ($bn) | (0.1) | (0.2) | (1.9) | (3.6) |

| Measure | Value |
|---|---|
| Market cap ($bn) | 6.3 |
| Enterprise value ($bn) | 10.0 |
| EV/Sales (TTM) (x) | 52.2 |
| FCF yield (%) | (49.2) |
| Price/Book (x) | 7.3 |
Cost structure and profitability
- Costs and expenses $164.5m in Q3 2026, +118.5%, against revenue +50.7%; operating margin (115.7%) against (48.8%) a year earlier and (313.7%) in Q2 2026.
- SG&A $57.1m, 75% of revenue, after $126.9m in Q2 2026 and $127.8m in Q1 2026; stock based compensation was $30.0m against $83.9m and $101.4m, after Jan 2026 awards. 9M 2026 SG&A includes a $14.4m stock contribution to the company's charitable foundation.
- Operating expenses $39.5m ($4.5m a year earlier) hold HPC site, construction and development costs; the Q3 2026 presentation attributes $18.0m to uncontracted development sites and $11.1m to pre revenue costs at WULF Compute.
- HPC segment profit $10.6m on $63.0m of lease revenue; cost of revenue $15.4m (power and fit out) and operating expenses $37.0m (Note 17).


| Line | Q3 2025 | Q4 2025 | Q1 2026 | Q2 2026 | Q3 2026 |
|---|---|---|---|---|---|
| Cost of revenue ($m) | 17.1 | 18.9 | 2.4 | 12.4 | 25.2 |
| Operating expenses ($m) | 4.5 | 8.8 | 11.2 | 23.4 | 39.5 |
| Selling, general and administrative ($m) | 16.7 | 66.6 | 127.8 | 126.9 | 57.1 |
| Stock based compensation (incl. in lines above) ($m) | 4.3 | 6.6 | 101.4 | 83.9 | 30.0 |
| Depreciation ($m) | 26.5 | 27.7 | 28.5 | 21.2 | 29.6 |
| Interest expense ($m) | 9.8 | 62.4 | 67.1 | 56.4 | 53.6 |
| Costs and expenses as % of revenue | 149 | 341 | 577 | 414 | 216 |
Debt, interest and capital expenditure
- Debt principal $5.73bn at 30 Sep 2026, unchanged from 31 Dec 2025; carrying value $5.23bn. The Q3 2026 presentation gives total debt of $5.8bn incl. $75m of revolver capacity used for letters of credit, and net debt of $3.4bn after cash and all restricted cash; this report uses carrying value less unrestricted cash ($3.63bn). The $100m bridge drawing of Mar 2026 was repaid on 16 Apr 2026 ($7.1m loss on extinguishment).
- Interest expense by quarter from Q1 2025: $4.0m, $4.0m, $9.8m, $62.4m, $67.1m, $56.4m, $53.6m. It is net of capitalized interest ($24.8m in Q3 2026, $60.2m in 9M 2026) and includes amortization of issuance costs and debt discount (Note 10).
- Cash capex by quarter from Q1 2025: $94m, $120m, $232m, $615m, $523m, $856m, $852m; 9M 2026 $2.23bn plus $234.7m for the Justified and Muskie sites. Accrued construction liabilities $329.1m at 30 Sep 2026 against $102.6m at 31 Dec 2025.
- Funding mix in 9M 2026: equity $1.20bn net, Abernathy proceeds $250.0m, bridge $92.8m drawn and $100.1m repaid; tax withholding on vested awards $148.1m (cash flow statement).

| Instrument | Principal or commitment | Maturity | Effective rate | Conversion price | Carrying value |
|---|---|---|---|---|---|
| 7.75% senior secured notes due 2030 (WULF Compute) | $3.20bn | 15 Oct 2030 | 8.7% | n/a | $3.11bn |
| 2.75% convertible notes due 2030 | $500m | 1 Feb 2030 | 3.3% | $8.48 (cap $12.80) | $491.5m |
| 1.00% convertible notes due 2031 | $1.00bn | 1 Sep 2031 | 10.9% | $12.43 (cap $18.76) | $625.3m |
| 0.00% convertible notes due 2032 | $1.025bn | 1 May 2032 | 0.4% | $19.94 | $1.00bn |
| Revolving credit facility (letters of credit $74.2m) | $250m; $400m from 23 Oct 2026 | 7 May 2030 | 1.9% on letters of credit | n/a | $0m drawn |
6 MD&A & Management Commentary
Q3 2026 results: 8-K Ex 99.1 and Ex 99.2 and 10-Q of 6 Nov 2026
- Revenue $76.2m, +50.7% year on year: HPC lease revenue $63.0m against $7.2m as revenue generating capacity rose from 18 MW to 102 MW; digital asset revenue $13.2m against $43.4m as 186 bitcoin were mined against 377 (MD&A).
- Costs (MD&A): cost of revenue $25.2m, up $8.1m, from $10.1m more fit out costs and $5.0m more HPC power, offset by $11.2m less mining power; operating expenses $39.5m against $4.5m, mainly HPC expansion and construction ($35.3m); SG&A $57.1m incl. related party, up $40.5m; the MD&A attributes the $40.2m rise in SG&A excl. related party mainly to $25.7m more stock based compensation and $9.0m more employee costs.
- Non cash items: depreciation $29.6m incl. $7.7m accelerated on a mining building being shut for HPC; impairment of miners $9.7m; loss on 5,010 miners sold or disposed $3.4m. 9M 2026 impairment $35.4m incl. $16.8m of asset retirement cost assumed with Justified.
- Interest: expense $53.6m against $9.8m; stated interest $68.5m, of which $24.8m capitalized into construction; the 2031 convertible notes carry a 10.9% effective rate against a 1.00% coupon (Note 10).
- Abernathy: stake sold effective 5 Jul 2026; equity method investment of $423.6m derecognized, gain $95.0m; deferred consideration of $280.0m booked at a present value of $268.6m (Note 11).
- Muskie collateral and costs (Note 3): $360.7m of letters of credit posted in Q3 2026 under the Kentucky Power agreements, $286.7m of them cash collateralized with a $295.3m deposit; the amended agreements add $100m of residential bill credits from 2028 to 2037, up to $465.4m of carrying charges on a planned generating plant and $125.1m more collateral after approval.
| Item | Outlook | Source |
|---|---|---|
| Annual contracting target | 250 MW to 500 MW of incremental critical IT capacity a year, reaffirmed | 8-K Ex 99.1, 6 Nov 2026 |
| Lake Mariner CB‑4 (168 MW) | phased delivery and rent commencement in Q4 2026 (Nov to Dec); earlier target 2H 2026 | 8-K Ex 99.1 and Ex 99.2, 6 Nov 2026; 8-K Ex 99.1, 5 Aug 2026 |
| Lake Mariner CB‑5 (168 MW) | phased delivery from early 2027 (Q1 2027) | 8-K Ex 99.1, 6 Nov 2026 |
| WULF Compute construction cost | $8m to $10m per critical IT MW, progressing within guidance; about 97% of construction capex secured | 8-K Ex 99.1 and Ex 99.2, 6 Nov 2026 |
| Justified (401 MW, Anthropic) | ready for service from late 2027 to Q2 2028; Jul 2026 filing stated late 2027 to early 2028 | 8-K Ex 99.1, 4 and 6 Nov 2026; 8-K, 6 Jul 2026 |
| Muskie (1 GW contracted power) | first 500 MW ramp from Q4 2028; second 500 MW moved to 2029 from 2H 2030; amended service agreement effective upon approval by the Kentucky Public Service Commission | 8-K, 26 May and 5 Oct 2026; 10-Q Q3 2026 Note 3 |
| Abernathy sale proceeds | $150m by 31 Dec 2026 and about $130m by 30 Apr 2027 still to be received | 8-K Ex 99.1, 6 Nov 2026 |
| Revolver availability | limit before the first Fluidstack commencement raised to $150m; full $400m once the CB‑4 lease commences | 10-Q Q3 2026; 8-K Ex 99.2, 6 Nov 2026 |
Management and CFO commentary
- TeraWulf files no CFO commentary document; the points below come from the releases filed as 8-K Ex 99.1.
- Q3 2026 release (6 Nov 2026), CFO Patrick Fleury: liquidity was added through the Abernathy monetization and the revolver upsize; Lake Mariner is progressing within cost guidance and Justified is supported by investment grade credit.
- Q3 2026 release, CEO Paul Prager: Lake Mariner is delivering contracted capacity, Justified has customer, credit support and construction in place, and Muskie gives a contracted path to 1 GW of power.
- Google and Fluor release (4 Nov 2026): TeraWulf develops and operates the infrastructure and does not invest in computing hardware; Fluor adds engineering and labor capacity as labor availability constrains large data center projects.
- Q2 2026 release (5 Aug 2026): HPC leasing about 71% of revenue; delivery of CB‑3 made $600m of Google's credit support for Fluidstack effective.
- Q1 2026 release (8 May 2026): HPC lease revenue $21.0m from the initial ramp at Lake Mariner; about $3.1bn of cash and restricted cash.
| Speaker | Date and source | Statement |
|---|---|---|
| Paul Prager, Chairman and CEO | 6 Nov 2026, 8-K Ex 99.1 | “Our focus is simple: execute on our commitments, protect our economics” |
| Patrick Fleury, CFO | 4 Nov 2026, 8-K Ex 99.1 | “Cost of capital is fundamental to infrastructure development” |
| Paul Prager, Chairman and CEO | 4 Nov 2026, 8-K Ex 99.1 | “Ultimately, megawatts alone do not create shareholder value” |
| Item | Disclosure |
|---|---|
| 10-K FY2025, business | 245 MW of bitcoin mining and 18 critical IT MW of HPC capacity at Lake Mariner at 31 Dec 2025 (the Q4 2025 release states 39 MW of HPC capacity online); about 49,400 miners, 9.3 EH/s; 141 full time employees, all in the US. |
| 10-K FY2025, contracts | 522 MW contracted across Lake Mariner and Abernathy; leases of 10 to 25 years with escalators; Google backstop for Fluidstack; Core42 paid $90.0m of prepaid rent in 2025. |
| 10-K FY2025, controls and legal | Disclosure controls and internal control effective at 31 Dec 2025 (Deloitte attestation); no material pending legal proceedings. |
| 10-Q Q3 2026, revenue mix | HPC 83% of Q3 revenue (14% in Q3 2025); rent $46.0m, power pass through $5.4m, tenant fit out $11.3m, maintenance $0.3m. |
| 10-Q Q3 2026, mining | 48,700 miners owned, 33,300 operational; operational hashrate 5.7 EH/s against 8.5 EH/s; 145 MW of mining capacity at Lake Mariner; power cost $0.060 per kWh. |
| 10-Q Q3 2026, Google warrants | 73.58m warrants at $0.01 issued for the Fluidstack backstop, 8.44m exercisable after one lease commenced; $515.5m deferred charge now amortized over the lease ($1.1m in Q3 2026). |
| 10-Q Q3 2026, liquidity | Cash $1.60bn and restricted cash $753.2m; working capital ($79.2m); 2030 convertible notes convertible at the holder's option and classed as current. |
| 10-Q Q3 2026, subsequent events | Revolver to $400m (23 Oct 2026); Google credit support and Anthropic lease amendments (4 Nov 2026); Fluor EPC for three Justified buildings; second amended Muskie service agreement (4 Nov 2026). |
7 Sector & Competitor Analysis
- Sector: data center landlords and former bitcoin miners leasing capacity for AI workloads. The FY2025 10-K names data center REITs, independent developers, hyperscalers, infrastructure funds and miners with sites suited for HPC conversion as competitors. CoreWeave and Nebius, GPU cloud operators, are shown for scale.
- Revenue mix, latest filed quarter: HPC or AI revenue was 96% of revenue at Hut 8, 93% at Core Scientific, 88% at IREN, 83% at TeraWulf, 22% at Cipher Digital, 10% at Riot and 0% at MARA.
- Growth, latest quarter year on year: NBIS +571.3%, CORZ +187.1%, CRWV +168.3%, WULF +50.7%, RIOT +0.7%, IREN (5.0%), HUT (14.9%), MARA (34.9%), CIFR (62.8%).
- Net debt at the latest quarter end: CRWV $42.7bn, HUT $7.6bn, NBIS $6.8bn, CIFR $5.4bn, IREN $4.1bn (after $2.26bn of restricted cash, as in the IREN post), WULF $3.6bn, CORZ $3.6bn, MARA $2.1bn.
- Valuation, EV/Sales TTM: WULF 52.2x at $12.62 (13 Nov 2026; market value $6.3bn), NBIS 21.5x ($128.64, 12 Nov 2026; $40.39bn), IREN 17.0x ($18.17, 13 Nov 2026; $7.7bn), CRWV 7.1x ($48.73, 10 Nov 2026; $27.1bn). MARA market value $2.97bn ($7.66, 11 Nov 2026). Peer prices were not collected for the other companies.
| Company | Revenue TTM ($bn) | Revenue growth (%) | Net cash ($bn) |
|---|---|---|---|
| WULF | 0.2 | 50.7 | (3.6) |
| CRWV | 9.9 | 168.3 | (42.7) |
| NBIS | 2.2 | 571.3 | (6.8) |
| IREN | 0.7 | (5.0) | (4.1) |
| CORZ | n/a | 187.1 | (3.6) |
| HUT | n/a | (14.9) | (7.6) |
| CIFR | n/a | (62.8) | (5.4) |
| RIOT | n/a | 0.7 | 0.0 |
| MARA | 0.7 | (34.9) | (2.1) |

| Company | Period | Line as filed | Revenue ($m) | Total revenue ($m) | Share (%) |
|---|---|---|---|---|---|
| TeraWulf | Q3 2026 | HPC lease revenue | 63.0 | 76.2 | 82.6 |
| Core Scientific | Q3 2026 | Colocation | 215.4 | 232.9 | 92.5 |
| IREN | Sep 2026 quarter | AI Cloud | 200.0 | 228.0 | 87.7 |
| Hut 8 | Q3 2026 | HPC colocation and cloud | 68.4 | 71.1 | 96.2 |
| Riot Platforms | Q3 2026 | Data center | 18.4 | 181.4 | 10.1 |
| Cipher Digital | Q3 2026 | HPC leasing | 5.9 | 26.7 | 22.1 |
| Applied Digital | Aug 2026 quarter | HPC Hosting segment | 262.6 | n/a | n/a |
8 Material Events & Contracts
- 20 Forms 8-K from 15 Nov 2025 to 15 Nov 2026: four earnings releases with investor presentations, a preliminary Q1 2026 release, eight financing filings (Flash Compute notes, bridge facility, equity offering, revolver), three site and power filings (Hawesville and Morgantown, Muskie, Muskie expansion), the Anthropic lease and Abernathy sale, the Google credit support agreements, the preferred stock conversion and the annual meeting results.
- Google support is tied to lease commencement: the Fluidstack backstop becomes effective lease by lease at commencement, the Anthropic backstop at commencement of each lease's final data hall; within the first six years Google may elect termination only in limited cases, and the backstop ends once Anthropic holds investment grade ratings for three months (10-Q Note 18).
- Fluidstack leases amended in Jul 2026: two leases raised from 162 MW to 168 MW, commencement by data hall, extra rent for tenant requested scope; the Q2 2026 presentation puts the added revenue at about $500m over the lease term, with TeraWulf funding about $150m of fit out.
- Equity linked securities: convertible notes due 2030 ($500m, conversion price $8.48, capped call to $12.80), 2031 ($1.0bn, $12.43, cap $18.76) and 2032 ($1.025bn, $19.94); Google warrants for 73.58m shares; estimated diluted share count 611.3m at a $10 share price and 611.4m at $12 (Q3 2026 presentation cap table, treasury method).
| Date | Items | Event |
|---|---|---|
| 25 Nov 2025 | 3.03, 8.01 | Mandatory conversion of all Series A convertible preferred stock into common stock on 9 Dec 2025 at 141.9483 shares each (Ex 99.1) |
| 18 Dec 2025 | 7.01, 8.01 | Flash Compute (Abernathy joint venture) investor presentation for a senior secured notes offering (Ex 99.1) |
| 18 Dec 2025 | 7.01 | Flash Compute investor presentation furnished again (Ex 99.1) |
| 18 Dec 2025 | 8.01 | Flash Compute notes upsized to $1.3bn and priced at 7.250% |
| 29 Dec 2025 | 1.01, 2.03 | Flash Compute indenture: $1.3bn 7.250% senior secured notes due 2030; up to $100m capped completion guarantee (Ex 4.1) |
| 2 Feb 2026 | 8.01 | Hawesville, Kentucky site acquired (seller keeps 6.8%); agreement to buy the Morgantown, Maryland generating station, about 210 MW (Ex 99.1) |
| 26 Feb 2026 | 2.02, 7.01 | FY2025 results: revenue $168.5m, adjusted EBITDA ($23.1m), 522 MW contracted (Ex 99.1, Ex 99.2) |
| 16 Mar 2026 | 1.01, 2.03, 7.01 | $500m 364 day delayed draw bridge facility for Hawesville at SOFR + 2.75%; $100m drawn and repaid 16 Apr 2026 (Ex 99.1) |
| 14 Apr 2026 | 2.02, 7.01, 8.01 | Preliminary Q1 2026 results and allocations for a $250m revolving credit facility (Ex 99.1, Ex 99.2) |
| 14 Apr 2026 | 7.01 | Common stock offering priced: 47.4m shares at $19.00, about $900m (Ex 99.1) |
| 16 Apr 2026 | 1.01, 8.01 | Underwriting agreement; 54.51m shares incl. option sold, net proceeds about $1.00bn (Ex 1.1, Ex 5.1, Ex 99.1) |
| 8 May 2026 | 2.02, 7.01 | Q1 2026 results: revenue $34.0m incl. $21.0m HPC lease revenue; 60 MW in service (Ex 99.1, Ex 99.2) |
| 26 May 2026 | 8.01 | Muskie Data Campus, Grayson, Kentucky acquired; Kentucky Power agreements for 500 MW of contracted service, campus planned for up to 1 GW (Ex 99.1) |
| 10 Jun 2026 | 5.07 | Annual meeting: nine directors elected, say on pay approved, Deloitte ratified |
| 6 Jul 2026 | 8.01 | 20 year Anthropic lease for about 401 MW at Justified; sale of the 50.1% Abernathy stake for about $530m (Ex 99.1) |
| 5 Aug 2026 | 2.02, 7.01 | Q2 2026 results: revenue $44.8m incl. $31.9m HPC lease revenue; 102 MW after CB‑3 delivery (Ex 99.1, Ex 99.2) |
| 5 Oct 2026 | 8.01 | Muskie contracted power raised to 1 GW, second 500 MW phase moved to 2029, subject to Kentucky PSC approval (Ex 99.1) |
| 23 Oct 2026 | 1.01, 2.03 | Revolver commitments raised from $250m to about $400m plus about $150m accordion; letter of credit sublimit removed |
| 4 Nov 2026 | 1.01, 7.01, 8.01 | Google credit support agreements for the three Justified leases; Anthropic lease amendments; Fluor EPC agreement (Ex 10.1, Ex 99.1) |
| 6 Nov 2026 | 2.02, 7.01 | Q3 2026 results: revenue $76.2m, HPC lease revenue $63.0m, net income $709.9m on a $728.4m warrant gain (Ex 99.1, Ex 99.2) |
| Contract | Terms |
|---|---|
| Core42 leases (La Lupa, Lake Mariner) | 60 MW, 10 year terms with two five year renewals; $90.0m prepaid rent applied to 50% of base rent; fully in service at 30 Sep 2026. |
| Fluidstack leases (Akela, Lake Mariner) | 378 MW in three leases, 10 year terms with two five year renewals; one lease commenced in Q3 2026, the rest in Q4 2026 and early 2027; Google backstop and 73.58m Google warrants. |
| Anthropic leases (Raylan Data, Justified) | About 401 MW in three buildings; rent runs for 20 years from delivery of the applicable premises, with two five year extensions; about $19bn over the initial term, up to about $33bn with extensions. |
| Google credit support agreements (Justified) | Signed 4 Nov 2026 for CB‑1, CB‑2 and CB‑3; on a payment default Google pays rent and assumes the lease or pays an amortizing termination fee and may take equity in the landlord. |
| Fluor EPC agreement (Justified) | Engineering, procurement, construction and commissioning of three buildings; guaranteed maximum price being set as engineering progresses. |
| Kentucky Power agreements (Muskie) | Amended service agreement for 1,000 MW in two 500 MW phases (Q4 2028 and 2029), effective upon approval by the Kentucky Public Service Commission; the original 500 MW agreement applies until then. Initial terms of 20 years for the first 500 MW and 15 years for the second; service agreement collateral to rise to $435.9m after approval. |
| 7.75% senior secured notes due 2030 (WULF Compute) | $3.2bn issued Oct 2025; semi annual amortization after the initial Lake Mariner phase; secured on WULF Compute assets and pledged Google warrants; 8.7% effective rate. |
| Convertible senior notes | 2.75% due 2030 ($500m), 1.00% due 2031 ($1.0bn) and 0.00% due 2032 ($1.025bn); unsecured; settlement in cash or a mix of cash and shares at TeraWulf's election. |
| Revolving credit agreement (Morgan Stanley Senior Funding) | $250m from 7 May 2026, about $400m from 23 Oct 2026 plus about $150m accordion; SOFR + 1.75%; matures 7 May 2030; minimum liquidity covenant. |
| Abernathy membership interest purchase agreement | 50.1% of FS CS I LLC sold for about $530m in three installments; purchasers' obligations guaranteed and secured by pledged interests. |
9 Ownership, Voting Power & Annual Meeting
- One class of common stock with one vote per share; 501,521,605 shares outstanding at 2 Nov 2026 (10-Q cover). Directors and executive officers held 15.9% at 17 Apr 2026, incl. Paul Prager 8.5% and Nazar Khan 5.7%; Bank of Nova Scotia held 5.6% (2026 proxy). The Q3 2026 presentation states about 25% ownership by management, board and affiliates.
- Annual meeting of 9 Jun 2026 (Item 5.07): 348.3m shares present (80.01%). Nine directors elected; Paul Prager 98.7% of votes cast, Steven Pincus 92.2%. Say on pay 66.1% for (92.3m against). Deloitte ratified with 99.8%.
- Insiders, Forms 4 from 13 Nov 2025 to 30 Sep 2026: sales of $36.1m and purchases of $0.44m. Paul Prager sold 1.10m shares for $23.4m at $16.10 to $26.60 from Mar to Aug 2026; CFO Patrick Fleury sold 0.60m shares for $9.7m on 17 Mar 2026; director Michael Bucella made 13 purchases totaling 29,240 shares.
- Awards: Jan 2026 grants of restricted and performance stock units to the CEO (11.77m units), CTO (9.81m), CFO and Chief Strategy Officer (3.92m each); $257.2m of unrecognized compensation cost at 30 Sep 2026 (10-Q Note 15).
| Proposal | For (m votes) | Against (m votes) | Abstain (m votes) | For as % of votes cast | Result |
|---|---|---|---|---|---|
| Election of Paul Prager (against column shows withheld) | 269.9 | 3.4 | n/a | 98.7 | Elected |
| Election of Steven Pincus, lowest support of nine directors (withheld) | 252.0 | 21.3 | n/a | 92.2 | Elected |
| Advisory vote on executive compensation | 179.8 | 92.3 | 1.3 | 66.1 | Approved |
| Ratification of Deloitte & Touche as auditor for 2026 | 346.6 | 0.6 | 1.1 | 99.8 | Ratified |
Annual meeting remarks
- No management remarks, presentation or shareholder questions from the meeting of 9 Jun 2026 were filed; the Item 5.07 filing reports vote counts only.
| Holder | Shares (m) | Share of common stock (%) |
|---|---|---|
| Paul Prager (CEO, incl. Riesling Power) | 41.71 | 8.5 |
| Riesling Power LLC | 33.55 | 6.8 |
| Nazar Khan (CTO) | 28.23 | 5.7 |
| Bank of Nova Scotia | 27.38 | 5.6 |
| Kerri Langlais (Chief Strategy Officer) | 3.58 | under 1 |
| Patrick Fleury (CFO) | 3.41 | under 1 |
| Directors and executive officers as a group (11) | 78.34 | 15.9 |
| Insider | Shares sold (m) | Sales ($m) | Shares bought | Purchases ($m) |
|---|---|---|---|---|
| Paul Prager, CEO | 1.10 | 23.43 | 0 | 0 |
| Patrick Fleury, CFO | 0.60 | 9.68 | 0 | 0 |
| Walter Carter, director | 0.13 | 1.98 | 0 | 0 |
| Catherine Motz, director | 0.06 | 1.00 | 0 | 0 |
| Michael Bucella, director | 0 | 0 | 29,240 | 0.44 |
10 Risk Factors
- Item 1A of the FY2025 10-K holds 41 risk factors against 47 in the FY2024 10-K (9,430 words against 11,978); 4 added, 10 removed and 7 materially reworded. The Q2 2026 10-Q adds one factor on New York's data center permitting pause; the Q1 and Q3 2026 Forms 10-Q report no material change.
| Risk | Disclosure and change |
|---|---|
| Construction and lease commencement | Revenue from 737 MW depends on finishing CB‑4, CB‑5 and Justified; lessees may terminate after delays beyond set thresholds, which would not trigger the Google backstop (10-K, new factor). |
| Customer concentration | Two customers produced all HPC lease revenue in 9M 2026; Fluidstack holds 378 MW of 438 MW at Lake Mariner and Anthropic all 401 MW at Justified. |
| Indebtedness and funding | Debt principal $5.73bn at 30 Sep 2026; Q3 2026 interest expense $53.6m with $24.8m capitalized; Justified project financing not yet raised; capital raises may be dilutive or restrictive (10-K, reworded). |
| Dilution | Convertible notes with conversion prices of $8.48, $12.43 and $19.94, 73.58m Google warrants and 32.8m unvested awards; a dilution factor was added to the 10-K. |
| Power and interconnection | New 10-K factor on interconnection and transmission access; Muskie collateral rises to $435.9m after approval, with carrying charges of up to $465.4m on a utility generating plant (10-Q Note 3). |
| Data center permitting | New York Executive Order No. 62 of Jul 2026 pauses certain discretionary permits for covered data center projects; the company does not expect a material effect on the Cayuga (Lake Hawkeye) timeline (Q2 2026 10-Q). |
| Bitcoin price and mining economics | Q3 2026 cash cost to mine $52,774 per bitcoin, 74.1% of the $71,204 value mined, against 38.9% a year earlier; miners impaired $9.7m in Q3 2026. |
| Warrant and share price volatility | Google warrant fair value changes moved quarterly results by $755.7m (Q2 2026 loss) and $728.4m (Q3 2026 gain); warrant liabilities $1.09bn at 30 Sep 2026. |
How risk factors changed
- Comparison: 10-K FY2025 filed 27 Feb 2026 acc 0001083301-26-000031 against 10-K FY2024 filed 28 Feb 2025 acc 0001083301-25-000018.
- Groups were reordered: HPC and data center business now leads with 19 of 41 factors; factors that mention bitcoin fell to 18 from 27.
- Item 1A holds 41 factors and 9,430 words against 47 and 11,978 a year earlier.
- Bitcoin is mentioned 103 times against 175 a year earlier; HPC 39 times against 35.
- Google appears for the first time, in the factor on backstop limits; interconnection appears for the first time.
- A data center permitting factor on New York's Jul 2026 executive order was added in the Q2 2026 10-Q.

| Measure | 10-K FY2024 | 10-K FY2025 |
|---|---|---|
| Risk factors (count) | 47 | 41 |
| Words in Item 1A | 11,978 | 9,430 |
| Change | Risk factor | What changed |
|---|---|---|
| Added | Lease commencement delays and backstop limits | Google's backstop of Fluidstack's lease obligations is effective only after each lease commences; a lease terminated for construction delay would not trigger the backstop, and completion guarantees may not be sufficient. |
| Added | Access to interconnection and transmission | Time and cost to secure and expand interconnection and transmission have increased, adding contractual and financial risk for projects under construction. |
| Added | Abernathy joint venture control | Board of managers of the Abernathy joint venture had three TeraWulf and two Fluidstack designees; disagreements could limit control (the stake was sold in Jul 2026). |
| Added | Dilution from convertible notes and warrants | Conversion or exercise of convertible notes and warrants, incl. those issued to business counterparties, dilutes existing holders. |
| Removed | Failure to increase hash rate | Hash rate growth factor dropped as mining capacity is curtailed and repurposed for HPC. |
| Removed | Cost of new miners and equipment | Miner procurement cost factor dropped. |
| Removed | Lake Mariner expansion risks | Folded into the new factor on completing data center campuses on time and on budget. |
| Removed | Economic and geopolitical events | Standalone macroeconomic factor dropped; tariff factor kept. |
| Removed | Financing growth through share issuance | Replaced by a capital access factor that names dilution and restrictive debt terms, and a new dilution factor. |
| Removed | Unregulated digital asset exchanges | Dropped; replaced by a broader factor on cryptocurrency ecosystem failures. |
| Removed | Transaction fees and bitcoin demand | Dropped. |
| Removed | Bitcoin scaling obstacles | Dropped. |
| Removed | Growing hash rate to match network | Dropped with the move away from mining growth. |
| Removed | Power and internet outages | Merged into the power procurement factor. |
| Reworded | HPC strategy may not perform as planned | Now names local labor availability and tariffs among the factors that could affect HPC hosting. |
| Reworded | Completing data center campuses | Rewritten around Lake Mariner and Abernathy: revenue from leases is not realized until construction is complete; lists permitting, utility approvals and contractor failure. |
| Reworded | Power cost, outages and capacity | Merged with the former outage factor and extended to data center customers. |
| Reworded | Access to additional capital | Heading now adds that capital raises may be dilutive or carry restrictive terms; debt holders would rank ahead of shareholders. |
| Reworded | Cyber attacks and data breaches | Shortened from 813 to 207 words and refocused on customer and company data. |
| Reworded | History of operating losses | No longer describes bitcoin mining as the primary business; adds capital investment in data center campuses and lease commencement dependence. |
| Reworded | Cryptocurrency ecosystem failures | Replaces the factor on financially troubled cryptocurrency companies with a broader one on instability, fraud or failures. |
| Filing | Change disclosed |
|---|---|
| 10-Q Q1 2026 filed 8 May 2026 | No material change to the FY2025 10-K risk factors. |
| 10-Q Q2 2026 filed 5 Aug 2026 | One new factor: New York Executive Order No. 62 of Jul 2026 temporarily pauses certain discretionary permits for covered data center projects; the company does not expect it to materially affect the Cayuga Site timeline. |
| 10-Q Q3 2026 filed 6 Nov 2026 | No material change to the FY2025 10-K and subsequent Forms 10-Q. |
11 Stock Price, Scenarios & Sensitivity
- WULF closed at $12.62 on 13 Nov 2026. 52 week closing high $28.98 on 18 Jun 2026 and closing low $10.08 on 5 Nov 2026, the day before the Q3 2026 release; month end closes ranged from $0.64 (Feb 2023) to $25.56 (May 2026).
- Valuation basis: EV/Sales. Market value $6.3bn on 501.5m shares (2 Nov 2026); enterprise value $10.0bn adds net debt of $3.63bn (debt carrying value less cash; restricted cash, leases and warrant liabilities excluded). EV/Sales 52.2x TTM revenue of $190.8m; P/E n/a on the TTM net loss.
- Scenario method: implied price equals TTM Q3 2029 revenue times an exit EV/Sales multiple, less net debt of $8.04bn, divided by diluted shares. Two inputs are the report's own assumptions: $4.41bn of assumed build debt for Justified (401 MW at $11m per MW, the midpoint of the illustrative $10m to $12m per MW in the Q3 2026 presentation; project financing is not yet raised), added to net debt of $3.63bn at 30 Sep 2026; and a share base of 611.3m, the company's estimated diluted count at a $10 share price in the presentation cap table (611.4m at $12), raised 5% to 20% by case.

Critical factors and core assumptions
| Factor | Current value | Best case requires | Evidence in filings |
|---|---|---|---|
| Lake Mariner delivery | 102 MW generating revenue; CB‑4 and CB‑5 336 MW under construction | 438 MW paying rent by Q2 2027 | 8-K Ex 99.1 and Ex 99.2, 6 Nov 2026 |
| Justified delivery and financing | 401 MW leased; Google credit support signed; Fluor EPC; project debt not yet raised | ready for service late 2027 to Q2 2028 at $10m to $12m per MW (report assumption) | 8-K, 4 Nov 2026; 10-Q Note 18 |
| New leases | 839 MW contracted; Muskie 1 GW of contracted power, customer discussions under way | 250 MW to 500 MW signed each year | 8-K Ex 99.1 target; Ex 99.2 pipeline of about 2.1 GW |
| Lease economics | about $1.5bn average annualized NOI on 839 MW once operational | about 85% NOI margin on contracts | 8-K Ex 99.2, 6 Nov 2026 (non GAAP) |
| Cost of debt | 7.75% secured notes, 10.9% effective rate on 2031 converts | investment grade backed project debt for Justified | 10-Q Note 10; Google credit support agreements |
| Dilution | 501.5m shares; 611.3m estimated diluted at $10 (611.4m at $12) | growth funded mainly with project debt | 10-Q cover; Ex 99.2 cap table |
- Revenue base TTM Q3 2026 $190.8m, of which HPC lease revenue $125.6m. Contracted revenue of about $8bn over 10 years at Lake Mariner and about $19bn over 20 years at Justified implies about $1.75bn a year once all 839 MW pay rent (derived).
- Best case: 130% revenue CAGR to $2.32bn as both campuses deliver on schedule and new leases add revenue by 2029; exit EV/Sales 14x; shares up 5%.
- Base case: 108% revenue CAGR to $1.72bn, close to the contracted run rate; exit EV/Sales 11x, about 13x NOI at the 85% target margin; shares up 10%.
- Worst case: 85% revenue CAGR to $1.21bn with Justified delays; exit EV/Sales 8x; shares up 20% from equity funding.
- Bitcoin mining is held flat at a small share of revenue; warrant fair value changes do not enter the EV/Sales method.
Scenarios, three years forward
| Measure | Worst case | Base case | Best case |
|---|---|---|---|
| Revenue CAGR, 3 years (%) | 85.0 | 108.0 | 130.0 |
| Revenue, TTM Q3 2029 ($bn) | 1.2 | 1.7 | 2.3 |
| Exit EV/Sales (x) | 8.0 | 11.0 | 14.0 |
| Implied price ($) | 2.22 | 16.14 | 38.12 |
| Change against $12.62 (%) | (82) | 28 | 202 |
| Implied annual return (%) | (44.0) | 8.5 | 44.6 |
| Description | Justified delays; equity dilution | Contracted run rate reached | Both campuses on schedule; new leases signed |

Sensitivity analysis
| Revenue CAGR \ EV/Sales | 8x | 10x | 11x | 12x | 14x |
|---|---|---|---|---|---|
| 85% | $2.42 | $6.01 | $7.81 | $9.61 | $13.20 |
| 95% | $4.88 | $9.09 | $11.19 | $13.30 | $17.50 |
| 108% | $8.47 | $13.58 | $16.14 | $18.69 | $23.80 |
| 120% | $12.22 | $18.26 | $21.29 | $24.31 | $30.35 |
| 130% | $15.67 | $22.57 | $26.03 | $29.48 | $36.39 |
Disclaimer
This analysis is for information only and is not financial advice. It is derived from public SEC filings retrieved via sec-api.io and is not a publication of the U.S. Securities and Exchange Commission. Scenario values are model outputs under stated assumptions and are not forecasts. Data as of 15 November 2026.
Sources
All company and peer figures are read from SEC filings retrieved through the sec-api.io MCP server. Share prices are regular session closes as dated in the text.
| Form | Period | Filed | Accession number |
|---|---|---|---|
| 8-K | Q3 2026 | 6 Nov 2026 | 0001628280-26-071306 |
| 10-Q | 30 Sep 2026 | 6 Nov 2026 | 0001628280-26-071671 |
| 8-K | 4 Nov 2026 | 0001628280-26-069810 | |
| 8-K | 23 Oct 2026 | 0001628280-26-067100 | |
| 8-K | 5 Oct 2026 | 0001628280-26-064757 | |
| 10-Q | 30 Jun 2026 | 5 Aug 2026 | 0001083301-26-000166 |
| 8-K | Q2 2026 | 5 Aug 2026 | 0001083301-26-000162 |
| 8-K | 6 Jul 2026 | 0001104659-26-080583 | |
| 8-K | 10 Jun 2026 | 0001083301-26-000115 | |
| 8-K | 26 May 2026 | 0001083301-26-000109 | |
| 10-Q | 31 Mar 2026 | 8 May 2026 | 0001083301-26-000092 |
| 8-K | Q1 2026 | 8 May 2026 | 0001083301-26-000083 |
| DEF 14A | 28 Apr 2026 | 0001083301-26-000077 | |
| 8-K | 16 Apr 2026 | 0001104659-26-044387 | |
| 8-K | 14 Apr 2026 | 0001104659-26-043402 | |
| 8-K | 14 Apr 2026 | 0001104659-26-043279 | |
| 8-K | 16 Mar 2026 | 0000950142-26-000720 | |
| 10-K | 31 Dec 2025 | 27 Feb 2026 | 0001083301-26-000031 |
| 8-K | Q4 2025 | 26 Feb 2026 | 0001083301-26-000026 |
| 8-K | 2 Feb 2026 | 0001083301-26-000023 | |
| 8-K | 29 Dec 2025 | 0001104659-25-124839 | |
| 8-K | 18 Dec 2025 | 0001104659-25-122616 | |
| 8-K | 18 Dec 2025 | 0001104659-25-122387 | |
| 8-K | 18 Dec 2025 | 0001104659-25-122293 | |
| 8-K | 25 Nov 2025 | 0001083301-25-000107 | |
| 10-Q | 30 Sep 2025 | 10 Nov 2025 | 0001083301-25-000099 |
| 10-Q | 30 Jun 2025 | 8 Aug 2025 | 0001083301-25-000061 |
| 10-Q | 31 Mar 2025 | 9 May 2025 | 0001083301-25-000038 |
| 10-K | 31 Dec 2024 | 28 Feb 2025 | 0001083301-25-000018 |
| Company | Form | Filed | Accession number |
|---|---|---|---|
| Anthropic | S-1 | Oct 2026 | 0001628280-26-067168 |
| Applied Digital | 8-K Ex 99.1 | 7 Oct 2026 | 0001144879-26-000057 |
| Cipher Digital | 10-Q | 2 Nov 2026 | 0001819989-26-000050 |
| CleanSpark | 10-Q | 6 Aug 2026 | 0001193125-26-338382 |
| Core Scientific | 10-Q | 5 Nov 2026 | 0001839341-26-000030 |
| CoreWeave | 8-K Ex 99.1 Q3 2026 | 10 Nov 2026 | 0001769628-26-000461 |
| CoreWeave | 10-Q | 12 Nov 2026 | 0001769628-26-000465 |
| Hut 8 | 10-Q | 4 Nov 2026 | 0001193125-26-446146 |
| IREN | 8-K Ex 99.1 | 5 Nov 2026 | 0001878848-26-000065 |
| IREN | 10-Q | 5 Nov 2026 | 0001878848-26-000066 |
| MARA | 10-Q | 9 Nov 2026 | 0001507605-26-000028 |
| Nebius | 6-K | 12 Nov 2026 | 0001104659-26-126008 |
| Riot Platforms | 10-Q | 4 Nov 2026 | 0001104659-26-122417 |
| Filed | Exhibit | Document | Content |
|---|---|---|---|
| 25 Nov 2025 | Ex 99.1 | Mandatory conversion of Series A convertible preferred stock | Each preferred share converts into 141.9483 common shares on 9 Dec 2025; Trigger met: share price above 130% of the $10.00 conversion price on at least five trading days from 4 to 24 Nov 2025 |
| 18 Dec 2025 | Ex 99.1 | Flash Compute (Abernathy) investor presentation | Model case: rent $1.47bn over 2026 to 2031 with NOI margin of 84%; Google termination fee backstop of $1.30bn at lease start, amortizing to $742m by 2031 |
| 18 Dec 2025 | 8-K Item 8.01 | Flash Compute notes upsized and priced | $1.3bn of 7.250% senior secured notes due 2030, upsized from $1.275bn; Flash Compute owned 50.1% by TeraWulf and 49.9% by Fluidstack |
| 29 Dec 2025 | Ex 4.1 | Flash Compute indenture, 7.250% senior secured notes due 2030 | $1.3bn issued at par, maturity 31 Dec 2030; amortization starts after campus completion; Capped completion guarantee of up to $100m from the joint venture holding company |
| 2 Feb 2026 | Ex 99.1 | Hawesville (Kentucky) and Morgantown (Maryland) site acquisitions | Hawesville: more than 250 buildable acres with an energized substation; seller received a 6.8% minority interest; Morgantown generating station: about 210 MW of operating capacity, subject to FERC approval |
| 26 Feb 2026 | Ex 99.1 | Q4 and FY2025 results release | FY2025 revenue $168.5m; adjusted EBITDA ($23.1m); cash and restricted cash $3.72bn; 522 critical IT MW contracted, more than $12.8bn of contracted revenue incl. 50.1% of Abernathy |
| 26 Feb 2026 | Ex 99.2 | Q4 2025 investor presentation | Image slides; figures used in the report are taken from the release and the 10-K |
| 16 Mar 2026 | Ex 99.1 | Delayed draw bridge credit agreement for Hawesville | 364 day $500m senior secured bridge facility at SOFR + 2.75%; Minimum liquidity covenant of $100m |
| 14 Apr 2026 | Ex 99.1 and Ex 99.2 | Preliminary Q1 2026 results and revolving credit facility allocations | Allocations received for a $250m senior secured revolving credit facility |
| 14 Apr 2026 | Ex 99.1 | Common stock offering priced | 47.4m shares at $19.00, gross about $900m, upsized from $800m; 7.11m share option |
| 16 Apr 2026 | Ex 1.1, Ex 5.1, Ex 99.1 | Underwriting agreement and offering close | 54.51m shares incl. option closed 16 Apr 2026; net proceeds about $1.00bn |
| 8 May 2026 | Ex 99.1 | Q1 2026 results release | Revenue $34.0m incl. $21.0m HPC lease revenue; 60 MW critical IT capacity for Core42 in service at 31 Mar 2026 |
| 8 May 2026 | Ex 99.2 | Q1 2026 investor presentation | Image slides; figures used are taken from the release and the 10-Q |
| 26 May 2026 | Ex 99.1 | Muskie Data Campus acquisition, Grayson, Kentucky | About 285 acres; supports up to 1 GW over time; Initial 500 MW to ramp from 2H 2028; second 500 MW targeted for 2H 2030 (later moved to 2029) |
| 10 Jun 2026 | 8-K Item 5.07 | Annual meeting results, 9 Jun 2026 | 348.3m shares present, 80.01% of outstanding; Say on pay 179.8m for and 92.3m against |
| 6 Jul 2026 | Ex 99.1 | Anthropic lease at Justified and sale of the Abernathy stake | 20 year lease for about 401 MW of critical IT load with two five year extensions; Abernathy 50.1% interest sold for about $530m in three installments: $250m, $150m by 31 Dec 2026 and about $130m by 30 Apr 2027 |
| 5 Aug 2026 | Ex 99.1 | Q2 2026 results release | Revenue $44.8m incl. $31.9m HPC lease revenue, about 71% of the total; CB‑3 delivery in early Jul 2026 lifted revenue generating capacity to 102 MW and made $600m of Google credit support effective |
| 5 Aug 2026 | Ex 99.2 | Q2 2026 investor presentation | 839 MW leased, 2.1 GW controlled pipeline across five sites, about $27bn of contracted revenue; Lake Mariner lease amendments add about $500m of revenue over the lease term; TeraWulf funds about $150m of tenant fit out |
| 5 Oct 2026 | Ex 99.1 | Muskie contracted power raised to 1 GW | Contracted power raised from 500 MW to 1 GW; second 500 MW phase moved from 2030 to 2029, subject to Kentucky PSC approval; Company plans to upsize its revolver and raise senior secured debt for letter of credit needs |
| 23 Oct 2026 | 8-K Item 1.01 | Revolving credit facility amendment | Commitments raised from $250m to about $400m plus an uncommitted accordion of about $150m; $150m letter of credit sublimit eliminated |
| 4 Nov 2026 | Ex 10.1 | Form of Google credit support agreement for the Justified leases | Three agreements for CB‑1, CB‑2 and CB‑3; backstop effective at commencement of the final data hall of each lease; On a payment default Google may pay rent and assume the lease, or pay a termination fee and take an equity interest in the landlord |
| 4 Nov 2026 | Ex 99.1 | Google credit backstop and Fluor EPC agreement | Credit support for debt financing of about $19bn of Anthropic lease commitments; Alphabet rated AA+ and Aa2; Fluor EPC for three buildings on a guaranteed maximum price basis; ready for service from late 2027 to Q2 2028 |
| 6 Nov 2026 | Ex 99.1 | Q3 2026 results release | Revenue $76.2m incl. $63.0m HPC lease revenue (about 83%); net income $709.9m on a $728.4m warrant fair value gain; adjusted EBITDA ($12.8m); 102 MW operating, 336 MW under construction (CB‑4 and CB‑5); cash, cash equivalents and restricted cash about $2.4bn |
| 6 Nov 2026 | Ex 99.2 | Q3 2026 investor presentation | HPC rent revenue $46.0m, up 71% on Q2 2026; contracted 839 MW and about $27bn of revenue; Lake Mariner about $8bn contracted revenue and about $700m average annualized NOI; Justified about $19bn and about $800m |
Read next
IREN Limited (IREN) Q1 FY2027 Earnings: $200m AI Cloud Revenue, $20.3bn Backlog and $4.8bn of Quarterly Capex, SEC Filing Analysis
November 15, 2026·40 min read
Astera Labs (ALAB) Q3 2026 Earnings: Revenue $584.9m (+154%), Gross Margin 72.3%, Q4 Guide $730m to $750m, SEC Filing Analysis
November 15, 2026·36 min read