Insights derived from analysing SEC filings. Independent analysis, not a publication of the SEC.
Figures come from Forms 10-K for FY2021 to FY2025, Forms 10-Q for 2025 and 2026, and Forms 8-K from Jul 2024 to Sep 2026 with their quarterly earnings exhibits 99.1. Other sources are proxy statements of 2025 and 2026, Schedules 13G, Forms 13F and Forms 4 and 144 filed under central index key 2488, and comparable filings of six peers. The Sources appendix lists the accession number of every filing used. Market prices are closing prices of 30 September 2026.
Data Center revenue doubled. Q2 2026 revenue (to 27 Jun 2026) was $11.54bn, up 50%. Data Center revenue was $6.72bn,
up 107% and 58% of the total. Q3 2026 guidance is about $13.0bn, up 41%, at a non GAAP gross margin of about 56%.
Two 6 GW GPU agreements carry warrants. OpenAI (Oct 2025) plans to deploy 6 GW of Instinct GPUs and Meta (Feb 2026) up to 6 GW, starting with MI450 in H2 2026. Each holds a warrant for up to 160m shares at $0.01. Together the warrants cover 320m shares, 19.6% of shares outstanding. No warrant shares had vested at 27 Jun 2026.
Margins rose. TTM gross margin was 53.2% and GAAP operating margin 15.7%.
Core operating margin, which adds back acquired intangible amortization and restructuring, was 21.1%. FY2025 carried about $440m of net MI308 export control charges.
Commitments grew. Purchase commitments rose to $30.3bn at 27 Jun 2026 from $12.2bn at FY2025 year end. AMD guarantees up to $4.1bn
of partners' data center leases. After the quarter it signed $9.5bn of data center leases, issued $4.75bn of notes and agreed to buy World Labs for
about $8.2bn in stock.
Shares trade at 157x TTM GAAP EPS. At $611.76, shares trade at 157x TTM GAAP EPS and 106x TTM non GAAP EPS of $5.76. The price is 2.9x the end 2025 close and 30.6x the Nov 2025 Analyst Day target of non GAAP EPS above $20.
Scenario values for end FY2029 are $88 (worst), $381 (base) and $709 (best) per share.
Current price is 111x worst case, 42x base case and 28x best case FY2029 core EPS. In the sensitivity analysis,
Data Center revenue and the exit P/E move value the most.
Views on these results differ. Arguments for a lower valuation cite the P/E, warrant dilution of up to 320m shares, lease guarantees, export
controls on China and memory supply. Arguments for a higher valuation cite the OpenAI, Meta, Anthropic and Oracle deployments, the call outlook for Data Center revenue to more than double in 2027 and 2026 hyperscaler capex guidance of $720bn to 745bn.
AMD designs processors and accelerators and outsources manufacturing. Data Center sells EPYC server CPUs, Instinct GPUs, DPUs and AI network
cards. Client and Gaming sells Ryzen PC chips, Radeon graphics and console chips. Embedded sells FPGAs and adaptive chips from Xilinx. Data Center was 54% of TTM revenue.
Acquisitions. Xilinx closed on 14 Feb 2022 for $48.8bn in stock; goodwill rose to $24.2bn. ZT Systems closed on 31 Mar 2025 for $4.4bn.
AMD sold the ZT manufacturing business to Sanmina for $2.4bn in cash plus shares on 27 Oct 2025 and kept the design team.
Customer agreements. OpenAI and Meta: up to 6 GW each, with 160m share warrants. Anthropic: up to 2 GW of MI450 in Helios racks from H1 2027.
Oracle: a cluster with an initial 50,000 MI450 GPUs from Q3 2026. Anthropic and Oracle terms come from earnings releases (8-K Ex 99.1); the H1 2027 Anthropic start comes from the call.
Concentration. No customer reached 10% of revenue in FY2025 or FY2024; one Client and Gaming customer was 18% in FY2023. International sales were
67% of FY2025 revenue. AMD's 10-K states that it depends on a small number of customers for a substantial portion of its business.
Supply and people. TSMC makes the leading edge wafers; assembly and test run mostly in China, Malaysia and Taiwan. About 31,000 employees.
Table 1.1. Revenue by segment
Segment
FY2021
FY2022
FY2023
FY2024
FY2025
TTM
FY2025 y/y
H1 2026 y/y
TTM share
Data Center
3.69bn
6.04bn
6.50bn
12.58bn
16.64bn
22.21bn
32.2%
80.7%
53.8%
Client
6.89bn
6.20bn
4.65bn
7.05bn
10.64bn
11.79bn
50.8%
24.1%
28.6%
Gaming
5.61bn
6.80bn
6.21bn
2.60bn
3.91bn
3.64bn
50.7%
(15.3%)
8.8%
Embedded
246.0m
4.55bn
5.32bn
3.56bn
3.45bn
3.66bn
(2.9%)
12.3%
8.9%
Total revenue
16.43bn
23.60bn
22.68bn
25.79bn
34.64bn
41.30bn
34.3%
44.1%
100.0%
TTM = Q3 2025 to Q2 2026. FY2021 recast to four segments in the FY2022 10-K. Since Q1 2025 Client and Gaming is one reportable segment; AMD still discloses revenue for each.
Table 1.2. Segment operating income
$
FY2021
FY2022
FY2023
FY2024
FY2025
TTM
Data Center
991.0m
1.85bn
1.27bn
3.48bn
3.60bn
6.53bn
Client and Gaming
3.02bn
2.14bn
925.0m
1.19bn
2.85bn
2.75bn
Embedded
44.0m
2.25bn
2.63bn
1.42bn
1.24bn
1.36bn
All Other
(409.0)m
(4.98)bn
(4.42)bn
(4.19)bn
(4.01)bn
(4.15)bn
Data Center segment margin
26.8%
30.6%
19.5%
27.7%
21.7%
29.4%
All Other holds acquired intangible amortization, stock compensation, acquisition costs and restructuring. Data Center operating income includes the MI308 charges.
Table 1.3. Revenue by billing location
Country
FY2021
FY2022
FY2023
FY2024
FY2025
FY2025 share
United States
4.66bn
8.05bn
7.84bn
8.69bn
11.36bn
32.8%
China
4.10bn
5.21bn
3.42bn
6.23bn
7.75bn
22.4%
Taiwan
2.09bn
2.37bn
1.84bn
3.30bn
5.19bn
15.0%
Singapore
1.39bn
1.38bn
2.23bn
3.61bn
4.28bn
12.4%
Japan
2.38bn
4.18bn
4.63bn
1.77bn
n/a
n/a
Europe
1.25bn
1.77bn
2.03bn
1.62bn
n/a
n/a
Other
572.0m
646.0m
695.0m
554.0m
6.05bn
17.5%
China includes Hong Kong. From FY2025, Japan and Europe are in Other. 10-Q filings give no revenue by country.
H1 2026 revenue rose 44.1% to $21.79bn. GAAP operating income was $3.47bn, against $672m in H1 2025,
which carried $800m of MI308 charges. Net income was $3.68bn. Other income of $598m in Q2 2026 includes $483m of gains on long term
investments; core earnings exclude these gains.
Table 2.1. Income statement; TTM = Q3 2025 to Q2 2026
$
FY2021
FY2022
FY2023
FY2024
FY2025
TTM
Revenue
16.43bn
23.60bn
22.68bn
25.79bn
34.64bn
41.30bn
Cost of revenue
(8.51)bn
(13.00)bn
(12.22)bn
(13.06)bn
(17.49)bn
(19.33)bn
Gross profit
7.93bn
10.60bn
10.46bn
12.72bn
17.15bn
21.98bn
Research and development
(2.85)bn
(5.00)bn
(5.87)bn
(6.46)bn
(8.09)bn
(9.39)bn
Marketing, general and administrative
(1.45)bn
(2.34)bn
(2.35)bn
(2.78)bn
(4.14)bn
(4.92)bn
Operating income
3.65bn
1.26bn
401.0m
1.90bn
3.69bn
6.49bn
of which acquired intangible amortization
n/a
(3.55)bn
(2.81)bn
(2.39)bn
(2.25)bn
(2.21)bn
Interest expense
(34.0)m
(88.0)m
(106.0)m
(92.0)m
(131.0)m
(147.0)m
Other income, net
55.0m
8.0m
197.0m
181.0m
577.0m
1.20bn
Income tax
(513.0)m
122.0m
346.0m
(381.0)m
103.0m
(1.10)bn
Net income
3.16bn
1.32bn
854.0m
1.64bn
4.33bn
6.43bn
Diluted EPS, $
2.57
0.84
0.53
1.00
2.65
3.89
Diluted shares, m
1,229
1,571
1,625
1,637
1,636
1,659
Fiscal years end on the last Saturday of December; FY2022 had 53 weeks. FY2025 tax includes an $853m release of uncertain tax positions. Net income includes ZT manufacturing as discontinued operations (FY2025 $66m).
Table 2.2. What changed: FY2025 against FY2024 and H1 2026 against H1 2025
Full year
First half
$
FY2024
FY2025
Change
H1 2025
H1 2026
Change
Revenue
25.79bn
34.64bn
34.3%
15.12bn
21.79bn
44.1%
Data Center
12.58bn
16.64bn
32.2%
6.91bn
12.49bn
80.7%
Client and Gaming
9.65bn
14.55bn
50.8%
6.56bn
7.45bn
13.5%
Embedded
3.56bn
3.45bn
(2.9%)
1.65bn
1.85bn
12.3%
Gross profit
12.72bn
17.15bn
34.8%
6.79bn
11.62bn
71.0%
Research and development
6.46bn
8.09bn
25.3%
3.62bn
4.92bn
36.0%
Marketing, general and administrative
2.78bn
4.14bn
48.9%
1.88bn
2.65bn
41.4%
Operating income
1.90bn
3.69bn
94.4%
672.0m
3.47bn
415.8%
Net income
1.64bn
4.33bn
164.2%
1.58bn
3.68bn
132.8%
Operating cash flow
3.04bn
6.49bn
113.5%
2.40bn
5.32bn
121.6%
Free cash flow
2.40bn
5.52bn
129.5%
1.91bn
4.12bn
116.3%
Stock based compensation
1.41bn
1.64bn
16.4%
733.0m
990.0m
35.1%
Share repurchases
862.0m
1.32bn
52.7%
1.23bn
221.0m
(82.0%)
Gross margin
49.4%
49.5%
0.2 pts
44.9%
53.3%
8.4 pts
Operating margin
7.4%
10.7%
3.3 pts
4.4%
15.9%
11.5 pts
Change shows n/a where either value is negative.
Table 2.3. Core earnings reconciliation
$
FY2025
TTM
Operating income, GAAP
3.69bn
6.49bn
Add: acquired intangible amortization
2.25bn
2.21bn
Add: restructuring
0.0m
0.0m
Operating income, core
5.95bn
8.70bn
Operating margin, core
17.2%
21.1%
Income before tax, GAAP
4.14bn
7.54bn
Less: gains on long term investments
(365.0)m
(855.0)m
Add: acquired intangible amortization
2.25bn
2.21bn
Income before tax, core
6.03bn
8.90bn
Net income, core (13% tax)
5.25bn
7.75bn
Diluted EPS, GAAP / core, $
2.65 / 3.21
3.89 / 4.67
Diluted EPS, company non GAAP, $
4.17
5.76
Core earnings count stock based compensation as a cost and tax income at 13%, the company non GAAP tax rate. Company non GAAP EPS also excludes stock compensation (Ex 99.1 of each quarter).
Table 2.4. Ratio analysis, FY2021 to FY2025 and TTM
Ratio
FY2021
FY2022
FY2023
FY2024
FY2025
TTM
Growth
Revenue growth
n/a
43.6%
(3.9%)
13.7%
34.3%
39.5%
Data Center growth
n/a
63.6%
7.5%
93.6%
32.2%
55.1%
Data Center share
22.5%
25.6%
28.6%
48.8%
48.0%
53.8%
Profitability
Gross margin
48.2%
44.9%
46.1%
49.4%
49.5%
53.2%
Operating margin
22.2%
5.4%
1.8%
7.4%
10.7%
15.7%
Core operating margin
22.2%
20.4%
14.2%
17.4%
17.2%
21.1%
Net margin
19.2%
5.6%
3.8%
6.4%
12.5%
15.6%
FCF margin
19.6%
13.2%
4.9%
9.3%
15.9%
18.7%
ROE
42.2%
4.2%
1.5%
2.9%
7.2%
10.1%
ROA
25.5%
3.3%
1.3%
2.4%
5.9%
8.1%
Cost structure
R&D / revenue
17.3%
21.2%
25.9%
25.0%
23.4%
22.7%
MG&A / revenue
8.8%
9.9%
10.4%
10.8%
12.0%
11.9%
SBC / revenue
2.3%
4.6%
6.1%
5.5%
4.7%
4.6%
Amortization / revenue
0.0%
15.0%
12.4%
9.3%
6.5%
5.4%
Balance sheet and working capital
Goodwill and intangibles / assets
2.3%
71.5%
67.2%
63.2%
54.4%
48.7%
Days sales outstanding
60
64
87
88
67
64
Days inventory
84
146
169
196
190
181
Current ratio
2.02x
2.36x
2.51x
2.62x
2.85x
2.61x
Leverage and returns
Debt / equity
0.04x
0.05x
0.04x
0.03x
0.05x
0.05x
Net debt / EBITDA
(0.81x)
(0.70x)
(1.03x)
(0.69x)
(1.09x)
(1.04x)
Buybacks / FCF
55%
119%
88%
36%
24%
4%
Valuation
EV / sales at year end
10.4x
4.3x
10.4x
7.5x
9.9x
23.9x
P/E at year end
56x
77x
278x
121x
81x
157x
Returns use average equity and assets. EBITDA = operating income plus depreciation and acquired intangible amortization. Year end valuation uses the December close; TTM uses 30 Sep 2026. Prior TTM: Q3 2024 to Q2 2025.
Table 2.5. Balance sheet, period end
$
FY2021
FY2022
FY2023
FY2024
FY2025
27 Jun 2026
Cash and short term investments
3.61bn
5.86bn
5.77bn
5.13bn
10.55bn
13.11bn
Accounts receivable
2.71bn
4.13bn
5.38bn
6.19bn
6.32bn
7.28bn
Inventories
1.96bn
3.77bn
4.35bn
5.73bn
7.92bn
8.47bn
Goodwill
289.0m
24.18bn
24.26bn
24.84bn
25.13bn
25.47bn
Intangible assets
n/a
24.12bn
21.36bn
18.93bn
16.70bn
15.63bn
Total assets
12.42bn
67.58bn
67.89bn
69.23bn
76.93bn
84.46bn
Total debt
313.0m
2.47bn
2.47bn
1.72bn
3.22bn
3.23bn
Net cash
3.29bn
3.39bn
3.31bn
3.41bn
7.33bn
9.88bn
Stockholders' equity
7.50bn
54.75bn
55.89bn
57.57bn
63.00bn
67.22bn
Shares outstanding, m
1,207
1,612
1,616
1,622
1,630
1,632
Table 2.6. Senior notes
Notes
Principal
4.212% notes due 2026
875.0m
4.319% notes due 2028
625.0m
2.375% notes due 2030
750.0m
3.924% notes due 2032
500.0m
4.393% notes due 2052
500.0m
Total at 27 Jun 2026
3.25bn
Issued Aug 2026: notes due 2029 to 2036
4.75bn
A $5.0bn revolving facility (May 2026) and a $5.5bn commercial paper program were undrawn at 27 Jun 2026. Remaining buyback authorization: $9.2bn at 27 Jun 2026. AMD pays no dividend.
AMD guided Q3 2026 revenue to about $13.0bn, plus or minus $0.3bn, up 41%, with a non GAAP gross margin of about 56%. Releases guide one quarter ahead. The 2027 Data Center outlook comes from the call. Multiyear targets come from the Nov 2025 Financial Analyst Day.
Table 3.1. Recent quarters and guidance (earnings releases, Ex 99.1)
Item
Q3 2025
Q4 2025
Q1 2026
Q2 2026
Q3 2026 guide
Revenue
$9.25bn
$10.27bn
$10.25bn
$11.54bn
$13.0bn
Revenue growth y/y
36%
34%
38%
50%
41%
Data Center revenue (share)
$4.34bn (47%)
$5.38bn (52%)
$5.78bn (56%)
$6.72bn (58%)
n/a
Gross margin, GAAP / non GAAP
51.7% / 54%
54.3% / 57%
52.8% / 55%
53.8% / 56%
about 56% non GAAP
Operating margin, non GAAP
24%
28%
25%
27%
n/a
Diluted EPS, GAAP / non GAAP
$0.75 / 1.20
$0.92 / 1.53
$0.84 / 1.37
$1.38 / 1.66
n/a
Free cash flow
$1.53bn
$2.08bn
$2.57bn
$1.56bn
n/a
Sources: 8-K 0000002488-25-000163, 0000002488-26-000014, 0000002488-26-000072 and 0000002488-26-000121. Q4 2025 includes about $390m of MI308 revenue to China and a $360m reserve release.
MD&A, FY2025 10-K. Revenue rose 34% to $34.64bn. Data Center rose 32% on EPYC and Instinct MI350. Client rose 51% on 15% more units and
a 31% higher average price (10-K/A correction). Embedded fell 3%. Other income of $577m came mainly from gains on long term investments.
MD&A, Q2 2026 10-Q. Gross margin was 54%, against 40% in Q2 2025. R&D rose 33% to $2.53bn on AI headcount. H1 operating cash flow from
continuing operations was $5.32bn. International sales were 70% of Q2 revenue.
Earnings call, 4 Aug 2026 (third party transcript summaries). CEO Lisa Su said Helios rack shipments start in
Q3 2026 and ramp into 2027. She expects Data Center revenue to more than double in 2027, with server CPU revenue up more than 70%, and expects to
"significantly exceed our $20 annual EPS target".
Financial Analyst Day, 11 Nov 2025 (company materials). Targets over three to five years: revenue growth above 35% a year, Data Center above 60%,
Data Center AI above 80%, non GAAP operating margin above 35% and non GAAP EPS above $20.
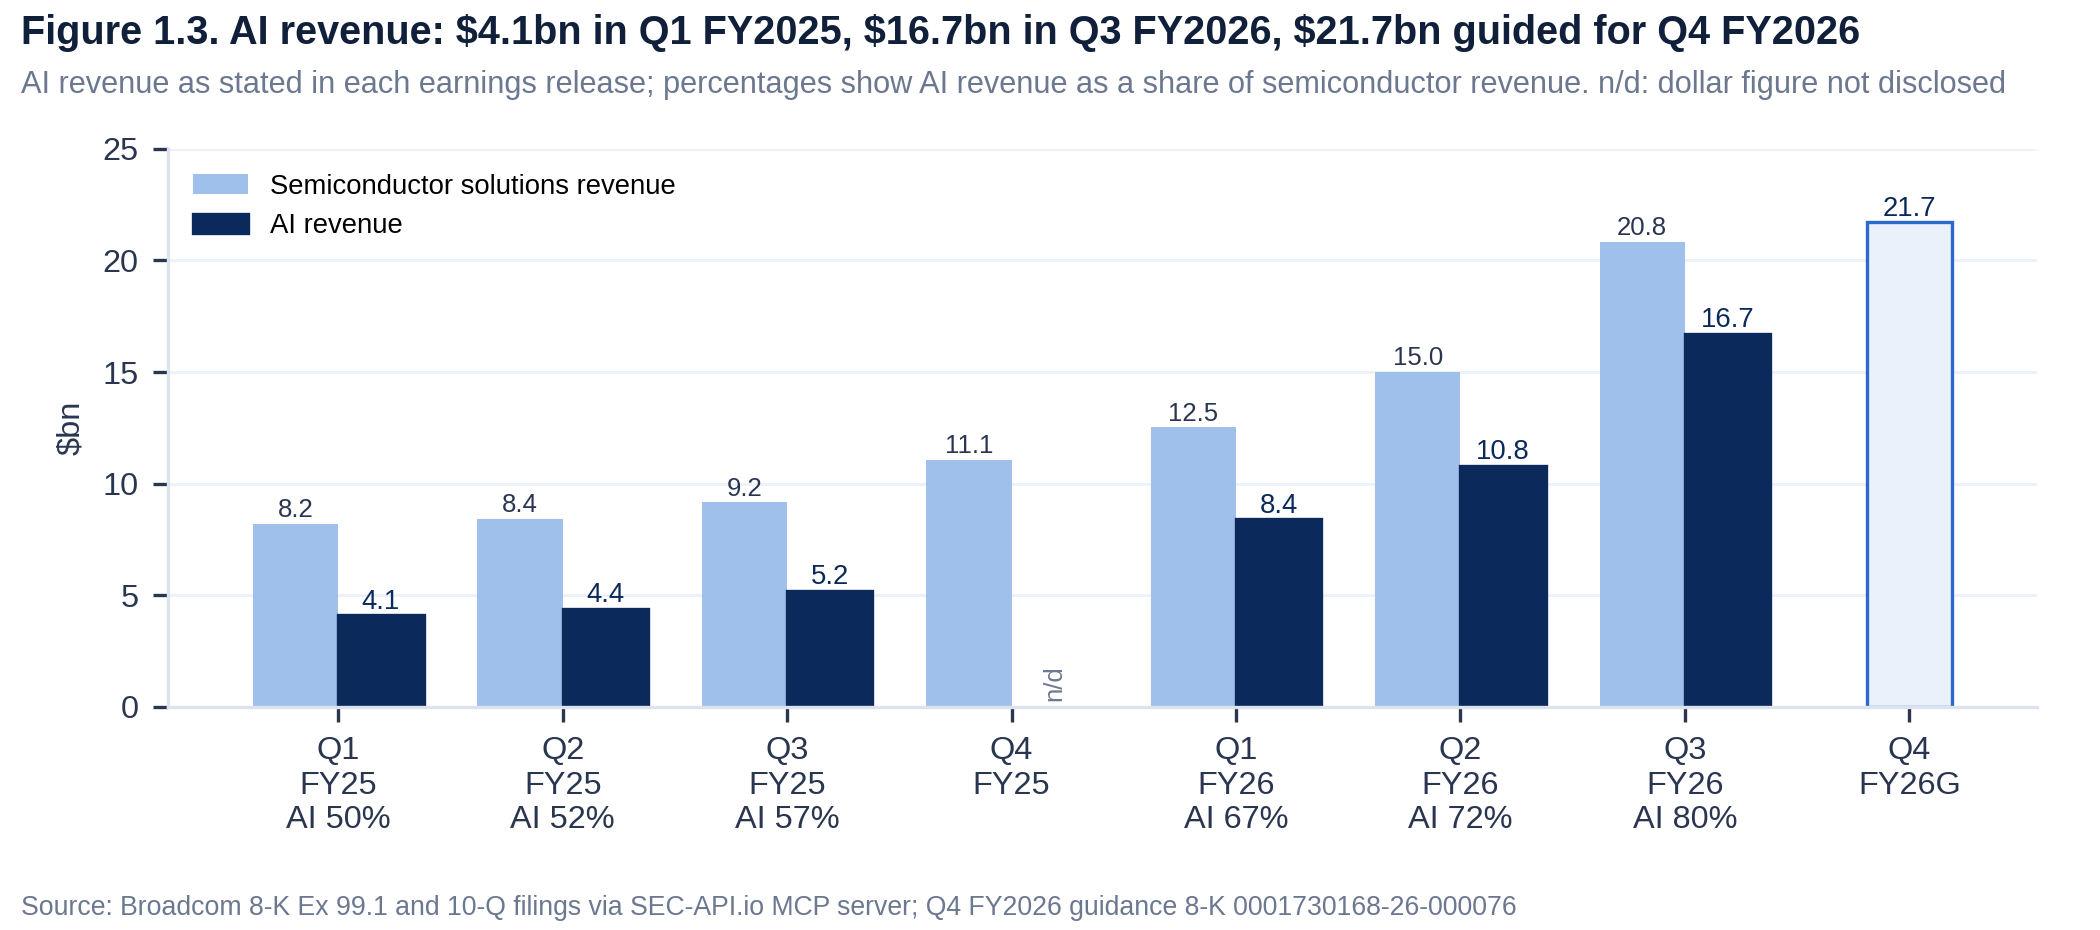
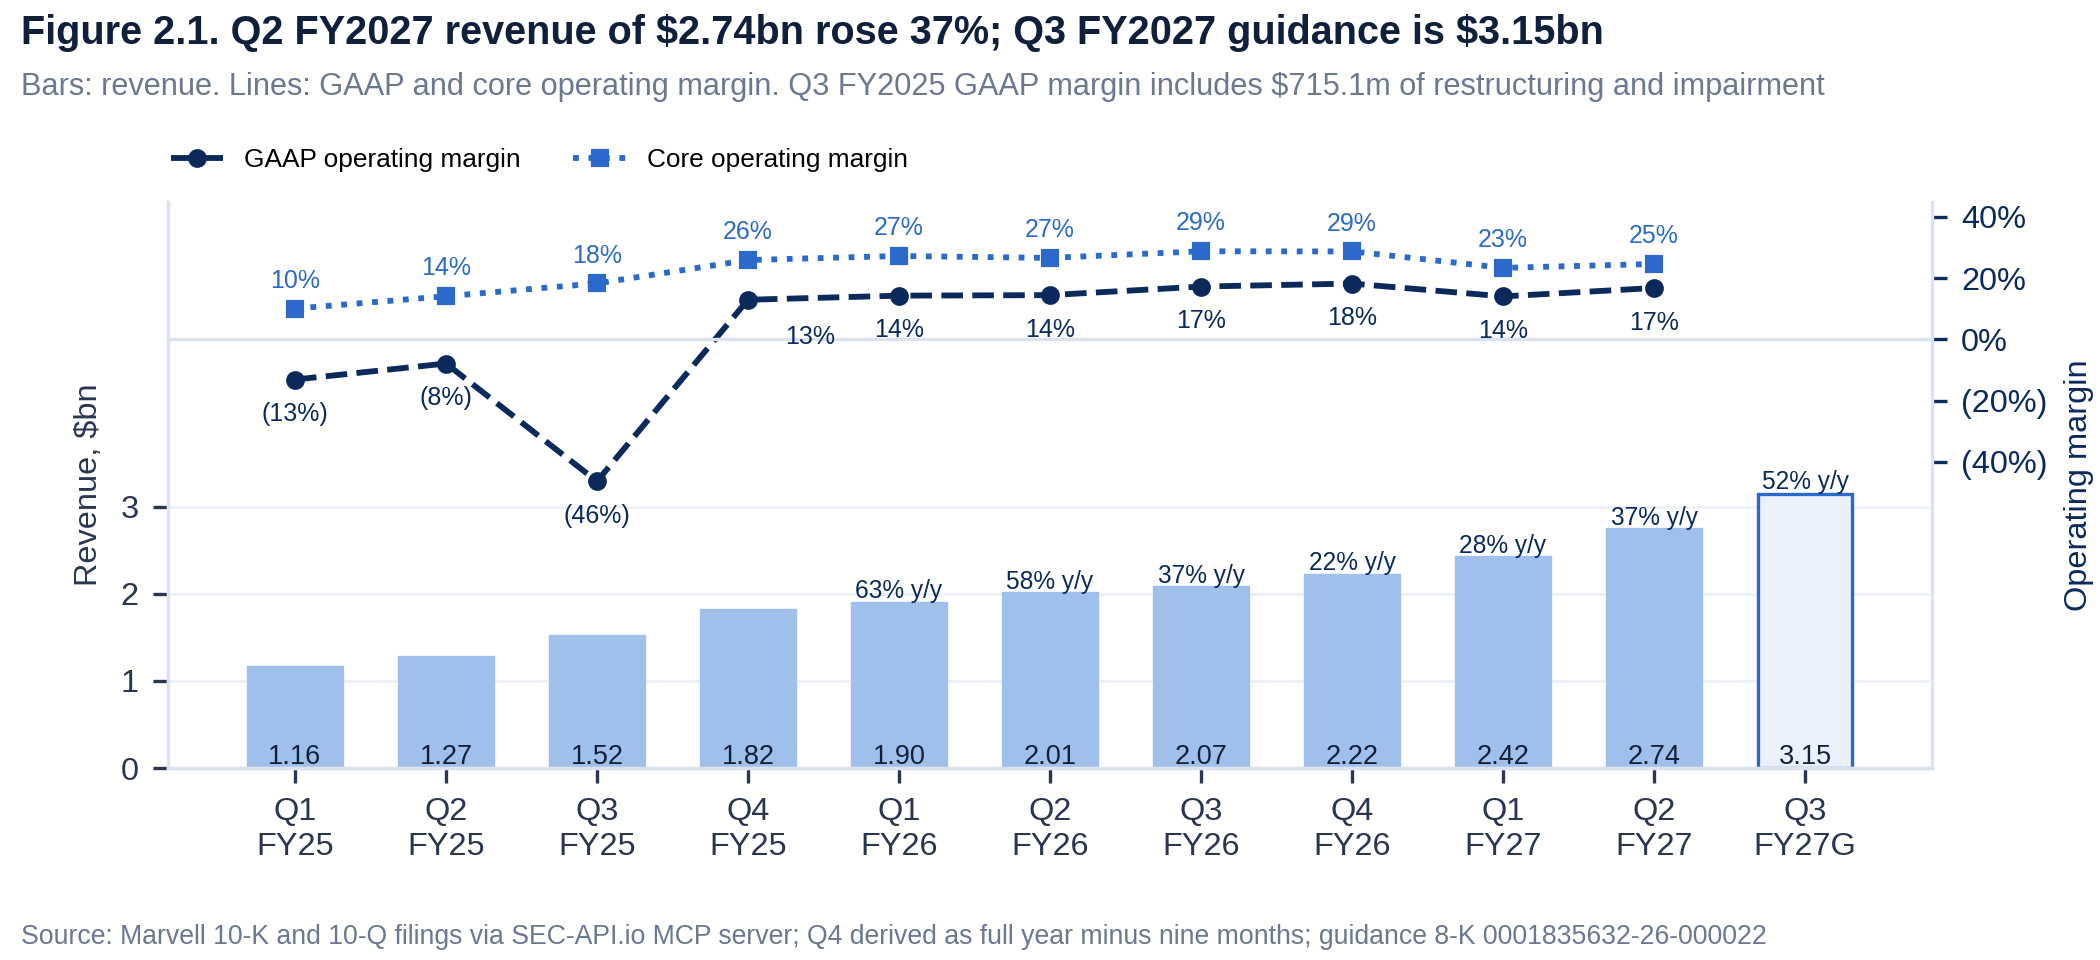
AMD's year to date revenue growth of 44.1% is below Micron (203.0%), NVIDIA (95.8%) and Broadcom (55.0%),
and above Marvell, Intel and Qualcomm. Its TTM gross margin of 53.2% compares with 74.7% at NVIDIA and 38.6% at Intel. Its TTM GAAP
P/E of 157x is the highest in the group.
Hyperscaler capital spending. Microsoft spent $115.9bn in its year to Jun 2026, Amazon $131.8bn in 2025, Alphabet $91.4bn and Meta
$69.7bn (10-K filings). Their combined 2026 guidance is about $720bn to 745bn; Meta's is from its 8-K, the others from earnings calls.
Accelerators. Dell'Oro projects the data center accelerator market to grow 25% a year over five years (Feb 2026). AMD put data center market size at $1tn by 2030 (Analyst Day).
Server and PC CPUs. Mercury Research put AMD at 34.5% of server CPU units in Q2 2026, up from 27.3% a year earlier, and 46.2% of server CPU revenue in
Q1 2026 (as reported by The Register and Tom's Hardware). IDC counted 68.2m PCs shipped in Q2 2026, down 4.9%.
China and memory. Revenue billed to China, including Hong Kong, was $7.75bn in FY2025, 22% of revenue. Licensed MI325 chips for China must be inspected in the US first and carry a 25% tariff on that import (Q2 2026 10-Q). The 10-Q also cites an industry wide memory shortage and higher memory prices.
Table 4.1. Peer comparison, TTM to the latest 10-Q; market data at 30 Sep 2026
Company
Year end
Revenue
Growth YTD
Gross margin
Operating margin
FCF margin
R&D / revenue
Market cap, $
P/E TTM
AMD
FY Dec
41.30bn
44.1%
53.2%
15.7%
18.7%
22.7%
998.7bn
157x
NVIDIA
FY Jan
302.97bn
95.8%
74.7%
65.2%
41.9%
7.8%
5.51tn
29x
Intel
FY Dec
57.03bn
16.4%
38.6%
(0.1%)
5.0%
23.1%
631.3bn
n/m
Broadcom
FY Nov
89.10bn
55.0%
68.8%
48.0%
44.2%
13.3%
1.66tn
44x
Qualcomm
FY Sep
44.07bn
(0.7%)
54.2%
23.2%
23.6%
22.4%
196.6bn
21x
Marvell
FY Jan
9.45bn
32.2%
52.2%
16.5%
18.3%
25.8%
238.5bn
88x
Micron
FY Aug
90.27bn
203.0%
72.6%
65.6%
29.0%
5.3%
1.20tn
24x
Growth compares the latest fiscal year to date with the prior year period. P/E uses filed TTM diluted EPS; Micron P/E uses FY2026 EPS to 3 Sep 2026 (8-K), other Micron columns TTM to 28 May 2026. NVIDIA TTM earnings include equity security gains; Intel has a TTM loss. AMD FCF uses continuing operations.
In the year to Sep 2026 AMD signed GPU agreements with OpenAI and Meta that carry share warrants, sold ZT Systems manufacturing, issued
$4.75bn of notes, opened a $5.0bn credit line and agreed to buy World Labs in stock.
Table 5.1. FY2025 10-K items and Q2 2026 10-Q updates
Item
Content
Items 1 and 7, Business and MD&A
Three segments plus All Other; about 31,000 employees. No customer at 10% of FY2025 revenue. Competitors named: Intel and NVIDIA in data center, Intel and Arm based PCs, NVIDIA in graphics, Altera and Lattice in FPGAs.
Item 1A, Risk factors
FY2025 against FY2024: 16 new and 23 reworded paragraphs. New topics: MI308 licenses and the 15% revenue share US officials expect, the AI Diffusion Rule, tariffs, the NVIDIA and Intel partnership, guarantees of partner obligations and customer financing requests.
Q2 2026 10-Q, Part II Item 1A
Adds MI325 licenses with a 25% tariff, Helios rack shipments in H2 2026, the industry wide memory shortage, receivables factoring and two 2026 Chinese decrees allowing countermeasures against firms that follow US controls.
Item 1C, Cybersecurity
Program based on NIST CSF; Audit and Finance Committee briefed quarterly.
Item 3, Legal proceedings
No material legal proceedings at 27 Dec 2025.
Item 9A, Controls
Controls were effective at 27 Dec 2025; Ernst & Young audited internal control.
10-K 0000002488-26-000018 and 10-K/A 0000002488-26-000021; 10-Q 0000002488-26-000123; risk factor comparison against 10-K 0000002488-25-000012.
Table 5.2. Form 8-K events, Jul 2025 to Sep 2026
Filed
Items
Event
28 Sep 2026
3.02
Agreement to buy World Labs for about $8.2bn in AMD stock
19 Aug 2026
5.02
Tim Ryan joins the board; Joseph Householder retires
17 Aug 2026
1.01, 2.03
$4.75bn of senior notes issued, due 2029 to 2036
4 Aug 2026
2.02, 7.01
Q2 2026 results: revenue $11.54bn (+50%); Data Center $6.72bn (+107%); Q3 guidance $13.0bn
1 Jul 2026
5.02
Executive pay: 2026 salaries and long term incentive targets (CEO $36.0m)
15 May 2026
1.01, 1.02, 2.03, 5.02, 5.07
Annual meeting results; new $5.0bn revolving facility
5 May 2026
2.02, 7.01
Q1 2026 results: revenue $10.25bn (+38%); Data Center $5.78bn (+57%)
24 Feb 2026
1.01, 3.02, 7.01
Meta agreement for up to 6 GW of Instinct GPUs; warrant for up to 160m shares at $0.01
17 Feb 2026
5.02
CEO award of $75m target performance shares tied to share price hurdles through 2031
Shareholders elected all eight directors, ratified the auditor and added 65m shares to the equity plan. Say on pay passed with 92.6% of
votes cast for or against, up from 85.6% in 2025. A shareholder proposal to let holders of 10% call a special meeting received
37.5%. About 1,270m of 1,630m shares were represented (computed).
Board. Abhi Talwalkar had the lowest support, 91.7%; Lisa Su had
93.3%. In 2025 a charter amendment limiting officer liability failed; it needed a majority of shares outstanding.
Pay. Lisa Su's reported pay was $55.2m in FY2025, $31.0m in FY2024 and $30.3m in FY2023.
In Feb 2026 the board granted her a one time award of $75m target performance shares that pay 0% to 200% on share price hurdles through Mar 2031,
with the top level at $600. CEO pay ratio was 341 to 1 (DEF 14A 0001193125-26-129057).
Table 6.1. Proposals and support (for as % of for plus against)
Proposal
Board view
2026
2025
Outcome
Say on pay
For
92.6%
85.6%
Approved
Ratify Ernst & Young
For
93.3%
93.1%
Approved
Equity plan, 65m more shares (2026)
For
97.1%
n/a
Approved
Special meeting right (shareholder)
Against
37.5%
12.2%
Rejected
Broker non votes: 266.5m in 2026. The 2025 proposal asked to remove the holding requirement. Sources: 8-K 0001193125-26-226746, 0000002488-25-000064 and 8-K/A 0000002488-25-000089.
Table 6.2. Director elections, support as % of for plus against
Insiders sold $373m of stock in the twelve months to Sep 2026 and made no open market purchases. Of this, $345m was sold under Rule 10b5-1 plans, including $239m by Lisa Su. AMD withheld a further $230m of shares
for tax on vesting awards. Vanguard Capital Management held 7.48% at 31 Mar 2026 (Schedule 13G).
Table 6.3. Largest institutional holders from Form 13F, shares m
Holder
30 Jun 2026
% of shares
31 Mar 2026
31 Dec 2025
Change since Dec 2025
BlackRock
150.3
9.2%
n/a
147.5
1.9%
Vanguard
144.4
8.8%
143.5
158.5
(8.9%)
State Street
74.4
4.6%
74.8
74.9
(0.7%)
Invesco
53.2
3.3%
50.4
52.0
2.2%
JPMorgan Chase
40.3
2.5%
24.2
20.9
92.8%
Geode Capital Management
39.6
2.4%
39.8
37.6
5.3%
T. Rowe Price Associates
35.9
2.2%
28.8
20.3
76.8%
FMR
25.6
1.6%
15.3
14.3
78.6%
Morgan Stanley
24.3
1.5%
23.8
n/a
n/a
Norges Bank
23.4
1.4%
n/a
23.0
1.5%
n/a: filing not retrieved or position absent from the data. Holders selected from about 35 large managers. Invesco includes amendments for its Nasdaq 100 holdings from Q4 2025.
Table 6.4. Insider sales, Oct 2025 to Sep 2026, $m (Form 4)
Insider
Role
Sales
Of which 10b5-1
Lisa Su
Chair and CEO
239.2
239.2
Mark Papermaster
CTO
55.5
55.5
Forrest Norrod
EVP, Data Center
33.7
33.7
Darren Grasby
EVP and CSO
22.3
0.0
Jean Hu
CFO
14.2
14.2
Nora Denzel
Director
5.5
0.0
Ava Hahn
General Counsel
2.8
2.8
Total
373.2
345.4
75 Form 4 and 3 Form 3 filings; one Form 4 reported zero transactions. Forms 144 covered about $445m of proposed sales.
EV to sales was 9.9x at the Dec 2025 close. It is now 23.9x TTM revenue and 20.0x the
model FY2026 revenue of $49.48bn. Market capitalization is $998.7bn. TTM free cash flow is 0.8% of market capitalization.
Closing prices over 52 weeks ranged from $164.01 (1 Oct 2025) to $630.63 (25 Sep 2026).
Table 7.1. Fiscal year end valuation (December close)
Fiscal year
Market cap, $bn
Price, $
Diluted EPS, $
EV / sales
FY21
174
143.90
2.57
10.4x
FY22
104
64.77
0.84
4.3x
FY23
238
147.41
0.53
10.4x
FY24
196
120.79
1.00
7.5x
FY25
349
214.16
2.65
9.9x
30 Sep 2026
999
611.76
3.89 TTM
23.9x
EV at 30 Sep 2026 uses the 27 Jun 2026 balance sheet, before the $4.75bn Aug 2026 notes.
Scenarios start from model FY2026 revenue of $49.48bn. FY2029 core EPS is $5.51 (worst),
$14.66 (base) and $22.14 (best), against $5.75 for FY2026 on a core basis. Implied
values per share at end FY2029 are $88, $381 and $709.
Table 8.1. Scenario assumptions, FY2027 to FY2029
Driver
Worst
Base
Best
Data Center growth FY2027 / FY2028 / FY2029
20% / 5% / (5%)
70% / 35% / 20%
100% / 50% / 35%
Other segments growth a year
0%
5%
10%
Core operating margin FY2027 / FY2028 / FY2029
21% / 20% / 19%
26% / 28% / 30%
30% / 33% / 35%
Warrant shares issued, m (cumulative by FY2029)
20
180
320
Exit P/E on FY2029 core EPS
16x
26x
32x
Common to all
FY2026 base year: revenue $49.5bn, made of H1 actual, Q3 guidance of $13.0bn and Q4 at 13% above Q3 (model value). Data Center $29.1bn: H1 actual plus 60% of H2 revenue; other segments $20.4bn. Core operating income $10.6bn (21.5%), with H2 at the Q2 2026 core margin of 22.0%. Net interest and other income $0.3bn a year; tax rate 13%; 1,659m diluted shares in FY2026, plus 0.5% a year. World Labs shares and lease guarantee losses excluded.
Demand. Best case follows the call outlook for Data Center to more than double in 2027. Base case uses 70%, 35% and 20% growth. Worst case uses 20%, 5% and (5%), as hyperscaler spending slows or GPU deployments slip. Other segments grow 0% to 10% a year.
Margin. Core margin counts stock compensation (4.6% of TTM revenue) as a cost and excludes acquired intangible amortization and restructuring.
In the base case it rises from 21.5% in FY2026 to 30% in FY2029.
Per share. Warrant shares vest as OpenAI and Meta take GPUs and as the share price passes targets up to $600; the scenarios issue 20m to 320m
of them. Warrant fair value reduces revenue as related sales are booked; the model excludes this effect.
Excluded. World Labs, other acquisitions, guarantee payments, changes in export rules and one off items.
1 of 25 combinations in Figure 9.1 reach today's $611.76: $630 at 34x and a 38% margin. 1 of 25 combinations in Table 9.1 reach it: $651 at 34x and 140% of base.
Table 9.1. Value per share, end FY2029, by Data Center revenue and exit P/E, base case margin
P/E \ Data Center
60% of base
80% of base
100% of base
120% of base
140% of base
18x
183
224
264
304
345
22x
224
273
323
372
421
26x
265
323
381
440
498
30x
305
373
440
507
575
34x
346
422
499
575
651
Base Data Center revenue: $80.2bn in FY2029. Shading: values at or above $611.76 in blue.
Dilution. If all 320m warrant shares vest, the share count rises 19.6%. World Labs adds about $8.2bn of stock, about
13m shares at today's price.
Export controls. FY2025 carried about $440m of net MI308 charges. US officials expect 15% of licensed MI308 China revenue; the 10-K notes that the US has yet to publish a regulation.
Rates. All notes are fixed rate. Net cash was $9.9bn at 27 Jun 2026.
Data. Financial statements from XBRL in the 10-K for FY2021 to FY2025 and 10-Q filings for Q1 2025 to Q2 2026, retrieved through the SEC-API.io
MCP server. Q4 2025 equals full year less the first nine months; quarterly cash flows are derived from year to date statements.
Other sources. Earnings call of 4 Aug 2026 from third party transcript summaries; Financial Analyst Day press release. Peer data from peer 10-K
and 10-Q filings. Sector data: hyperscaler filings, Dell'Oro, Mercury Research and IDC as reported by trade press. Market prices: 30 Sep 2026.
Definitions. FCF = operating cash flow from continuing operations less capex. Core earnings exclude items in Table 2.3. Net cash = cash and short term investments less debt.
Scenario model. EPS = ((Data Center plus other revenue) x core margin plus $0.3bn) x (1 less 13%) over diluted shares. Implied value =
FY2029 EPS x exit P/E, undiscounted.
Disclaimer: for information only, not financial advice. This report is not a recommendation to buy, sell or hold any
security. Figures come from SEC filings retrieved through the SEC-API.io MCP server and from sources named above. Scenario values follow
arithmetically from the stated assumptions. Consult a licensed adviser before investing.