Berkshire Hathaway Inc. (BRK.B), Financial Analysis
Insights derived from analysing SEC filings. Independent analysis of Berkshire Hathaway Inc. Class B common stock, not a publication of the SEC. Figures are read from the FY2025 Form 10-K filed 2 March 2026, the Form 10-Q for the quarter ended 30 June 2026 filed 10 August 2026, and the current reports, proxy statement and Section 16 forms listed in Sources. Market prices are last trades on 2 September 2026. Amounts are United States dollars, in millions unless marked otherwise.
The argument
Revenue stagnated and reported earnings fell. FY2025 revenue of $371,444m was $11m above FY2024, while earnings before income taxes fell $27,917m to $82,459m, and the fall is marks: investment and derivative gains dropped to $39,078m from $52,799m and equity method results turned to $(9,590)m from $1,841m. Operating earnings after tax fell 6.2% to $44,486m, the only decline of the five years. Core return on average equity of 6.3% is the lowest of the nine property and casualty filers compared in chapter 4, and the cause is revenue mix: McLane and Pilot Travel Centers supply 25.3% of segment revenue and 1.7% of segment pretax earnings. Capital policy changed with the chief executive: Berkshire repurchased nothing in 2025, restarted on 4 March 2026, had bought $4,762m of stock by 30 June 2026, Greg Abel bought 21 Class A shares on the open market the day the restart was disclosed, and 46.4% of the key person risk factor was rewritten to name him as the holder of capital allocation authority. BRK.B at $506.90 trades at 1.46 times the 30 June 2026 book value, with $326.33 a share of investments behind it, so the three year outcome turns on the multiple applied to the $180.57 a share of operating businesses.
1 Revenue & Business Model
Berkshire sells insurance and uses the policyholder money it holds to own an industrial and consumer conglomerate. FY2025 revenue was $371,444m, $11m above FY2024 and 7.7% a year above FY2021. Almost all of the four year growth came from two places. Insurance group revenue rose $29,090m to $104,212m, and Pilot Travel Centers added $42,198m after Berkshire took control in 2023. Strip both out and the other five segments compounded at 2.5% a year. BRK.B is a float funded owner of operating businesses whose reported earnings are set by marks on a concentrated equity portfolio.
How Berkshire makes money
Three engines produce revenue. Insurance underwriting earns premiums and generates float, which Item 1 of the FY2025 10-K puts at about $176bn at the end of 2025 against about $138bn at the end of 2020; the investment income that float earns sits inside insurance group revenue. Regulated capital intensive assets, BNSF and Berkshire Hathaway Energy, contributed $49,830m, or 13.4% of revenue. Everything else is sales, service and leasing at manufacturing, distribution and retailing subsidiaries run on a decentralised basis, employing 387,800 people at year end, about 80% of them in the United States. Combined statutory surplus of the United States insurers was about $333bn. Item 1 states that the investment portfolios hold a much greater proportion of equity securities than is customary in the insurance industry.
Table 1. Revenue by income statement caption, FY2025 (USD millions)
| Revenue caption | FY2025 | Share of total |
|---|---|---|
| Insurance premiums earned | 88,902 | 23.9% |
| Sales and service revenues | 199,524 | 53.7% |
| Leasing revenues | 10,034 | 2.7% |
| Interest, dividend and other | 23,261 | 6.3% |
| Railroad freight | 23,330 | 6.3% |
| Utility and energy operating | 21,856 | 5.9% |
| Service revenues and other | 4,537 | 1.2% |
| Total revenues | 371,444 | 100.0% |
Sales and service revenues are the largest caption at 53.7% of revenue, and margin does not follow revenue. McLane turned $50,998m into $676m of pretax earnings, a margin of 1.33%, while the insurance group turned $104,212m into $24,721m, a margin of 23.7%. Revenue share and profit share are different questions at Berkshire, and chapter 4 measures what that costs the return on equity.
Revenue by segment

Table 2. Revenue by reportable segment, FY2021 to FY2025 (USD millions)
| Segment | FY2021 | FY2022 | FY2023 | FY2024 | FY2025 | Share FY2025 | CAGR |
|---|---|---|---|---|---|---|---|
| Insurance group | 75,122 | 82,310 | 95,022 | 105,069 | 104,212 | 28.1% | 8.5% |
| Manufacturing | 68,730 | 75,781 | 75,405 | 77,231 | 78,487 | 21.1% | 3.4% |
| McLane | 49,450 | 53,209 | 52,607 | 51,907 | 50,998 | 13.7% | 0.8% |
| Service and retailing | 34,832 | 38,303 | 39,996 | 39,874 | 42,647 | 11.5% | 5.2% |
| Pilot Travel Centers | n/a | n/a | 51,739 | 46,891 | 42,198 | 11.4% | (9.7%) from FY2023 |
| BHE | 25,096 | 26,393 | 26,008 | 26,348 | 26,297 | 7.1% | 1.2% |
| BNSF | 23,282 | 25,888 | 23,876 | 23,572 | 23,533 | 6.3% | 0.3% |
| Segment total | 276,512 | 301,884 | 364,653 | 370,892 | 368,372 | 99.2% | 7.4% |
| Corporate, other and eliminations | (327) | 136 | (171) | 541 | 3,072 | 0.8% | n/a |
| Total revenues | 276,185 | 302,020 | 364,482 | 371,433 | 371,444 | 100.0% | 7.7% |
Insurance is the only segment that materially changed weight, from 27.2% of revenue in FY2021 to 28.1% in FY2025. Premiums earned rose 28.0% over four years as GEICO repriced and the primary group grew, and investment income on float rose 170.4% as short rates lifted the yield on the group's short term investments. FY2025 broke the pattern: investment income fell to $15,310m from $16,812m and insurance group revenue fell for the first time in the period, by $857m.
Table 3. Insurance group revenue by underwriting unit, FY2021 to FY2025 (USD millions)
| Insurance revenue line | FY2021 | FY2022 | FY2023 | FY2024 | FY2025 |
|---|---|---|---|---|---|
| GEICO | 37,706 | 38,984 | 39,264 | 42,252 | 44,481 |
| Berkshire Hathaway Primary | 11,575 | 13,746 | 17,129 | 18,733 | 18,713 |
| Reinsurance group | 20,179 | 21,846 | 27,010 | 27,272 | 25,708 |
| Premiums earned, net | 69,460 | 74,576 | 83,403 | 88,257 | 88,902 |
| Investment income on float | 5,662 | 7,734 | 11,619 | 16,812 | 15,310 |
| Insurance group revenue | 75,122 | 82,310 | 95,022 | 105,069 | 104,212 |
Pilot moves the other way. Segment revenue fell 18.4% from FY2023 to FY2025, and FY2023 covered only the eleven months from 1 February, so the underlying decline is larger. Volume fell too: Item 1 of the FY2023 10-K reported over 16 billion gallons of fuel sold in 2023 and Item 1 of the FY2025 10-K about 10.9 billion in 2025, on disclosures that are not drawn on the same basis. BNSF and Berkshire Hathaway Energy are flat: freight revenue moved $251m across four years and utility revenue $1,201m. Manufacturing compounded at 3.4% a year, with industrial and commercial products at 7.9% while building products fell from $22,762m in FY2022 to $19,609m. Service and retailing is the quiet grower at 5.2% a year and added $2,773m in FY2025, the largest increase of any segment. Only it and manufacturing grew revenue in FY2025.
Revenue by region

Berkshire files one geographic disaggregation and no other: insurance premiums written, net, by geographic area. It publishes no geographic split of consolidated revenue, and Item 1 sends the reader to the segment note for everything else. The disclosure covers 23.9% of FY2025 revenue on a premiums earned basis, so it measures the international exposure of the insurance group.
Table 4. Insurance premiums written, net, by geographic area, FY2021 to FY2025 (USD millions)
| Geographic area | FY2021 | FY2022 | FY2023 | FY2024 | FY2025 | Share FY2021 | Share FY2025 | CAGR |
|---|---|---|---|---|---|---|---|---|
| United States | 57,594 | 61,755 | 69,116 | 73,081 | 73,885 | 80.5% | 82.7% | 6.4% |
| Western Europe | 5,911 | 6,136 | 6,337 | 6,659 | 6,599 | 8.3% | 7.4% | 2.8% |
| Asia Pacific | 5,852 | 6,403 | 7,066 | 6,591 | 6,061 | 8.2% | 6.8% | 0.9% |
| All other | 2,194 | 2,161 | 2,913 | 2,362 | 2,831 | 3.1% | 3.2% | 6.6% |
| Premiums written, net | 71,551 | 76,455 | 85,432 | 88,693 | 89,376 | 100.0% | 100.0% | 5.7% |
| Memo: premiums earned, net | 69,460 | 74,576 | 83,403 | 88,257 | 88,902 | n/a | n/a | n/a |
| Memo: share of consolidated revenue | 25.1% | 24.7% | 22.9% | 23.8% | 23.9% | n/a | n/a | n/a |
The insurance book is getting more domestic. Premiums written outside the United States fell from 19.5% of the total in FY2021 to 17.3% in FY2025, because United States premiums compounded at 6.4% a year while Asia Pacific grew 0.9% and Western Europe 2.8%. Item 1 states that nearly 90% of Berkshire Hathaway Primary net premiums written in 2025 were in the United States. The rest of the group is domestic by construction: BNSF is a North American railroad, the utilities serve 5.4 million retail customers in western and midwestern states, McLane distributes in all 50 states, and Pilot operates travel centres across the United States and five Canadian provinces. The visible international assets are General Reinsurance AG in Cologne, Berkshire Hathaway Specialty branches in Asia and Europe, IMC with plants in eleven countries, Detlev Louis in Germany, and electricity distribution in Great Britain and Canada.
Revenue by product

Table 5. Revenue from contracts with customers by source, FY2021 to FY2025 (USD millions)
| Source of revenue | FY2021 | FY2022 | FY2023 | FY2024 | FY2025 |
|---|---|---|---|---|---|
| Other retail and wholesale | 18,895 | 20,126 | 70,775 | 64,858 | 60,598 |
| Service | 35,063 | 37,416 | 36,053 | 35,941 | 36,879 |
| Grocery and convenience | 31,245 | 32,599 | 31,524 | 31,841 | 30,697 |
| Industrial and commercial | 22,343 | 24,765 | 28,299 | 29,117 | 30,336 |
| Electricity and natural gas | 18,264 | 20,317 | 20,647 | 20,991 | 21,338 |
| Building products | 19,604 | 22,762 | 20,119 | 19,892 | 19,609 |
| Food and beverage | 17,332 | 19,388 | 19,040 | 18,068 | 18,585 |
| Consumer products | 18,540 | 19,912 | 17,702 | 18,204 | 17,919 |
| Auto sales | 9,966 | 10,486 | 10,747 | 10,802 | 11,283 |
| Revenue from contracts with customers | 191,252 | 207,771 | 254,906 | 249,714 | 247,244 |
| Revenue outside the contracts standard | 84,933 | 94,249 | 109,576 | 121,719 | 124,200 |
Revenue from contracts with customers was $247,244m in FY2025, 66.6% of revenue. The balance of $124,200m is insurance premiums, leasing and investment income, which fall outside the contracts standard. Fuel and distribution dominate the contract revenue mix: other retail and wholesale distribution, grocery and convenience distribution and food and beverage distribution together were $109,880m, carried mostly by the two thinnest margin segments in the group. The FY2025 10-K reclassifies FY2023 by moving Pilot fuel out of electricity, natural gas and fuel into other retail and wholesale distribution. FY2021 and FY2022 predate Pilot, so the five year series is on one basis.
What the revenue line does not carry
Revenue excludes investment and derivative gains and losses, which is where the earnings volatility lives. FY2025 earnings before income taxes of $82,459m contained $39,078m of investment and derivative gains against $51,714m from the operating segments and $1,257m from corporate items. Equity method results turned to $(9,590)m, of which $(4,393)m came from Kraft Heinz and $(5,302)m from Occidental Petroleum. Revenue moved $11m year on year while pretax earnings fell $27,917m. Headline earnings therefore track the portfolio; chapter 2 separates the portfolio from the businesses.
One structural change lands after the balance sheet date. Berkshire completed the purchase of Occidental Petroleum's chemicals business, OxyChem, on 2 January 2026 under an agreement dated 1 October 2025. OxyChem runs 21 United States plants and two international sites, is a top three North American producer of PVC, chlor alkali products and chlorinated organic chemicals, and reports inside manufacturing. No OxyChem revenue is in any figure in this chapter.
2 Financial Analysis & Ratios
Berkshire's reported earnings move with the stock market. Strip the equity marks out and the operating engine earned $44,486m after tax in FY2025, down 6.2% on FY2024 and the only decline of the five years shown. GAAP net earnings fell 24.8% to $66,968m because after tax investment gains fell from $58,873m in FY2023 to $30,737m and an $8,255m after tax impairment of the Kraft Heinz and Occidental equity method holdings landed in the same year. The balance sheet did the work instead: cash and Treasury bills reached $373,311m, 30.5% of total assets, against equity securities of $297,778m, and Berkshire repurchased no common stock at all. The first six months of 2026 reverse the earnings direction, with operating earnings up 17.0% and net earnings up 110.8%.
FY2021 and FY2022 are carried at the values restated for ASU 2018-12, adopted 1 January 2023 and applied retrospectively to 1 January 2021 in the FY2023 10-K.
Table 6. What changed, FY2025 against FY2024 (USD millions)
| FY2024 | FY2025 | Change | Change % | |
|---|---|---|---|---|
| Revenues | 371,433 | 371,444 | 11 | 0.00% |
| Operating pretax earnings | 55,736 | 52,971 | (2,765) | (5.0%) |
| Operating earnings, after tax | 47,437 | 44,486 | (2,951) | (6.2%) |
| Net earnings to Berkshire | 88,995 | 66,968 | (22,027) | (24.8%) |
| Operating cash flow | 30,592 | 45,969 | 15,377 | 50.3% |
| Free cash flow | 11,616 | 25,042 | 13,426 | 115.6% |
| Insurance underwriting, after tax | 9,020 | 7,258 | (1,762) | (19.5%) |
| Insurance investment income, after tax | 13,670 | 12,513 | (1,157) | (8.5%) |
| BNSF, after tax | 5,031 | 5,476 | 445 | 8.8% |
| Berkshire Hathaway Energy, after tax | 3,730 | 3,979 | 249 | 6.7% |
| Manufacturing, service and retailing, after tax | 13,072 | 13,647 | 575 | 4.4% |
| Other, after tax | 2,914 | 1,613 | (1,301) | (44.6%) |
| Investment gains, after tax | 41,558 | 30,737 | (10,821) | (26.0%) |
| Impairment of equity method holdings, after tax | n/a | (8,255) | (8,255) | n/a |
Insurance did the damage. Underwriting earnings fell $1,762m as each of GEICO, Berkshire Hathaway Primary and Berkshire Hathaway Reinsurance Group earned less, against after tax losses from significant catastrophe events of about $850m that include the Southern California wildfires. Insurance investment income fell $1,157m on lower interest rates and on large capital distributions from the insurance subsidiaries to the parent at the end of 2024, which moved that interest income into the other line rather than out of the group. The four operating businesses outside insurance all grew: BNSF 8.8% on lower operating expenses, Berkshire Hathaway Energy 6.7% on lower PacifiCorp wildfire accruals, manufacturing, service and retailing 4.4%. The $1,301m fall in other turns on a $1,792m after tax currency swing, from gains of $1,150m in FY2024 to losses of $642m in FY2025, partly offset by higher investment income.
Operating cash flow rose $15,377m on a fall in cash taxes paid, from $28,544m in FY2024 to $13,978m in FY2025. The FY2024 figure carried the tax on $143,400m of equity security disposals, which is why free cash flow was only $11,616m that year.

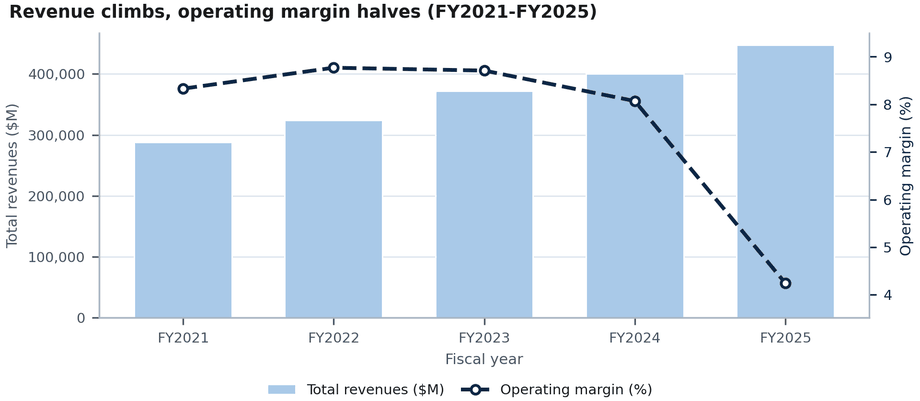
Revenue growth has stopped. The 20.7% jump in FY2023 is the consolidation of Pilot Travel Centers from 31 January 2023, which added $51,664m of FY2023 revenues. Since then revenue grew 1.9% in FY2024 and was flat in FY2025, up $11m on a $371bn base. Margin carried the earnings instead: operating pretax margin moved from an 11.7% to 11.9% band in FY2021 to FY2023 up to 15.0% in FY2024, then eased to 14.3%.
Table 7. Consolidated earnings and cash flow, FY2021 to FY2025 (USD millions)
| FY2021 | FY2022 | FY2023 | FY2024 | FY2025 | |
|---|---|---|---|---|---|
| Revenues | 276,185 | 302,020 | 364,482 | 371,433 | 371,444 |
| Costs and expenses | (243,752) | (266,484) | (321,144) | (315,697) | (318,473) |
| Operating pretax earnings | 32,433 | 35,536 | 43,338 | 55,736 | 52,971 |
| Investment gains (losses) | 78,542 | (67,899) | 74,855 | 52,799 | 39,078 |
| Equity method earnings (losses) | 886 | 1,863 | 1,973 | 1,841 | (9,590) |
| Earnings (loss) before income taxes | 111,861 | (30,500) | 120,166 | 110,376 | 82,459 |
| Income tax (expense) benefit | (20,912) | 8,502 | (23,019) | (20,815) | (15,199) |
| Noncontrolling interests | (1,012) | (761) | (924) | (566) | (292) |
| Net earnings (loss) to Berkshire | 89,937 | (22,759) | 96,223 | 88,995 | 66,968 |
| Operating cash flow | 39,427 | 37,350 | 49,196 | 30,592 | 45,969 |
| Capital expenditure | (13,276) | (15,464) | (19,409) | (18,976) | (20,927) |
| Free cash flow | 26,151 | 21,886 | 29,787 | 11,616 | 25,042 |
| Common stock repurchased | (27,061) | (7,854) | (9,171) | (2,918) | 0 |
| Income taxes paid, net | n/a | n/a | (7,765) | (28,544) | (13,978) |

The two series have almost nothing in common. Operating earnings compounded at 12.7% a year across the four years to FY2025. GAAP net earnings swung from $89,937m to a $22,759m loss and back to $96,223m over FY2021 to FY2023 on the mark to market of the equity portfolio alone. Berkshire states in the FY2025 10-K that investment gains and losses "are generally meaningless in understanding our reported periodic results or evaluating our periodic economic performance".
Table 8. GAAP to operating earnings, after tax and attributable to Berkshire (USD millions)
| FY2021 | FY2022 | FY2023 | FY2024 | FY2025 | |
|---|---|---|---|---|---|
| Insurance underwriting | 870 | (30) | 5,428 | 9,020 | 7,258 |
| Insurance investment income | 4,807 | 6,484 | 9,567 | 13,670 | 12,513 |
| BNSF | 5,990 | 5,946 | 5,087 | 5,031 | 5,476 |
| Berkshire Hathaway Energy | 3,572 | 3,904 | 2,331 | 3,730 | 3,979 |
| Manufacturing, service and retailing | 11,120 | 12,512 | 13,362 | 13,072 | 13,647 |
| Other | 1,238 | 2,037 | 1,575 | 2,914 | 1,613 |
| Operating earnings, after tax | 27,597 | 30,853 | 37,350 | 47,437 | 44,486 |
| Investment gains (losses), after tax | 62,340 | (53,612) | 58,873 | 41,558 | 30,737 |
| Impairment of equity method holdings | n/a | n/a | n/a | n/a | (8,255) |
| Net earnings (loss) to Berkshire | 89,937 | (22,759) | 96,223 | 88,995 | 66,968 |
| Operating earnings as share of net earnings | 30.7% | n/a | 38.8% | 53.3% | 66.4% |
FY2021 and FY2022 are recast onto the FY2025 layout, which folds Pilot Travel Centers into manufacturing, service and retailing and folds noncontrolled businesses into other; the underlying lines are unchanged. The impairment line appears only in FY2025, so earlier years read n/a rather than zero, and the final ratio is not meaningful in FY2022, when net earnings were negative. The share of net earnings that comes from operations rose from 30.7% in FY2021 to 66.4% in FY2025 as the equity marks shrank.

Operating return on average equity sits in a 5.9% to 7.8% band and fell to 6.5% in FY2025. That is the number a shareholder buying the operating businesses earns, and it is low because equity of $717,419m carries unrealised gains on securities that generate no operating earnings. GAAP return on average equity of 9.8% in FY2025 is the same denominator with a numerator that moves with the market. Chapter 4 ranks that return against eight competitors on one definition.
Table 9. Ratio analysis, FY2021 to FY2025
| FY2021 | FY2022 | FY2023 | FY2024 | FY2025 | |
|---|---|---|---|---|---|
| Revenue growth | n/a | 9.4% | 20.7% | 1.9% | 0.00% |
| Operating earnings growth | n/a | 11.8% | 21.1% | 27.0% | (6.2%) |
| Book value per share growth | n/a | (4.5%) | 20.1% | 16.0% | 10.5% |
| Operating pretax margin | 11.7% | 11.8% | 11.9% | 15.0% | 14.3% |
| Operating earnings margin | 10.0% | 10.2% | 10.2% | 12.8% | 12.0% |
| GAAP net margin | 32.6% | (7.5%) | 26.4% | 24.0% | 18.0% |
| Effective tax rate | 18.7% | 27.9% | 19.2% | 18.9% | 18.4% |
| Return on average equity, GAAP | 19.2% | (4.7%) | 18.6% | 14.7% | 9.8% |
| Return on average equity, operating earnings | 5.9% | 6.3% | 7.2% | 7.8% | 6.5% |
| Return on average assets, GAAP | n/a | (2.4%) | 9.5% | 8.0% | 5.6% |
| Borrowings to equity | 22.8% | 25.9% | 22.9% | 19.2% | 18.0% |
| Assets to equity | 1.91x | 2.00x | 1.91x | 1.78x | 1.70x |
| Operating pretax interest cover | 7.77x | 8.17x | 8.66x | 10.72x | 10.45x |
| Cash and Treasury bills to assets | 15.3% | 13.6% | 15.7% | 29.0% | 30.5% |
| Cash and Treasury bills to borrowings | 1.28x | 1.05x | 1.31x | 2.68x | 2.89x |
| Asset turnover | n/a | 0.32x | 0.36x | 0.33x | 0.31x |
| Operating cash flow to operating earnings | 142.9% | 121.1% | 131.7% | 64.5% | 103.3% |
| Pretax underwriting margin | 1.6% | (0.03%) | 8.3% | 12.9% | 10.6% |
| Implied combined ratio | 98.4% | 100.0% | 91.7% | 87.1% | 89.4% |
| Pretax underwriting return on float | 0.8% | (0.01%) | 4.1% | 6.7% | 5.4% |
| Insurance float, $bn | 147 | 164 | 169 | 171 | 176 |
| Book value per Class B equivalent share, $ | 226.32 | 216.21 | 259.58 | 301.00 | 332.55 |
| Basic earnings per Class B equivalent share, $ | 39.70 | (10.33) | 44.27 | 41.27 | 31.04 |
| Operating earnings per Class B equivalent share, $ | 12.18 | 14.00 | 17.19 | 22.00 | 20.62 |
Leverage fell every year from FY2022: borrowings to equity 25.9% to 18.0%, assets to equity 2.00x to 1.70x, operating pretax interest cover 8.17x to 10.45x. Liquidity rose on the same scale, with cash and Treasury bills covering borrowings 2.89 times against 1.05 times in FY2022. Asset turnover of 0.31x in FY2025 is the lowest of the five years, a direct consequence of holding $373,311m in Treasury bills that produce interest income rather than revenue.

The reweighting is the largest single change on the balance sheet. Cash and Treasury bills grew from $146,719m at the end of FY2021 to $373,311m at the end of FY2025, a $226,592m build, while equity securities fell from $350,719m to $297,778m. Borrowings are almost static at $114,262m to $129,081m across the five years, so the build is funded from retained operating earnings and from $143,400m of equity disposals in FY2024.

Float grew every year, from $147bn to $176bn, and cost less than nothing in four of the five years: pretax underwriting was positive in every year but FY2022 and the implied combined ratio has been below 100 since FY2023. The FY2025 margin of 10.6% sits below the 12.9% of FY2024 and well above the 1.6% and (0.03%) of FY2021 and FY2022. Underwriting is the swing factor in operating earnings: after tax it moved $9,050m between FY2022 and FY2024, against $7,534m for the other five lines added together.
Table 10. First six months 2026 against first six months 2025 (USD millions)
| H1 2025 | H1 2026 | Change | Change % | |
|---|---|---|---|---|
| Revenues | 182,240 | 195,483 | 13,243 | 7.3% |
| Costs and expenses | 157,652 | 165,997 | 8,345 | 5.3% |
| Operating pretax earnings | 24,588 | 29,486 | 4,898 | 19.9% |
| Operating earnings, after tax | 20,801 | 24,329 | 3,528 | 17.0% |
| Investment gains (losses), after tax | (68) | 11,444 | 11,512 | n/a |
| Impairment of Kraft Heinz holding | (3,760) | 0 | 3,760 | n/a |
| Earnings before income taxes | 19,898 | 44,382 | 24,484 | 123.0% |
| Net earnings to Berkshire | 16,973 | 35,773 | 18,800 | 110.8% |
| Operating cash flow | 20,988 | 21,653 | 665 | 3.2% |
| Capital expenditure | 9,139 | 10,631 | 1,492 | 16.3% |
| Free cash flow | 11,849 | 11,022 | (827) | (7.0%) |
| Operating pretax margin | 13.5% | 15.1% | 1.6% | n/a |
| Effective tax rate | 13.9% | 19.0% | 5.1% | n/a |
Revenue growth returned at 7.3% and operating pretax margin widened 1.6 points to 15.1%. Underwriting is close to flat at $3,448m against $3,328m, with GEICO pretax underwriting earnings down to $2,410m from $3,994m as the GEICO loss and loss adjustment expense ratio rose to 75.3% from 70.4%, offset by Reinsurance Group earnings of $1,286m against $343m. Insurance investment income fell again, 8.3%. Manufacturing, service and retailing grew 15.1%. The other line rose $2,461m, almost all of it a $2,165m currency swing on the senior notes of Berkshire and Berkshire Hathaway Finance Corporation denominated outside the dollar, from a $1,590m loss to a $575m gain.

Free cash flow fell 7.0% to $11,022m as capital expenditure rose 16.3% to $10,631m against operating cash flow up 3.2%. At 30 June 2026 cash and Treasury bills were $365,514m, equity securities $323,779m, borrowings $128,599m and shareholders' equity $747,910m.
Table 11. Quarterly revenue reconciled to the audited full year (USD millions)
| Year | Q1 | Q2 | Q3 | Q4 implied | Sum of four quarters | Full year as first filed | Current comparative | Difference |
|---|---|---|---|---|---|---|---|---|
| FY2021 | 64,599 | 69,114 | 70,583 | 71,798 | 276,094 | 276,094 | 276,185 | (91) |
| FY2022 | 70,810 | 76,180 | 76,934 | 78,165 | 302,089 | 302,089 | 302,020 | 69 |
| FY2023 | 85,393 | 92,503 | 93,210 | 93,376 | 364,482 | 364,482 | 364,482 | 0 |
| FY2024 | 89,869 | 93,653 | 92,995 | 94,916 | 371,433 | 371,433 | 371,433 | 0 |
| FY2025 | 89,725 | 92,515 | 94,972 | 94,232 | 371,444 | 371,444 | 371,444 | 0 |
The FY2021 and FY2022 differences in Table 11 are restatements rather than errors. Service revenues and other income in railroad, utilities and energy were restated from $6,052m to $6,161m between the FY2021 10-K and the FY2022 10-K, a $109m reclassification with no earnings effect, and premiums earned were restated from $69,478m to $69,460m on adoption of ASU 2018-12, a further $18m; together they account for the $91m. The $69m in FY2022 is premiums earned restated from $74,645m to $74,576m on the same adoption, applied retrospectively to 1 January 2021.
3 MD&A & Management Commentary
Berkshire gives no guidance, holds no earnings call and publishes no analyst deck. Management commentary reaches the market through three documents only: Item 7 of the Form 10-K, Part I Item 2 of the Form 10-Q, and the one page Exhibit 99.1 attached to each earnings Form 8-K. The Q2 2026 release says so itself: "The limited information that follows in this press release is not adequate for making an informed investment judgment." The MD&A is therefore the commentary, and in the year to 30 June 2026 it says four things: underwriting margin is being given back, rate driven investment income is shrinking, the industrial and rail businesses are carrying the operating result, and capital policy changed with the chief executive.
Operating earnings, the measure management builds the MD&A around, rose 17.0% in the first six months of 2026 to $24,329m from $20,801m. GAAP net earnings more than doubled to $35,773m from $16,973m. The two numbers move for different reasons and only one of them is management's own subject.
3.1 The trends management names
The label in the first column below is this analysis's. The second column is management's own wording, quoted where quotation marks appear.
Table 12. Trends management names, with source and date
| Trend | What management says | Source | Date |
|---|---|---|---|
| Underwriting margin will not hold | Results over the past three years were "exceptional compared to results over longer periods". Earnings "may decline in the future from the ongoing impacts of competition within the industry and rising claim cost trends". | Form 10-K FY2025, Item 7 | 2026-03-02 |
| Auto claim costs are rising | Private passenger auto bodily injury severity rose 10% to 12% in the first six months of 2026, with frequency up 5% to 7%. | Form 10-Q Q2 2026 | 2026-08-10 |
| Acquisition spend at GEICO is climbing | Expense ratio 14.0% in the first six months of 2026, up 2.7 points, "primarily driven by increases in commissions and advertising expenses". | Form 10-Q Q2 2026 | 2026-08-10 |
| Reinsurance pricing is softening | Premiums written at the reinsurance group fell $1.7bn in 2025 "attributable to increased competition and lower rates". | Form 10-K FY2025, Item 7 | 2026-03-02 |
| Underwriting discipline over volume | Underwriting managers are instructed "to decline writing insurance business when the premiums are deemed inadequate to the risks underwritten, without regard to the impact on premium volume". | Form 10-Q Q2 2026 | 2026-08-10 |
| Lower rates are eroding investment income | Insurance investment income fell 8.5% in 2025 and 8.3% in the first six months of 2026, "attributable to lower interest income, reflecting lower interest rates". | Form 10-K FY2025 and Form 10-Q Q2 2026 | 2026-08-10 |
| Liquidity comes before yield | Maintaining ample liquidity is "paramount" and Berkshire insists on "safety over yield" in short term investments. | Form 10-K FY2025, Item 7 | 2026-03-02 |
| Tariffs and trade policy are unquantified | "We are currently unable to reliably predict the ultimate impact on our businesses, whether through changes in the availability of products, supply chain costs and efficiency, and customer demand for our products and services." | Form 10-Q Q2 2026 | 2026-08-10 |
| Raw material cost and availability | "We are experiencing increased costs and reduced availability of certain raw materials, which could negatively impact our earnings in 2026." | Form 10-K FY2025, Item 7 | 2026-03-02 |
| A named second half headwind | "IMC's earnings over the second half of 2026 are expected to be negatively impacted by the rise in raw materials costs." | Form 10-Q Q2 2026 | 2026-08-10 |
| Electronics distribution margin risk | "Inventory cost and supply chain uncertainties could negatively impact TTI's gross margins in the future." | Form 10-Q Q2 2026 | 2026-08-10 |
| Aerospace growth depends on capacity | "Future sales and earnings growth will depend on successfully increasing production and expanding capacity, as necessary, to meet customer demand." | Form 10-Q Q2 2026 | 2026-08-10 |
| Housing remains blocked | The real estate brokerage business "continues to be negatively impacted by the limited availability of homes for sale and high home prices". | Form 10-K FY2025, Item 7 | 2026-03-02 |
| Consumers are cautious | Several retailing businesses saw "sluggish customer demand", from "increased competition and the impacts of higher economic uncertainty and changes in consumer confidence". | Form 10-K FY2025, Item 7 | 2026-03-02 |
| Clean energy credits phase out early | The One Big Beautiful Bill Act accelerates the phase out of clean electricity credits. Berkshire Hathaway Energy "currently does not believe these items will significantly impact its business in the near term". | Form 10-K FY2025, Item 7 | 2026-03-02 |
| Goodwill headroom is thin at four units | Four reporting units did not clear carrying value by 20% at the 2025 review. Aggregate fair value $27.7bn against carrying value $26.2bn, with goodwill of $9.2bn. | Form 10-Q Q2 2026 | 2026-08-10 |
| Investment marks carry no signal | "We continue to believe the investment gains and losses recorded in earnings in any given period has little analytical or predictive value." | Form 10-K FY2025, Item 7 | 2026-03-02 |
| Buybacks restarted with the succession | "In the interest of transparency with our leadership transition, we are disclosing that we commenced repurchasing shares of our common stock under this policy on Wednesday, March 4, 2026." | Form 8-K, Item 8.01 | 2026-03-05 |
| The cash floor is unchanged | "We will not repurchase our stock if it reduces our consolidated cash, cash equivalents and U.S. Treasury Bills holdings to below $30 billion." | Form 10-Q Q2 2026 | 2026-08-10 |
| Claim payments stay above $30bn | Consolidated claim liabilities of about $152bn. Forecast 2026 payments on occurrences before 2026 expected to exceed $30bn. | Form 10-K FY2025, Item 7 | 2026-03-02 |
3.2 Operating earnings against the GAAP headline
Management defines operating earnings as net earnings excluding investment gains and losses, impairments of goodwill and intangible assets, and other than temporary impairments of equity method investments. Over the six quarters to 30 June 2026 operating earnings ranged from $9,641m to $12,983m, a spread of 1.35 times, while GAAP net earnings ranged from $4,603m to $30,796m, a spread of 6.7 times.

Table 13. GAAP to operating earnings, as management presents it (USD millions, after tax)
| Period | Operating earnings | Investment gains (losses) | Impairment of equity method investments | Net earnings attributable to Berkshire |
|---|---|---|---|---|
| FY2024 | 47,437 | 41,558 | 0 | 88,995 |
| FY2025 | 44,486 | 30,737 | (8,255) | 66,968 |
| Q1 2025 | 9,641 | (5,038) | 0 | 4,603 |
| Q2 2025 | 11,160 | 4,970 | (3,760) | 12,370 |
| Q3 2025 | 13,485 | 17,311 | 0 | 30,796 |
| Q4 2025 | 10,200 | 13,494 | (4,495) | 19,199 |
| Q1 2026 | 11,346 | (1,240) | 0 | 10,106 |
| Q2 2026 | 12,983 | 12,684 | 0 | 25,667 |
| First six months 2025 | 20,801 | (68) | (3,760) | 16,973 |
| First six months 2026 | 24,329 | 11,444 | 0 | 35,773 |
The 2025 impairments are permanent. Berkshire wrote down Kraft Heinz and Occidental by $8,255m after tax, $3,760m in the second quarter and $4,495m in the fourth. These are equity method holdings, so the charge is a revaluation that does not reverse with the tape. Management excludes it from operating earnings and describes it in one sentence of the MD&A.
3.3 What is carrying the operating result

Five of the six operating lines grew in the first six months of 2026. Manufacturing, service and retailing added $1,008m, the largest contribution, on industrial products revenue up 25.5% helped by the OxyChem acquisition. BNSF added $255m on revenue up 9.8%. Insurance investment income fell $522m, the only decline, and management attributes all of it to lower short term rates.

The two ratios management reports against move in opposite directions. GEICO's combined ratio widened from 81.5% in 2024 to 84.7% in 2025 and 89.3% in the first six months of 2026. BNSF's operating ratio narrowed from 68.0% to 65.5% and held there. In cash terms GEICO's pretax underwriting earnings fell 39.7% to $2,410m in the first six months of 2026 and 45.4% to $994m in the second quarter alone. The $994m is premiums earned of $11,291m less losses and loss adjustment expenses of $8,644m less underwriting expenses of $1,653m, all three as printed in the Form 10-Q, and it agrees with the 91.2% total ratio the filing prints beside them.
Table 14. GEICO private passenger auto, as management states the drivers
| Period | Coverage | Frequency | Severity |
|---|---|---|---|
| FY2025 | Bodily injury | up 4% to 6% | up 12% to 14% |
| FY2025 | Property damage and collision | down 1% to 3% | up 2% to 4% |
| First six months 2026 | Bodily injury | up 5% to 7% | up 10% to 12% |
| First six months 2026 | Property damage and collision | up 3% to 5% | up 0% to 3% |
Both sides of GEICO's ratio moved against it in 2026. Frequency turned positive across every coverage after falling in 2025, severity stayed in double digits on bodily injury, and management put 2.7 points of expense ratio increase down to commissions and advertising. Written premium grew 1.3%. GEICO is buying growth into a rising claim cost, and management said in the 10-K it expected competition and claim cost trends to press on underwriting earnings.
3.4 Float, rates and the cost of carry

Float reached about $177.5bn at 30 June 2026, up about $1.1bn since year end 2025. Management repeats each period that the average cost of float was negative, which it was in each of the three years to 31 December 2025 and in both halves compared. The income earned on that float is the part under pressure: insurance investment income fell to 23.6% of operating earnings in the first six months of 2026 from 30.1% a year earlier. Management gives one reason for the decline and repeats it in every filing: lower interest rates.
3.5 Capital, in management's own disclosure
Table 15. Capital and liquidity, as disclosed (USD billions unless stated)
| Item | 31 Dec 2025 or FY2025 | 30 Jun 2026 or first six months 2026 | Source |
|---|---|---|---|
| Shareholders' equity | 717.4 | 747.9 | Form 10-K FY2025, Form 10-Q Q2 2026 |
| Cash, cash equivalents and Treasury Bills, insurance and other | 369.0 | 359.2 | Form 10-K FY2025, Form 10-Q Q2 2026 |
| Equity and fixed maturity securities, excluding equity method | 315.6 | 340.8 | Form 10-K FY2025, Form 10-Q Q2 2026 |
| Insurance float | 176.0 | 177.5 | Form 10-K FY2025, Form 10-Q Q2 2026 |
| Consolidated claim liabilities | 152.0 | 152.9 | Form 10-K FY2025, Form 10-Q Q2 2026 |
| Net cash from operating activities | 46.0 | 21.7 | Form 10-K FY2025, Form 10-Q Q2 2026 |
| Capital expenditure | 20.9 | 10.6 | Form 10-K FY2025, Form 10-Q Q2 2026 |
| Of which BNSF and Berkshire Hathaway Energy | 14.4 | 6.7 | Form 10-K FY2025, Form 10-Q Q2 2026 |
| Treasury stock acquired | 0.0 | 4.8 | Form 10-K FY2025, Form 10-Q Q2 2026 |
| Acquisitions completed or agreed | 9.4 for OxyChem, 2 Jan 2026 | 6.8 for Taylor Morrison, 24 Jul 2026 | Form 10-Q Q2 2026 |
| Forecast BNSF and Berkshire Hathaway Energy capital expenditure | about 15.0 for 2026 | about 8.6 for the remainder of 2026 | Form 10-K FY2025, Form 10-Q Q2 2026 |
Three capital statements changed in nine months, all of them filed rather than spoken. The Item 8.01 report of 4 March 2026 tied the start of repurchases to the leadership transition, and by 30 June 2026 Berkshire had bought $4.8bn of stock, about $4.5bn of it in the second quarter. Cash and Treasury Bills fell $9.8bn over the half while equity and fixed maturity holdings rose $25.2bn. Chapter 5 dates the officer changes that came with the handover, and chapter 9 prices the buybacks against book value.
Nancy Pierce took GEICO in December 2025 and reports a combined ratio 7.6 points wider in her first six months than in the same period a year earlier. The drivers management gives are claim frequency, claim severity, commissions and advertising, none of which the filings tie to the change of leadership.
3.6 Where management's framing and the numbers part company
Insurance underwriting growth is catastrophe absence and reserve releases. Management writes that underwriting earnings "increased 3.6% in the first six months of 2026", a gain of $120m after tax. The same filing discloses that after tax losses from significant catastrophe events were $850m in the first six months of 2025 and nil in 2026, and that reductions in prior accident years' claim estimates were far larger in 2026.
Table 16. Two items inside the first half underwriting result (USD millions, pretax, effect on underwriting earnings)
| Item | First six months 2025 | First six months 2026 | Swing |
|---|---|---|---|
| Significant catastrophe losses, primary group | (300) | 0 | 300 |
| Significant catastrophe losses, reinsurance group | (760) | 0 | 760 |
| Prior year reserve movement, primary group | (401) | 444 | 845 |
| Prior year reserve movement, reinsurance group | 506 | 869 | 363 |
| Combined effect | (955) | 1,313 | 2,268 |
A positive figure adds to underwriting earnings, and catastrophe losses for the primary group are stated as approximately $300m in the first six months of 2025. Roughly $2.3bn pretax of support sits behind an after tax underwriting gain of $120m. Current accident year underwriting, on management's own component disclosure, went backwards, and GEICO's 45.4% second quarter decline is the visible part.
The other line is a currency translation. Other operating earnings rose from $73m to $2,534m in the first six months, the single largest contributor to the operating earnings increase. Management attributes the move "primarily" to currency on yen denominated borrowings: gains of $575m after tax in 2026 against losses of $1.59bn in 2025, a swing of about $2.17bn. Berkshire excludes equity marks from operating earnings on the argument that they carry no predictive value, and leaves an equally reversible currency translation inside the same measure. Against that, the borrowings are real liabilities, the accounting is required, and the disclosure of the amount is clear enough that any reader can strip it out.
The purchase price of OxyChem moved. The FY2025 Form 10-K states Berkshire acquired the business "for approximately $9.5 billion". The Q2 2026 Form 10-Q states "approximately $9.4 billion". The difference is $0.1bn on a completed transaction and is consistent with a closing adjustment settled after the 10-K was filed. It is not adjusted here.
3.7 The absence of an earnings call
Berkshire does not hold a quarterly earnings conference call. No transcript exists for any quarter in the review period, and the earnings release directs readers to the 10-Q instead. The only live management question and answer session is the annual meeting, held in Omaha on 2 May 2026, which Berkshire discloses on Form 8-K only for the vote results and the first quarter release attached to it. At that meeting, asked whether there is a point at which Berkshire should stop being a conglomerate, Greg Abel answered "Absolutely not", and said of the cash balance that if there is a "strong value proposition" Berkshire "will be prepared to act decisively and with significant capital. That's what it's there for." The filings show the follow through: $9.4bn for OxyChem, $6.8bn for Taylor Morrison, $4.8bn of buybacks and a $25.2bn rise in securities holdings, against a $9.8bn fall in cash and Treasury Bills.
Berkshire offers no forward numbers to model against. Every forward statement in Table 12 gives a direction only, with three exceptions that carry a figure: capital expenditure of about $15bn at BNSF and Berkshire Hathaway Energy in 2026, claim payments above $30bn in 2026, and interest on debt of $4.9bn in 2026 falling to $4.3bn in 2030.
4 Sector & Competitor Analysis
Berkshire is the largest filer in its SIC code by a factor of four and the least profitable of the nine on a like for like measure. Core revenue of $371.4bn in FY2025 is 4.3 times Progressive's $86.9bn, yet the core pretax margin of 14.3% sits below the peer median of 16.6% and the core return on average equity of 6.3% is the lowest in the set. The stock trades at 1.52 times closing book value against 1.32 times implied by the cross sectional fit of price to book on return on equity across the nine. Cash and Treasury bills of $373.3bn plus listed equities of $297.8bn together equal 61% of market capitalisation.
The sector backdrop cuts the other way. United States property and casualty carriers recorded a 92.9% combined ratio in 2025 against 96.6% in 2024, and property catastrophe rates fell 12% globally at the 1 January 2026 renewals. Berkshire's underwriting earnings moved against that improvement, falling to $9.46bn pretax from $11.41bn, with GEICO down to $6.82bn from $7.81bn.
4.1 The sector
The United States property and casualty market wrote $975.8bn of net premiums in 2025, up 5% on AM Best's count. Verisk and APCIA put net written premium at $971bn against $927bn in 2024 and record one of the strongest underwriting results in years: a $63bn underwriting gain against $23bn, on a 92.9% combined ratio. Policyholders' surplus reached $1.2trn while net income after tax fell to $148bn from $169bn.
Two forces set margins from here. Capital is abundant, and price follows capital: Guy Carpenter's rate on line index fell 12% globally and in the United States at 1 January 2026, and 15% in Europe. Verisk attributes the 2025 result to unusually low catastrophe losses rather than to a change in underlying risk, which makes the 92.9% combined ratio a cycle peak rather than a new level.
Table 17. United States property and casualty sector indicators, calendar 2025
| Indicator | 2024 | 2025 | Source |
|---|---|---|---|
| Net premiums written, USD bn | n/a | 975.8 | AM Best |
| Net written premium, USD bn | 927.0 | 971.0 | Verisk and APCIA |
| Net earned premium growth | n/a | 6.3% | Verisk and APCIA |
| Underwriting gain, USD bn | 23.0 | 63.0 | Verisk and APCIA |
| Combined ratio | 96.6% | 92.9% | Verisk and APCIA |
| Net income after tax, USD bn | 169.0 | 148.0 | Verisk and APCIA |
| Policyholders' surplus, USD bn | 1,100 | 1,200 | Verisk and APCIA |
| Global property catastrophe rate on line, 1 January 2026 | n/a | (12.0%) | Guy Carpenter |
| United States property catastrophe rate on line, 1 January 2026 | n/a | (12.0%) | Guy Carpenter |
| Europe property catastrophe rate on line, 1 January 2026 | n/a | (15.0%) | Guy Carpenter |
| State Farm Group net premiums written, USD bn | n/a | 113.79 | AM Best |
| Progressive Insurance Group net premiums written, USD bn | n/a | 83.15 | AM Best |
| Liberty Mutual net premiums written, USD bn | n/a | 37.23 | AM Best |
| Farmers Insurance Group net premiums written, USD bn | n/a | 21.55 | AM Best |
Berkshire's insurance underwriting revenue of $88.9bn in FY2025 equals 9.1% of the $975.8bn written premium pool. The two figures are not on one basis: Berkshire reports earned premiums worldwide, the pool is United States written premium. The ratio sizes the company against the market and is not a market share.
4.2 The peer set and how it was chosen
The selection rule has two tiers, both anchored on the SIC code EDGAR assigns Berkshire, 6331, Fire, Marine and Casualty Insurance.
- Scale peers: United States listed 10-K filers under SIC 6331 with FY2025 revenue above $25bn. Six qualify: Progressive, Chubb, Allstate, Travelers, Hartford Insurance Group and American International Group.
- Structure peers: SIC 6331 filers that also consolidate operating businesses funded alongside insurance float, the feature that separates Berkshire from a pure carrier. Two qualify: Markel Group, which runs Markel Ventures, and Loews, which runs Boardwalk Pipelines, Loews Hotels and Altium Packaging.
CNA Financial meets the SIC and revenue tests and is excluded, because Loews consolidates CNA and including both would count the same underwriting book twice. Every filer in the set reports a fiscal year ended 31 December 2025, so no period adjustment is applied anywhere in this chapter.
Table 18. Peer set, selection rule and source filings
| Company | Ticker | CIK | SIC | Tier | Form | Fiscal period | Filed | Accession number |
|---|---|---|---|---|---|---|---|---|
| Berkshire Hathaway Inc. | BRK.B | 1067983 | 6331 | Scale and structure | 10-K | 2025-12-31 | 2026-03-02 | 0001193125-26-083899 |
| Progressive Corp. | PGR | 80661 | 6331 | Scale | 10-K | 2025-12-31 | 2026-03-02 | 0000080661-26-000086 |
| Chubb Ltd. | CB | 896159 | 6331 | Scale | 10-K | 2025-12-31 | 2026-02-27 | 0000896159-26-000005 |
| Allstate Corp. | ALL | 899051 | 6331 | Scale | 10-K | 2025-12-31 | 2026-02-19 | 0000899051-26-000031 |
| Travelers Companies, Inc. | TRV | 86312 | 6331 | Scale | 10-K | 2025-12-31 | 2026-02-12 | 0000086312-26-000065 |
| Hartford Insurance Group, Inc. | HIG | 874766 | 6331 | Scale | 10-K | 2025-12-31 | 2026-02-20 | 0000874766-26-000012 |
| American International Group, Inc. | AIG | 5272 | 6331 | Scale | 10-K | 2025-12-31 | 2026-02-12 | 0000005272-26-000023 |
| Markel Group Inc. | MKL | 1096343 | 6331 | Structure | 10-K | 2025-12-31 | 2026-02-26 | 0001096343-26-000020 |
| Loews Corp. | L | 60086 | 6331 | Structure | 10-K | 2025-12-31 | 2026-02-10 | 0000060086-26-000008 |

4.3 Like for like comparison
Insurance holding companies do not report a gross margin, and the revenue subtotal is not comparable as filed: Berkshire and Markel present investment gains below revenue, the other seven present them inside it. Three definitions are therefore applied identically to all nine.
- Core revenue removes net investment gains and losses and market risk benefit remeasurement from revenue wherever the filer reports them inside it.
- Core pretax earnings remove those same marks from pretax income, and also remove gains on business disposals and equity method impairment losses.
- Core return on average equity taxes core pretax at each filer's own FY2025 effective rate and divides by average parent equity.
Leverage is debt divided by debt plus total equity. Price to book is market capitalisation over closing parent equity.
Table 19. Like for like comparison, FY2025, fiscal year ended 31 December 2025
| Company | Core revenue, USD m | Revenue growth | Revenue CAGR, FY2023 to FY2025 | Pretax margin, GAAP | Pretax margin, core | Return on average equity | Core return on average equity | Debt to total capital | Price to book | Price to earnings | Price to core earnings |
|---|---|---|---|---|---|---|---|---|---|---|---|
| Berkshire Hathaway | 371,444 | 0.0% | 1.0% | 20.1% | 14.3% | 9.8% | 6.3% | 15.2% | 1.52x | 16.3x | 25.3x |
| Progressive | 86,944 | 15.8% | 18.7% | 16.2% | 15.5% | 40.4% | 38.4% | 18.5% | 4.28x | 11.5x | 12.1x |
| Allstate | 67,853 | 5.5% | 8.7% | 19.4% | 17.3% | 39.5% | 35.1% | 19.7% | 2.20x | 6.6x | 7.4x |
| Chubb | 59,479 | 6.6% | 8.4% | 22.0% | 22.1% | 15.0% | 15.5% | 18.1% | 1.80x | 12.9x | 12.4x |
| Travelers | 48,876 | 5.2% | 8.6% | 16.0% | 16.0% | 20.7% | 20.8% | 22.0% | 2.41x | 12.6x | 12.5x |
| Hartford Insurance Group | 28,468 | 7.0% | 7.3% | 16.8% | 17.1% | 21.7% | 22.1% | 18.7% | 2.00x | 9.9x | 9.7x |
| American International Group | 27,977 | 0.6% | (1.8%) | 14.5% | 17.9% | 7.4% | 9.5% | 18.3% | 1.00x | 13.3x | 10.3x |
| Loews | 18,535 | 5.4% | 7.8% | 12.4% | 12.8% | 9.3% | 10.3% | 32.6% | 1.21x | 13.5x | 12.3x |
| Markel Group | 15,513 | 4.7% | 4.2% | 16.5% | 10.7% | 11.9% | 7.3% | 18.8% | 1.23x | 10.9x | 17.6x |
| Peer median, eight competitors | 38,672 | 5.4% | 8.1% | 16.4% | 16.6% | 17.8% | 18.2% | 18.8% | 1.90x | 12.0x | 12.2x |
Market capitalisation uses the last traded price on 2 September 2026 and the share count on the 10-K cover page, dated between 30 January and 20 February 2026. Every filer in the table is priced on that same basis, so the comparison is like for like. Buybacks after the cover date are not captured, so price to book is marginally overstated for any filer that has retired stock since.

Progressive is the outlier on both growth and return: core revenue up 15.8%, a 38.4% core return on average equity and a 4.28 times book multiple. Chubb runs the widest core margin at 22.1% on 6.6% growth. Allstate's 39.5% return on average equity is flattered by a $1,603m gain on the disposal of a business, which the core measure removes and which cuts the core return to 35.1%. Berkshire and Markel occupy the same corner for the same reason: both consolidate low margin operating revenue alongside insurance.
4.4 Why Berkshire's core margin sits below the median
The gap is segment mix, and Figure 16 sizes it.

McLane and Pilot supply 25.3% of segment revenue and 1.7% of segment pretax earnings, on margins of 1.3% and 0.5%. Strip both and segment margin rises to 18.5% from 14.0%. The insurance group supplies 28.3% of revenue and 47.8% of earnings on a 23.7% pretax margin. BNSF is the best margin in the group at 30.5%.
The same mix explains flat group revenue. Insurance underwriting revenue rose 0.7% to $88,902m, service and retailing rose 7.0% and manufacturing rose 1.6%. Pilot fell 10.0% to $42,198m and McLane fell 1.8% to $50,998m, $5,602m of decline between them. Segment revenue fell $2,520m to $368,372m, corporate reconciling items and eliminations rose $2,531m to $3,072m, and consolidated core revenue finished at $371,444m against $371,433m.
Underwriting itself weakened while the sector improved. Berkshire's pretax underwriting earnings fell 17.1% to $9,460m, GEICO fell to $6,824m from $7,813m, and the reinsurance group fell to $1,851m from $2,737m. Against a sector combined ratio moving from 96.6% to 92.9%, that is underperformance of the cycle rather than participation in it. The $9,460m underwriting profit still means float carried a negative cost in FY2025, worth about 5.4% of the closing balance.
4.5 GAAP earnings against core earnings
Berkshire's reported pretax income of $82,459m contains $39,078m of investment gains, almost all of it the unrealised mark on the listed equity portfolio, and $9,590m of equity method losses driven by impairments at Kraft Heinz and Occidental Petroleum. Core pretax earnings are $52,971m, and the $29,488m adjustment is 35.8% of reported pretax income, the largest in the set. Markel's is 39.4% of a much smaller base. For the seven filers without a consolidated operating book the adjustment stays inside 29%, and for four of them inside 4%.

Table 20. GAAP to core pretax reconciliation, FY2025 (USD millions)
| Company | Pretax income, as reported | Investment gains and losses | Market risk benefit remeasurement | Business disposal gains | Equity method impairment losses | Core pretax earnings | Effective tax rate |
|---|---|---|---|---|---|---|---|
| Berkshire Hathaway | 82,459 | (39,078) | 0 | 0 | 9,590 | 52,971 | 18.4% |
| Progressive | 14,223 | (727) | 0 | 0 | 0 | 13,496 | 20.5% |
| Allstate | 13,156 | 168 | 0 | (1,603) | 0 | 11,721 | 22.0% |
| Chubb | 13,044 | (211) | 288 | 0 | 0 | 13,121 | 18.6% |
| Travelers | 7,796 | 48 | 0 | 0 | 0 | 7,844 | 19.3% |
| Hartford Insurance Group | 4,760 | 100 | 0 | 0 | 0 | 4,860 | 19.4% |
| American International Group | 3,879 | 1,202 | 0 | (81) | 0 | 5,000 | 20.2% |
| Loews | 2,283 | 81 | 0 | 0 | 0 | 2,364 | 22.4% |
| Markel Group | 2,733 | (1,076) | 0 | 0 | 0 | 1,657 | 21.2% |
Of Berkshire's $39,078m, $39,981m is the unrealised mark on equities, offset by $18m of realised equity losses, $30m of debt security losses and $855m on other investments. The equity method loss splits $4,393m to Kraft Heinz and $5,302m to Occidental, with $105m of income elsewhere.
Core measures understate Berkshire by construction. The $297.8bn equity portfolio is carried in the equity base of the return calculation while its price appreciation is removed from the numerator. Adding the FY2025 investment marks and the equity method losses back at a 21% statutory rate lifts the return on average equity from 6.3% to 9.5%, against the 9.8% the GAAP measure shows. A reader who treats portfolio appreciation as part of the return should read the GAAP column, where Berkshire's 20.1% pretax margin is the second widest in the set behind Chubb.
4.6 Valuation

Price to book across the nine is explained by return on equity with a slope of 0.066 times book per point of return. Berkshire's 9.8% return implies 1.32 times book. It trades at 1.52 times, 15% above the line. American International Group trades at 1.00 times on a 7.4% return, closest to the line from below; Progressive at 4.28 times on 40.4% sits above it.
The fit is thin and Progressive drives much of it, so the residual is an observation rather than a valuation. Two balance sheet items explain a premium that earnings alone do not. Cash and Treasury bills total $373,311m, 34.1% of the $1,093.6bn market capitalisation. The listed equity portfolio adds $297,778m, a further 27.2%. Together they cover 61.4% of the equity value. Debt to total capital of 15.2% is the lowest in the set, against an 18.8% peer median and 32.6% at Loews, whose figure carries consolidated Boardwalk Pipelines borrowings. Berkshire's figure carries $83,318m of BNSF and Berkshire Hathaway Energy debt, which is serviced by those subsidiaries rather than by the parent.
Book value per share is $332.55 on the Class B equivalent count of 2,157,335,139 shares, against a $506.90 last trade on 2 September 2026.
5 Material Events & Contracts
Berkshire filed ten current reports in the twelve months to 2 September 2026 and none of them announced an acquisition. The news was governance and capital structure: Greg Abel took the chief executive seat on 1 January 2026, the board split the Chairman and Chief Executive roles in the bylaws first, the finance and legal benches were rebuilt around him, and on 4 March 2026 the company started buying its own stock again after a full year of buying none. The repurchase restart is the item that moves cash. Berkshire spent about $4.8bn on its own shares in the first half of 2026 and raised $3.08bn of yen debt across the two note issues in the window, so the period was a modest net return of capital rather than a balance sheet expansion. Berkshire is a domestic filer and filed no Form 6-K in the period.
Table 21. Material events from 8-K filings, twelve months to 2 September 2026
Sorted newest first. Every row is one filing.
| Filed | Form and items | Event | Accession |
|---|---|---|---|
| 2026-08-11 | 8-K, 2.02, 9.01 | Second quarter 2026 net earnings of $25,667m and operating earnings of $12,983m, with about $4.5bn of stock repurchased in the quarter and float at $177.5bn. | 0001193125-26-344495 |
| 2026-05-07 | 8-K, 2.02, 5.02, 5.03, 5.07, 9.01 | Annual meeting of 2 May 2026 returned all thirteen directors, carried say on pay on 93.0% of votes cast and defeated the workforce disclosure proposal on 15.0% support; Chang's chief financial officer salary set at $8,000,000, Hamburg granted a NetJets flight benefit, bylaws amended again. | 0001193125-26-212148 |
| 2026-04-16 | 8-K, 8.01, 9.01 | Six yen senior note series totalling 272.3bn JPY, about $1.71bn, issued at coupons of 2.077% to 4.037% and maturities from 2029 to 2056. | 0001193125-26-159326 |
| 2026-03-05 | 8-K, 8.01, 9.01 | Berkshire disclosed that it began repurchasing Class A and Class B stock on 4 March 2026 under its standing intrinsic value policy, framing the disclosure as transparency around the leadership transition. | 0001193125-26-092557 |
| 2026-03-02 | 8-K, 2.02, 9.01 | Full year 2025 net earnings of $66,968m against $88,995m and operating earnings of $44,486m against $47,437m, after an $8,255m impairment of Kraft Heinz and Occidental. | 0001193125-26-085801 |
| 2026-01-06 | 8-K/A, 5.02 | Greg Abel became President and Chief Executive Officer on 1 January 2026 and his annual cash salary rose to $25,000,000 on that date. | 0001193125-26-004727 |
| 2025-12-11 | 8-K, 5.02, 9.01 | Leadership slate reset: Chang succeeds Hamburg as chief financial officer on 1 June 2026, Pierce replaces Combs at GEICO, Combs leaves for JPMorgan Chase, Johnson adds the consumer products group, O'Sullivan becomes the first General Counsel. | 0001193125-25-314935 |
| 2025-11-21 | 8-K, 8.01, 9.01 | Four yen senior note series totalling 210.1bn JPY, about $1.37bn, issued at coupons of 1.510% to 2.810% and maturities from 2028 to 2040. | 0001193125-25-290864 |
| 2025-11-03 | 8-K, 2.02, 9.01 | Third quarter 2025 net earnings of $30,796m and operating earnings of $13,485m, the strongest operating quarter of that year. | 0001193125-25-262260 |
| 2025-10-03 | 8-K, 5.03, 9.01 | The board amended and restated the bylaws on 30 September 2025 to separate Chairman from Chief Executive ahead of the 1 January 2026 handover, adding bylaw 3.5 and reworking Section 4. | 0001193125-25-229405 |
Three of the ten are pure earnings releases carrying only Item 2.02 and the exhibit item. The May 2026 filing bundles the first quarter release with three governance items. The remaining six split evenly: the September 2025 bylaw amendment and two officer changes on the governance side, two note issues and the repurchase restart on the capital side.

The repurchase restart is the event with the largest cash consequence
Berkshire bought no stock at all in 2025. Class A equivalent shares stood at 1,438,223 on 30 September 2025 and the same 1,438,223 on 31 December 2025, and Schedule I of the 10-K records nil parent company treasury stock purchases for the year against $2,918m in 2024. The 5 March 2026 filing then disclosed a restart dated 4 March 2026. By 30 June 2026 the count had fallen to 1,431,693, so 6,530 Class A equivalent shares, 0.45% of the register, were retired inside four months. Berkshire gives the second quarter as about $4.5bn and the six months as about $4.8bn, which leaves roughly $0.3bn for the first quarter. Both published figures are approximations, so the first quarter split is an inference rather than a disclosure.
The company bound itself to nothing. The filing repeats that the policy obligates no specific number of shares, that purchases may run in the open market or in privately negotiated transactions including under a Rule 10b5-1 plan, and that they may be suspended at any time. The filing frames the restart as a judgement on price against conservatively determined intrinsic value and attaches no size to it; chapter 9 prices the shares bought against book value.
What sits inside the 2025 earnings gap

The gap between the two series in 2025 sits in the investment line. Investment gains added $30,737m to 2025 GAAP earnings, of which $12.9bn was the change in unrealised gains on equity holdings and $17.8bn was after tax realised gains on sales. Against that, an $8,255m after tax other than temporary impairment of Kraft Heinz and Occidental ran through GAAP earnings. Schedule I of the 10-K records a $5.0bn other than temporary impairment on the parent's Kraft Heinz stake in 2025, a holding it carries at 27.5% under the equity method.
Insurance float reached $177.5bn at 30 June 2026, which Berkshire states is about $1.1bn above year end 2025. The rounded levels it publishes, $176bn at 31 December 2025 and $177.5bn at 30 June 2026, imply $1.5bn instead. The stated change is the reliable figure and is the one used here; the rounding in the published levels is the reconciling item.
Table 22. Material contracts
Filed with or incorporated into the FY2025 10-K, accession 0001193125-26-083899, and filed as 8-K exhibits inside the window.
| Counterparty | Subject | Term | Filing |
|---|---|---|---|
| Berkshire directors and officers | Form of indemnification agreement to the fullest extent Delaware law allows, paid within thirty days of written demand, expenses advanced within two business days of request, directors and officers policy cover at the level given any director, authorised by bylaw 8 | Survives the indemnitee leaving office and binds any successor by merger or purchase | 10-K Exhibit 10.1, filed as a document, new this year, 0001193125-26-083899 |
| Mizuho Securities USA LLC and Merrill Lynch International | Underwriting agreement for 272.3bn JPY of senior notes in six series | Dated 10 April 2026, performed at settlement on 16 April 2026 | 8-K Exhibit 1.1, 0001193125-26-159326 |
| Mizuho Securities USA LLC and Merrill Lynch International | Underwriting agreement for 210.1bn JPY of senior notes in four series | Dated 14 November 2025, performed at settlement on 20 November 2025 | 8-K Exhibit 1.1, 0001193125-25-290864 |
| Berkshire Hathaway Finance Corporation and The Bank of New York Mellon Trust Company, N.A. | Indenture governing both yen issues, Berkshire as issuer and as guarantor of finance subsidiary debt | Dated 31 January 2025, open ended | 10-K Exhibit 4.7, by reference to Form S-3 No. 333-284622 |
| The Bank of New York Mellon Trust Company, N.A., as trustee | Ten officers' certificates, one per note series, setting coupon, maturity and redemption terms | Dated 20 November 2025 and 16 April 2026, running to 2056 | 8-K Exhibits 4.2 to 4.5 and 4.2 to 4.7, 0001193125-25-290864 and 0001193125-26-159326 |
| Berkshire Hathaway Finance Corporation and The Bank of New York Mellon Trust Company, N.A. | Four earlier indentures still governing outstanding Berkshire and finance subsidiary debt | Dated 2003, 2010, 2016 and 2022, open ended | 10-K Exhibits 4.1, 4.2, 4.3 and 4.6, all by reference |
| The First National Bank of Chicago, as trustee | BNSF indenture carried at the parent level | Dated 1 December 1995, open ended | 10-K Exhibit 4.4, by reference |
| The Bank of New York, as trustee | MidAmerican Energy Holdings indenture, the entity now Berkshire Hathaway Energy | Dated 4 October 2002, open ended | 10-K Exhibit 4.5, by reference |
| General Re Corporation, BNSF and Precision Castparts Corporation | The three merger agreements behind the largest acquisitions | Dated 1998, 2009 and 2015, performed | 10-K Exhibits 2(i), 2(ii) and 2(iii), all by reference |
| Marc D. Hamburg | Up to 30 flight hours a year on a midsized NetJets aircraft with a tax gross up, costed by Berkshire at about $490,000 a year | 1 June 2026 to no later than 31 May 2037 | 8-K Item 5.02(e), 0001193125-26-212148 |
| Charles C. Chang | Chief Financial Officer cash salary of $8,000,000 a year | From 1 June 2026 | 8-K Item 5.02(c), 0001193125-26-212148 |
| Gregory E. Abel | Chief Executive Officer cash salary of $25,000,000 a year | From 1 January 2026 | 8-K Item 5.02(c), 0001193125-26-004727 |
Two entries in the 10-K exhibit index changed this year, and both track the transition. Exhibit 3(ii) now points at the October 2025 8-K rather than the 8-K filed on 10 May 2023. Exhibit 10.1 was replaced outright: the FY2024 10-K listed a 2013 equity commitment letter with Hawk Acquisition Holding Corporation, incorporated by reference; the FY2025 10-K drops it and files the form of indemnification agreement as a document instead. Berkshire's only Exhibit 10 slot moved from a spent thirteen year old deal commitment to a live standing obligation to its own directors and officers, in the same annual report that first carries Abel's signature as chief executive and follows the first in house General Counsel appointment. Berkshire states no reason. The recitals say what the document does: they put indemnification into a contract that holds regardless of any later amendment to the Certificate of Incorporation or bylaws or any change in the composition of the board.
The 10-K also states that other long term debt instruments are not filed because the securities they authorise do not exceed 10% of consolidated total assets, so the exhibit index covers only those instruments above that threshold.
Debt raised: two yen offerings, one syndicate, one shelf
Both offerings were wholly yen denominated, both were sold under the January 2025 shelf, Registration No. 333-284622, both were underwritten by Mizuho Securities USA LLC and Merrill Lynch International, and both were opined on by Baker & McKenzie LLP. Combined issuance was 482.4bn JPY, about $3.08bn.
Table 23. Yen senior notes issued in the window
| Issue date | Series | Coupon range | Maturities | Principal | USD equivalent |
|---|---|---|---|---|---|
| 2025-11-20 | 4 | 1.510% to 2.810% | 2028 to 2040 | 210.1bn JPY | $1.37bn |
| 2026-04-16 | 6 | 2.077% to 4.037% | 2029 to 2056 | 272.3bn JPY | $1.71bn |
USD equivalents and the fixing rates come from the Rule 424(b)(5) registration fee tables, accessions 0001193125-25-286108 at 153.06 JPY and 0001193125-26-154274 at 159.64 JPY to the dollar.
The April 2026 8-K prints the third tranche as 22,300,000,00 JPY, one digit short, and omits the currency symbol on the fifth and sixth tranches; the registration fee table resolves all three, the tranche is 22.3bn JPY and every tranche is yen. The figures here are the filed figures read against the fee table.
Berkshire paid up between the two deals. At adjacent tenors the April 2026 coupons sit 57 to 66 basis points above the November 2025 coupons, part of which is the extra year of term, and the April deal stretched the longest maturity from 2040 to 2056. Parent company yen and euro debt is what produces the foreign exchange line that swings operating earnings: gains of $575m in the first half of 2026 against losses of $1.59bn in the first half of 2025. The 10-K puts parent par value outside the dollar at 3.6bn EUR and 2,343bn JPY at 31 December 2025, and parent guarantees of subsidiary debt at $20.1bn.
Governance: the roles were separated before the handover
The bylaws were amended twice. On 30 September 2025 the board added Paragraph 3.5 to Section 3 and reworked Section 4 so that Chairman and Chief Executive need not be the same person, with Buffett staying as Chairman and Abel becoming Chief Executive on 1 January 2026. On 3 May 2026, the day after the annual meeting, the board amended Sections 4, 6 and 10 to conform officer roles to the current operating structure. The constitutional change came three months before the handover. Chapter 6 sets out how shareholders voted at the meeting that sat between the two amendments.
What could not be verified
Berkshire disclosed no dollar authorisation, no share count and no expiry for the repurchase programme, so the pace after 30 June 2026 cannot be estimated from filings. It disclosed no price paid per share for the first half 2026 repurchases beyond the aggregate. Charles C. Chang's compensation beyond the $8,000,000 cash salary was described as not finalised in the December 2025 filing and only the salary was disclosed in May 2026. The reason for adding Exhibit 10.1 to the FY2025 10-K is not stated in any filing. Whether the 4 March 2026 repurchases ran through a Rule 10b5-1 plan is not disclosed, only that they may.
6 Ownership, Voting Power & Annual Meeting
Berkshire's two share classes separate money from control. Warren Buffett held 13.7% of the economics and 30.2% of the votes at the 4 March 2026 record date, a ratio of 2.2 to 1. The three index managers that dominate the Class B register held 16.3% of the economics and 5.4% of the votes, a ratio of 0.33 to 1. Buffett's latest Schedule 13D amendment, dated 14 July 2026, still reports 29.7% of the vote against 13.2% of the economics.
The mechanics of the two classes
Each Class A share carries one vote. Each Class B share carries one ten thousandth of a vote. Each Class A share converts into 1,500 Class B shares, so a Class A share carries 1,500 times the economic claim and 10,000 times the vote. A dollar in Class B buys 15% of the voting weight that a dollar in Class A buys.
Table 24. Class A and Class B, economic weight against voting weight at the 4 March 2026 record date
| Measure | Class A | Class B | Total |
|---|---|---|---|
| Shares outstanding and entitled to vote | 510,766 | 1,390,722,404 | n/a |
| Votes per share | 1.0000 | 0.0001 | n/a |
| Votes, Class A equivalents | 510,766.0 | 139,072.2 | 649,838.2 |
| Share of total voting power | 78.6% | 21.4% | 100.0% |
| Economic units, Class A equivalents | 510,766.0 | 927,148.3 | 1,437,914.3 |
| Share of total economic interest | 35.5% | 64.5% | 100.0% |
Source: DEF 14A filed 13 March 2026, accession 0001193125-26-106253.
Class B carries 64.5% of the economics and 21.4% of the votes. A year earlier, at the 5 March 2025 record date, Class B carried 62.1% of the economics and 19.7% of the votes. Conversion of Class A into Class B lifts both figures by about two points a year.
Who owns what, and who votes it
Table 25. Beneficial ownership at 4 March 2026, economic interest separated from voting power
| Holder | Class A shares | Class B shares | % of Class A | % of Class B | Economic interest | Voting power | Voting to economic |
|---|---|---|---|---|---|---|---|
| Insiders | |||||||
| Warren E. Buffett | 196,317 | 1,114 | 38.4% | under 0.1% | 13.7% | 30.2% | 2.21 |
| Susan A. Buffett | 80 | 3,190,932 | under 0.1% | 0.2% | 0.2% | 0.1% | n/a |
| Ajit Jain | 166 | 107,660 | under 0.1% | under 0.1% | under 0.1% | under 0.1% | n/a |
| Gregory E. Abel | 249 | 2,363 | under 0.1% | under 0.1% | under 0.1% | under 0.1% | n/a |
| All directors and officers as a group | 197,224 | 3,318,752 | 38.6% | 0.2% | 13.9% | 30.4% | 2.19 |
| Institutions, holdings at 31 December 2025 | |||||||
| The Vanguard Group | 0 | 157,103,196 | n/a | 11.3% | 7.3% | 2.4% | 0.33 |
| BlackRock Inc. | 0 | 121,286,101 | n/a | 8.7% | 5.6% | 1.9% | 0.33 |
| State Street Corporation | 0 | 73,925,068 | n/a | 5.3% | 3.4% | 1.1% | 0.33 |
| Three index managers combined | 0 | 352,314,365 | n/a | 25.3% | 16.3% | 5.4% | 0.33 |
| FMR LLC, Class A only | 24,558 | 0 | 4.8% | n/a | 1.7% | 3.8% | 2.21 |
Source: DEF 14A accession 0001193125-26-106253 for the insiders and the three index managers, which the proxy reports from their Form 13F filings. FMR from Schedule 13G/A accession 0000315066-26-000368. Economic interest, voting power and the ratio are computed on the record date share counts in Table 24.
The Class B percentages above are computed on the 4 March 2026 record date count and differ slightly from the proxy's own. The proxy states 11.4% for Vanguard and approximately 8.8% for BlackRock; on the 1,390,722,404 Class B shares outstanding at the record date those same share counts give 11.3% and 8.7%. The difference is the denominator: both stated figures reproduce exactly on 1,378,545,639 Class B shares, the count Berkshire reported outstanding at 21 July 2025, giving 11.40% and 8.80%. State Street's 5.3% reproduces on the record date count and not on the July 2025 count. The filed figures are left unadjusted, and Tables 25 and 26 use the record date count throughout.
Buffett's 196,317 votes exceed the 139,072 votes carried by every Class B share in existence, by 41%, so Class B holders acting unanimously cannot outvote him. The three largest institutional holders own a quarter of Class B and control one vote in eighteen. FMR, with 1.7% of the economics, controls 3.8% of the votes, more than Vanguard's 2.4% on four times the money, because FMR holds Class A.
The proxy discloses one constraint on the controlling block. Buffett has a voting agreement with Berkshire: if his combined voting power exceeds 49.9% of the total, he votes the excess proportionately with other shareholders. At 30.2% the cap is not binding.

The direction of travel
Buffett converts Class A into Class B each June and November and gives the Class B to five foundations. His Class A block fell 8.8% across six dated disclosures, from 206,363 shares on 25 November 2024 to 188,290 on 14 July 2026. His economic interest fell 1.2 points over the same disclosures, from 14.4% at the March 2025 record date to 13.2% in July 2026.
Voting power did not follow. It moved between 29.7% and 30.4% across the six disclosures and ended at 29.7%, within 0.7 points of where it started. Berkshire's buybacks and other holders' conversions shrink Class A at a pace close to the pace of the gifts, so Buffett's share of Class A rose from 37.9% to 38.2% while his share count fell. On this record the gifts transfer economics faster than they transfer control.

Each conversion of 8,000 Class A shares adds 12 million Class B shares to the tradeable float. It removes 8,000 votes from the block and returns 1,200, a net loss of 6,800 votes out of about 650,000.
Institutional ownership
Table 26. Form 13F institutional ownership, four quarters
| Quarter end | Form 13F filings reporting Class B | Vanguard complex, Class B | State Street, Class B | Combined | Combined % of Class B | Combined % of votes |
|---|---|---|---|---|---|---|
| 30 September 2025 | 4,689 | 154,553,095 | 72,812,974 | 227,366,069 | 16.3% | 3.5% |
| 31 December 2025 | 5,003 | 157,333,676 | 73,925,068 | 231,258,744 | 16.6% | 3.6% |
| 31 March 2026 | 4,960 | 158,514,889 | 74,099,062 | 232,613,951 | 16.7% | 3.6% |
| 30 June 2026 | 5,007 | 160,408,794 | 75,747,788 | 236,156,582 | 17.0% | 3.6% |
Source: Form 13F filings indexed on CUSIP 084670702. The filer count is the number of filings reporting that CUSIP for the quarter. The Vanguard complex is the sum of every Vanguard named filer, deduplicated by CIK, with an amended filing replacing the original. Percentages use the 4 March 2026 record date counts.
The holder base widened by 318 filings, or 6.8%, over the four quarters, and the two largest index managers added 8.8 million Class B shares, 3.9%. Both series point the same way: more institutions, larger passive positions, no change in who decides. Those 236 million Class B shares carry 23,616 votes, an eighth of Buffett's block.

The Vanguard register shows a structural change rather than a trading one. Vanguard reported through a single filer, The Vanguard Group Inc, up to the December 2025 quarter, then split the assets across ten separately reporting entities from the March 2026 quarter. The complex total rose through the split, so the reorganisation moved shares between filers and not out of the register.
Schedule 13D and 13G filings, two years
Table 27. Schedule 13D and 13G filings on Berkshire Hathaway, September 2024 to September 2026
| Filed | Form | Filer | Event date | Class | Shares | % of class | What changed |
|---|---|---|---|---|---|---|---|
| 15 Jul 2026 | SC 13D/A no. 81 | Warren E. Buffett | 14 Jul 2026 | Class A | 188,290 | 38.2% | Converted 8,000 Class A into 12,000,000 Class B and gave all of it to four family foundations. Voting power 29.7%, economic interest 13.2%. |
| 29 Apr 2026 | SC 13G | Vanguard Capital Management LLC | 31 Mar 2026 | Class B | 134,303,785 | 9.65% | New filer created by the Vanguard reorganisation. Sole voting power over 16,888,250 shares only. |
| 26 Mar 2026 | SC 13G/A no. 13 | The Vanguard Group Inc | 13 Mar 2026 | Class B | 0 | 0.00% | Exit filing. The entity reports it no longer holds more than 5%. |
| 5 Feb 2026 | SC 13G/A no. 3 | FMR LLC and Abigail P. Johnson | 31 Dec 2025 | Class A | 24,558 | 4.7% | Class A stake falls below the 5% threshold from 33,428 shares. |
| 12 Nov 2025 | SC 13D/A no. 80 | Warren E. Buffett | 10 Nov 2025 | Class A | 196,317 | 37.7% | Converted 1,800 Class A into 2,700,000 Class B and gave all of it to four family foundations. Voting power 29.8%, economic interest 13.6%. |
| 30 Jun 2025 | SC 13D/A no. 79 | Warren E. Buffett | 27 Jun 2025 | Class A | 198,117 | 37.0% | Converted 8,239 Class A into 12,358,500 Class B and gave 12,358,321 to the Gates Foundation Trust and four family foundations. Voting power 29.7%, economic interest 13.8%. |
| 25 Nov 2024 | SC 13D/A | Warren E. Buffett | 25 Nov 2024 | Class A | 206,363 | 37.5% | Annual November conversion and gift of Class B shares to family foundations. |
Source: Schedule 13D and 13G filings, accessions 0001193125-26-304838, 0002100119-26-000227, 0000102909-26-000775, 0000315066-26-000368, 0001193125-25-277436, 0000950170-25-091802 and 0001193125-24-265100.
No activist filing appears in the window. Every 13D event is a scheduled gift by the controlling holder. Every 13G event is an index manager crossing a threshold or reorganising its filing entities. Vanguard Capital Management's disclosure of sole voting power over 16,888,250 shares out of 134,303,785 held is the sharpest illustration of the register's shape: the largest economic holder in Class B directs the votes on one eighth of its own position.
The 2026 annual meeting
Berkshire held the meeting on 2 May 2026 in Omaha. Class A and Class B voted together as a single class. The 8-K reports votes in Class A equivalents and carries no broker nonvote column, so broker nonvotes read n/a throughout. The proxy states that abstentions and broker nonvotes have no effect on the election of directors, that abstentions are the equivalent of an against vote on the other questions, and that broker nonvotes have no effect on them.
Votes cast came to 435,305, which is 67.0% of the 649,838 votes outstanding. Buffett's 196,317 votes were 45.1% of the votes cast.
Table 28. Voting results, annual meeting of 2 May 2026
| Item | Proponent | Board recommendation | For | Against or withheld | Abstain | Broker nonvotes | Outcome |
|---|---|---|---|---|---|---|---|
| 1. Election of Gregory E. Abel | Board | For | 431,852 | 3,454 | n/a | n/a | Elected |
| 1. Election of Howard G. Buffett | Board | For | 428,007 | 7,299 | n/a | n/a | Elected |
| 1. Election of Susan A. Buffett | Board | For | 427,052 | 8,254 | n/a | n/a | Elected |
| 1. Election of Warren E. Buffett | Board | For | 424,675 | 10,631 | n/a | n/a | Elected |
| 1. Election of Stephen B. Burke | Board | For | 403,648 | 31,658 | n/a | n/a | Elected |
| 1. Election of Kenneth I. Chenault | Board | For | 410,696 | 24,610 | n/a | n/a | Elected |
| 1. Election of Christopher C. Davis | Board | For | 426,119 | 9,187 | n/a | n/a | Elected |
| 1. Election of Susan L. Decker | Board | For | 386,648 | 48,658 | n/a | n/a | Elected |
| 1. Election of Charlotte Guyman | Board | For | 381,226 | 54,080 | n/a | n/a | Elected |
| 1. Election of Ajit Jain | Board | For | 430,489 | 4,817 | n/a | n/a | Elected |
| 1. Election of Thomas S. Murphy, Jr. | Board | For | 410,831 | 24,475 | n/a | n/a | Elected |
| 1. Election of Wallace R. Weitz | Board | For | 429,478 | 5,828 | n/a | n/a | Elected |
| 1. Election of Meryl B. Witmer | Board | For | 427,348 | 7,958 | n/a | n/a | Elected |
| 2. Advisory vote on executive compensation | Board | For | 403,351 | 30,251 | 1,703 | n/a | Approved with 93.0% of votes for and against |
| 3. Frequency of the advisory pay vote, three years | Board | Three years | 288,858 | 144,765 | 924 | n/a | Three years with 66.6% |
| 4. Report on board oversight of workforce and human capital management | Meredith Benton of Whistle Stop Capital, for Myra K. Young | Against | 65,023 | 367,387 | 2,895 | n/a | Rejected with 15.0% support |
Source: Form 8-K item 5.07 filed 7 May 2026, accession 0001193125-26-212148, for the votes. DEF 14A accession 0001193125-26-106253 for the proponent and the board recommendation. On item 3 the against column holds the 143,050 votes for one year and the 1,715 votes for two years.
Say on pay passed with 93.0% of the votes for and against, and the frequency vote returned a three year cycle with 66.6%. One third of the frequency vote, 143,050 votes, asked for an annual vote, a wider dissent than the say on pay margin alone suggests.
The single shareholder proposal drew 15.0% support of the votes for and against. At the 2025 meeting, seven shareholder proposals drew between 0.7% and 3.6%, so the 2026 proposal drew more than four times the best 2025 result. Its subject was board oversight of workforce and human capital management, and it was voted at the first annual meeting after Greg Abel became chief executive on 1 January 2026.
Withhold votes concentrated on three long serving independent directors. Charlotte Guyman drew 12.4% withheld, Susan L. Decker 11.2% and Stephen B. Burke 7.3%. Abel drew 0.8%, the lowest of the thirteen.
Table 29. Director election, withhold rates at the 2026 meeting
| Director | For | Withheld | Withheld % of votes cast | Withheld % if the Buffett block voted for |
|---|---|---|---|---|
| Charlotte Guyman | 381,226 | 54,080 | 12.4% | 22.6% |
| Susan L. Decker | 386,648 | 48,658 | 11.2% | 20.4% |
| Stephen B. Burke | 403,648 | 31,658 | 7.3% | 13.2% |
| Kenneth I. Chenault | 410,696 | 24,610 | 5.7% | 10.3% |
| Thomas S. Murphy, Jr. | 410,831 | 24,475 | 5.6% | 10.2% |
| Warren E. Buffett | 424,675 | 10,631 | 2.4% | 4.4% |
| Christopher C. Davis | 426,119 | 9,187 | 2.1% | 3.8% |
| Susan A. Buffett | 427,052 | 8,254 | 1.9% | 3.5% |
| Meryl B. Witmer | 427,348 | 7,958 | 1.8% | 3.3% |
| Howard G. Buffett | 428,007 | 7,299 | 1.7% | 3.1% |
| Wallace R. Weitz | 429,478 | 5,828 | 1.3% | 2.4% |
| Ajit Jain | 430,489 | 4,817 | 1.1% | 2.0% |
| Gregory E. Abel | 431,852 | 3,454 | 0.8% | 1.4% |
Source: Form 8-K item 5.07, accession 0001193125-26-212148. The final column removes Buffett's 196,317.11 votes from the base. It is conditional on that block voting for each nominee, which the filings do not disclose.
Berkshire's corporate governance guidelines require a nominee who receives more withheld than for votes to offer a resignation, and no nominee came close. Turnout was 67.0% of voting power in 2026 against 66.5% in 2025, when 451,252 of 678,944 votes were cast, and withhold rates ranged from 0.8% for Gregory E. Abel to 12.4% for Charlotte Guyman.
What it means for the stock
BRK.B is a claim on 64.5% of Berkshire's economics that carries 21.4% of its votes. Nothing on the 2026 ballot changed that, and nothing on the register threatens it: no activist filed in two years, and the three largest passive holders control 5.4% of the votes on 16.3% of the economics. Control moves on the schedule of Buffett's conversions and gifts, which over the last six disclosures transferred economics roughly twice as fast as votes. Price BRK.B as the register describes it: the float supplies the capital, and a board elected by a single block supplies the decisions.
7 Insider Activity
Berkshire insiders were net buyers of BRK.B through the chief executive handover. Across the twelve months to 2 September 2026, open market purchases totalled 35,524 Class B equivalent shares for $17.34m against a single open market sale of 15,000 Class B shares for $7.51m. The buy to sell ratio, computed on open market transactions only, is 2.37 to 1 by share count and 2.31 to 1 by value. In the preceding twelve months the same measure was zero: no insider bought a share on the open market, and 304,500 Class B equivalent shares left insider hands for $141.31m.
The three buyers are the new operating leadership. Greg Abel bought 21 Class A shares on 4 March 2026, his first open market purchase since March 2023, on the same day Berkshire disclosed it had commenced repurchasing its own stock. Michael O'Sullivan and Charles Chang, the general counsel and chief financial officer named in the 8 December 2025 leadership announcement, each bought within weeks of filing a Form 3.
Everything on the sell side is structural rather than discretionary. Of 35 transaction lines in the window, 26 are charitable gifts or Class A into Class B conversions that fund those gifts. They carry 14,741,525 Class B equivalent shares out of insider hands at a price of nil or none, and no part of that is a sale. The plan or award bucket is empty: no Form 4 in the window carries an option exercise code M, an award code A, a tax withholding code F or a Rule 10b5-1 affirmation, no Form 5 was filed, and the form-144 endpoint returns nothing for this issuer. Berkshire pays these officers in cash, with Abel's annual salary at $25.0m and Chang's at $8.0m and no equity grant disclosed.
Table 30. Insider transaction ledger, twelve months to 2 September 2026
Every Form 4 line with a transaction date in the window. Price is the price per share of the class named, as reported on the form. It reads nil where the form states a zero price and n/a where it states none. Resulting holding is the shares of that class owned following the transaction, as reported. Roles: CEO is president and chief executive officer, VC is vice chairman insurance operations, GC is senior vice president, general counsel and secretary, CFO is senior vice president and chief financial officer.
| Date | Insider | Role | Code | Class | Shares | Price (USD) | Resulting holding | Held |
|---|---|---|---|---|---|---|---|---|
| 2025-09-24 | Ajit Jain | VC, director | G gift | B | 32 | n/a | 384 | direct |
| 2025-09-26 | Ajit Jain | VC, director | S sale | B | 15,000 | 501.00 | 107,308 | indirect |
| 2025-10-22 | Ajit Jain | VC, director | G gift | B | 32 | n/a | 352 | direct |
| 2025-11-03 | Charlotte Guyman | Director | C conversion | A | 1 | n/a | 54 | direct |
| 2025-11-03 | Charlotte Guyman | Director | C conversion | B | 1,500 | nil | 3,872 | direct |
| 2025-11-03 | Charlotte Guyman | Director | G gift | B | 410 | nil | 3,462 | direct |
| 2025-11-10 | Warren E. Buffett | Chairman, 10 percent owner | C conversion | A | 1,800 | n/a | 196,317 | direct |
| 2025-11-10 | Warren E. Buffett | Chairman, 10 percent owner | C conversion | B | 2,700,000 | nil | 2,701,114 | direct |
| 2025-11-10 | Warren E. Buffett | Chairman, 10 percent owner | G gift | B | 1,500,000 | nil | 1,201,114 | direct |
| 2025-11-10 | Warren E. Buffett | Chairman, 10 percent owner | G gift | B | 400,000 | nil | 801,114 | direct |
| 2025-11-10 | Warren E. Buffett | Chairman, 10 percent owner | G gift | B | 400,000 | nil | 401,114 | direct |
| 2025-11-10 | Warren E. Buffett | Chairman, 10 percent owner | G gift | B | 400,000 | nil | 1,114 | direct |
| 2026-03-04 | Gregory E. Abel | CEO, director | P purchase | A | 21 | 728,970.11 | 249 | indirect |
| 2026-03-17 | Warren E. Buffett | Chairman, 10 percent owner | G gift | A | 2 | n/a | 196,315 | direct |
| 2026-03-27 | Ajit Jain | VC, director | G gift | B | 22 | n/a | 330 | direct |
| 2026-05-06 | Michael J. O'Sullivan | GC | P purchase | B | 483 | 467.13 | 610 | indirect |
| 2026-05-06 | Michael J. O'Sullivan | GC | P purchase | B | 53 | 470.22 | 663 | indirect |
| 2026-05-14 | Charlotte Guyman | Director | G gift | B | 574 | nil | 2,888 | direct |
| 2026-05-18 | Warren E. Buffett | Chairman, 10 percent owner | C conversion | A | 25 | n/a | 196,290 | direct |
| 2026-05-18 | Warren E. Buffett | Chairman, 10 percent owner | C conversion | B | 37,500 | nil | 38,614 | direct |
| 2026-05-18 | Warren E. Buffett | Chairman, 10 percent owner | G gift | B | 18,646 | nil | 19,968 | direct |
| 2026-05-18 | Warren E. Buffett | Chairman, 10 percent owner | G gift | B | 18,646 | nil | 1,322 | direct |
| 2026-05-22 | Warren E. Buffett | Chairman, 10 percent owner | G gift | B | 160 | nil | 1,162 | direct |
| 2026-07-01 | Ajit Jain | VC, director | G gift | B | 3 | n/a | 327 | direct |
| 2026-07-14 | Warren E. Buffett | Chairman, 10 percent owner | C conversion | A | 8,000 | n/a | 188,290 | direct |
| 2026-07-14 | Warren E. Buffett | Chairman, 10 percent owner | C conversion | B | 12,000,000 | nil | 12,001,162 | direct |
| 2026-07-14 | Warren E. Buffett | Chairman, 10 percent owner | G gift | B | 9,000,000 | nil | 3,001,162 | direct |
| 2026-07-14 | Warren E. Buffett | Chairman, 10 percent owner | G gift | B | 1,000,000 | nil | 2,001,162 | direct |
| 2026-07-14 | Warren E. Buffett | Chairman, 10 percent owner | G gift | B | 1,000,000 | nil | 1,001,162 | direct |
| 2026-07-14 | Warren E. Buffett | Chairman, 10 percent owner | G gift | B | 1,000,000 | nil | 1,162 | direct |
| 2026-08-12 | Charles C. Chang | CFO | P purchase | A | 1 | 765,189.94 | 7 | indirect |
| 2026-08-12 | Charles C. Chang | CFO | P purchase | A | 1 | 765,184.18 | 8 | indirect |
| 2026-08-12 | Michael J. O'Sullivan | GC | P purchase | B | 45 | 510.64 | 708 | indirect |
| 2026-08-12 | Michael J. O'Sullivan | GC | P purchase | B | 400 | 512.52 | 1,108 | indirect |
| 2026-08-12 | Michael J. O'Sullivan | GC | P purchase | B | 43 | 513.61 | 1,151 | indirect |
Abel's 4 March 2026 purchase appears on the Form 4 as 18 separate lines at prices from $725,210.19 to $733,300.00 a Class A share. The $728,970.11 figure is the volume weighted average of those lines and is the only price in the table computed rather than read. O'Sullivan's three 12 August 2026 prices are weighted averages stated in footnotes F1 to F3, with quoted ranges of $510.58 to $510.68, $512.42 to $512.54 and $513.60 to $513.64. Jain's 15,000 share sale is stated in footnote F1 at an average of $500.99805, range $500.63 to $501.36, and the value calculation uses that unrounded figure. That sale disposed of stock held by Jain Foundation Inc., a nonprofit corporation, taking the foundation's holding from 122,308 to 107,308 Class B shares. Abel's, O'Sullivan's and Chang's purchases sit in a revocable trust, a living trust and a family limited liability company.

Eight of twelve months carry no open market insider transaction at all. The whole net position sits in four months: a sale of 15,000 shares in September 2025 and purchases of 31,500, 536 and 3,488 Class B equivalent shares in March, May and August 2026. Net for the window is 20,524 Class B equivalent shares acquired.
Table 31. Open market summary and buy to sell ratio
The ratio uses open market transaction codes P and S only. Gifts, conversions, option exercises, award vestings and tax withholding are excluded by construction, and none of the last three appears in either period. Class A converts at 1,500 Class B per Class A, the ratio stated in the form footnotes.
| Measure | Twelve months to 2 Sep 2026 | Twelve months to 2 Sep 2025 |
|---|---|---|
| Open market purchase lines | 8 | 0 |
| Open market sale lines | 1 | 3 |
| Purchases, Class B equivalent shares | 35,524 | 0 |
| Sales, Class B equivalent shares | 15,000 | 304,500 |
| Net, Class B equivalent shares | 20,524 | (304,500) |
| Purchases, USD | 17,339,364 | 0 |
| Sales, USD | 7,514,971 | 141,313,361 |
| Net, USD | 9,824,393 | (141,313,361) |
| Buy to sell ratio, shares | 2.37 | 0.00 |
| Buy to sell ratio, value | 2.31 | 0.00 |
Prior period sales comprise 200 Class A by Ajit Jain on 9 September 2024 at $695,417.65, accession 0001728451-24-000004; 1 Class A by Charlotte Guyman on 31 December 2024 at $678,064.00, accession 0000950170-25-001533; and 2 Class A by Meryl B. Witmer on 3 March 2025 at $775,883.30, accession 0000919574-25-001778.
Table 32. Open market purchases by buyer and implied Class B equivalent price
| Date | Buyer | Class | Shares | Class B equivalent | Value (USD) | Price per Class B equivalent (USD) |
|---|---|---|---|---|---|---|
| 2026-03-04 | Gregory E. Abel | A | 21 | 31,500 | 15,308,372 | 485.98 |
| 2026-05-06 | Michael J. O'Sullivan | B | 536 | 536 | 250,545 | 467.44 |
| 2026-08-12 | Michael J. O'Sullivan | B | 488 | 488 | 250,072 | 512.44 |
| 2026-08-12 | Charles C. Chang | A | 2 | 3,000 | 1,530,374 | 510.12 |
| Total | n/a | 35,524 | 17,339,364 | 488.10 |
Abel carries 89% of the purchased share count and 88% of the purchased value. The two new officers each committed roughly a quarter of a million dollars, and O'Sullivan repeated at a price 9.6% above his first purchase three months earlier. The single open market sale in the window cleared at $501.00 in September 2025, inside the $467 to $512 band of the purchases that followed.
Table 33. Abel open market purchase history since his 2018 Form 3
Eight Section 16 filings cover Abel's full history, starting with a Form 3 dated 9 January 2018. Three of them are purchase episodes. Class A holding is the indirect position after each episode.
| Date | Class A shares | Volume weighted price (USD) | Value (USD) | Class A holding after | Accession |
|---|---|---|---|---|---|
| 2022-09-29 | 168 | 406,729.53 | 68,330,561 | 173 | 0001081316-22-000036 through 0001081316-22-000039 |
| 2023-03-17 | 55 | 447,259.99 | 24,599,299 | 228 | 0001081316-23-000009 |
| 2026-03-04 | 21 | 728,970.11 | 15,308,372 | 249 | 0001193125-26-092556 |
The 2026 episode is the smallest of the three by share count and by value, and the highest by price. Abel has added to the position in each of the three episodes and has reported no open market sale of Berkshire stock.

Charitable gifts move 292 times the share volume of every open market transaction combined. Reading gift volume as selling pressure would invert the signal in this filing set: the shares move to donee foundations rather than to the market, and the Form 4 price column reads nil on 13 of the 18 gift lines and states no price on the other five. Buffett's Class A holding fell from 198,117 to 188,290 shares across the window, all of it through conversions that funded gifts plus one direct gift of 2 Class A shares. The opening figure of 198,117 is the 196,317 shares reported after the 10 November 2025 conversion plus the 1,800 shares that conversion used.
Table 34. Section 16 filers added in the window
| Filer | Role | Form 3 event date | Filed | Opening holding | Held |
|---|---|---|---|---|---|
| Michael J. O'Sullivan | Senior Vice President, General Counsel and Secretary | 2026-05-03 | 2026-05-05 | 127 Class B | indirect, by trust |
| Charles C. Chang | Senior Vice President and Chief Financial Officer | 2026-06-01 | 2026-06-10 | 6 Class A | indirect, by LLC |
Chang's Form 3 event date matches the 1 June 2026 effective date for the chief financial officer succession disclosed on 8 December 2025. Abel filed no Form 3 on becoming chief executive on 1 January 2026, having reported as a director since January 2018. Buffett's Form 4 reporting owner block carries an officer title through the 17 March 2026 filing and reports him as director and 10 percent owner from the 18 May 2026 filing onward.
Filing coverage
The insider trading endpoint returns 19 Forms 3, 4 and 5 for CIK 1067983 filed between 1 August 2025 and 3 September 2026. One of the 19, accession 0001728451-25-000006 dated 8 August 2025, falls before the window and is excluded, leaving 18 forms and 35 transaction lines. No Form 4 in the window sets the Rule 10b5-1 affirmation flag. No Form 5 was filed. The form-144 endpoint returns zero filings for this issuer, so no proposed sale of restricted stock is outstanding.
8 Risk Factors
Berkshire rewrote its succession risk and left everything else close to intact. Item 1A of the FY2025 10-K carries the same 13 risk headings as FY2024, none dropped and none added, across 2,870 words against 2,782, a rise of 3.2%. Eight headings changed in substance, five did not. One paragraph is wholly new, and it sits under railroad regulation. The single largest edit is the key person factor, where 46.4% of the FY2024 wording is gone: Gregory Abel is now named as the holder of capital allocation authority, Warren Buffett is named only as the person succeeded, and the board's reserved right to change its successor choice has been deleted. For the stock this is a disclosure catching up with a completed event rather than a new hazard. The forward looking risks that grew are reserve adequacy, rail network consolidation and artificial intelligence compliance.
No interim filing carried any of this. Part II Item 1A of the Q3 2025 10-Q, filed 3 November 2025, referred back to the FY2024 10-K without amendment, so every change below first reached investors on 2 March 2026.

Two headings show a changed word count with no changed risk. Economic conditions moved from "a prolonged period" to "prolonged time periods" and equity concentration lost one article. Both are wording, and both are shown apart from the substantive rewrites in Figure 26, because a changed sentence is not a changed risk.
8.1 What changed, factor by factor
Table 35. Item 1A change map, FY2025 10-K against FY2024 10-K, grouped by category
| Category | Risk factor as filed | Status | What changed |
|---|---|---|---|
| Key person | |||
| We are dependent on a few key people for our major investment and capital allocation decisions | Reworded | Abel replaces Buffett as the named holder of capital allocation authority, Adam Johnson enters as President of Consumer Products, Service and Retailing, and the board's stated ability to revisit its successor choice is removed. | |
| We need qualified personnel to manage and operate our various businesses | Unchanged | ||
| Investments | |||
| Investments are unusually concentrated in equity securities and fair values are subject to loss in value | Unchanged | ||
| Insurance underwriting | |||
| Our tolerance for underwriting risk assumed in our various insurance businesses may result in significant underwriting losses | Reworded | Litigation funding by third parties and larger jury verdicts are named as social inflation drivers, and stated unpaid losses move from $147.6bn to $151.8bn. | |
| Regulation | |||
| Regulatory changes may adversely impact our future operating results | Reworded | Artificial intelligence law joins data privacy, and both regimes are recast as enacted or under development rather than recently enacted. | |
| Changes in regulations and regulatory actions can adversely affect our operating results and our ability to allocate capital, insurance paragraph | Unchanged | ||
| Same heading, BNSF regulatory and litigation paragraph | Unchanged | ||
| Same heading, BNSF commodity and hazardous materials paragraph | Reworded | Policy risk widens from coal alone to any commodity BNSF hauls. | |
| Same heading, rail interchange and industry consolidation paragraph | New | A new paragraph on dependence on ports, passenger operators and connecting railroads, and on mergers among major rail carriers disrupting the network and the wider supply chain. | |
| Same heading, BHE regulation, wildfire and rate recovery paragraph | Unchanged | ||
| Same heading, BNSF and BHE capital investment paragraph | Reworded | BNSF and BHE are named directly, and funding risk is restated as restricted access rather than market disruption. | |
| Climate | |||
| Climate change and the regulation of greenhouse gas emissions may impact our businesses | Reworded | The BNSF and BHE share of direct emissions changes from more than 90% to the vast majority, withdrawing the quantification. | |
| General business | |||
| Cybersecurity risks could result in economic losses to our businesses and reputational damage | Reworded | Systems are described as already subject to cyber threats with continued exposure expected, and the loss list adds penalties, legal proceedings and confidential company information. | |
| Competition and technology may erode our business franchises and result in lower earnings | Reworded | Disruptive innovation and failure to enforce intellectual property join technological change as erosion channels. | |
| Geopolitical events could cause losses to our business and losses in the values of securities we own | Reworded | Sanctions join reduced sales and higher operating costs as a named channel of loss. | |
| Unfavorable general economic conditions may significantly reduce our operating earnings and impair our ability to access capital markets at a reasonable cost | Unchanged | ||
| Epidemics, pandemics or other similar outbreaks could hurt our operating businesses | Unchanged | ||
| Terrorist acts could hurt our operating businesses | Unchanged |
Thirteen headings and, within the regulated business heading, six paragraphs. Nothing in this table appears outside Item 1A of the two 10-K filings, accessions 0001193125-26-083899 and 0000950170-25-025210.
8.2 The succession rewrite
The FY2024 text made Berkshire's capital allocation a one man function and left the successor choice provisional. The FY2025 text makes it Abel's function and states no reservation. Both readings are the filer's own words.
Table 36. Key person risk factor, wording as filed
| Element | FY2024 10-K | FY2025 10-K |
|---|---|---|
| Who allocates capital | Warren E. Buffett, Chairman and Chief Executive Officer, age 94 | Gregory E. Abel, appointed by the board in May 2025 and effective 1 January 2026 |
| Who reports to that person | Abel, Vice Chairman noninsurance, and Ajit Jain, Vice Chairman insurance | Ajit Jain, Vice Chairman insurance, and Adam Johnson, President of Consumer Products, Service and Retailing |
| Age disclosed | Yes, 94 | No age disclosed |
| Successor commitment | "Berkshire's Board of Directors has agreed that Mr. Abel should replace Mr. Buffett" | No successor sentence; the succession has occurred |
| Board's freedom to revisit | "could alter its current view regarding a replacement for Mr. Buffett in the future" | Sentence deleted |
| Stated mitigant | "the Board's succession plan" | "the Board's succession plans" |
| Named exposure | "our key personnel, particularly Mr. Buffett" | "our key personnel", with no individual singled out |
Quoted text is verbatim from Item 1A of each filing.
Three consequences for the stock. The key person discount no longer attaches to one individual whose age the filing disclosed; it attaches to a bench of three named executives, which is a lower single point failure but a shorter track record. Berkshire has stopped telling investors it might change its mind about the successor, which removes a piece of optionality the FY2024 language preserved. Item 1A does not mention that Buffett continues as Chairman; that fact is in the 8-K of 8 May 2025, so the risk section now understates the continuity that exists.
The FY2025 wording is also thinner than the event it describes. The 8 December 2025 announcement covered five changes, set out in chapter 5, and none of them reaches Item 1A. The risk factor names three executives out of a turnover of at least seven roles in eight months.
8.3 The one new risk
The rail interchange and consolidation paragraph is the only wholly new text in Item 1A. It does two things. It concedes that BNSF's service quality depends on ports, passenger operators and connecting railroads that Berkshire does not control. It then adds that mergers among major rail carriers may disrupt the network and the wider supply chain, and may hit BNSF's operating results, financial condition and liquidity.
Berkshire does not name a transaction. Union Pacific and Norfolk Southern signed a merger agreement on 28 July 2025, disclosed by both filers on Form 8-K Item 1.01 the following day. The timing lines up, but the attribution is inference. What the filing does establish is that Berkshire now treats a competitor's structure, rather than its own conduct, as a source of loss at BNSF. That is a new category of railroad risk for this issuer.
8.4 Reserve risk, quantified
Estimated unpaid losses on property and casualty contracts rose 2.8% to $151.8bn, and the language around them hardened. FY2024 cited "new or expanded theories of liability and increased frequency of litigation". FY2025 adds litigation funding by third parties and "juries awarding increasingly larger verdicts" as named drivers. On the FY2025 balance, a 1% reserve shortfall is $1.5bn pretax, which is the sensitivity Berkshire is pointing at when it says a small percentage increase can materially reduce reported earnings.
The catastrophe appetite did not move. Berkshire still avoids policy groups from which a single event could cost more than $15bn pretax. Against shareholders' equity that grew 10.5% to $717.4bn, the same dollar tolerance now represents 2.09% of book, down from 2.31%. The stated risk appetite is unchanged in dollars and smaller in relation to the balance sheet.

Equity concentration works the other way. The risk factor text is unchanged, but the exposure it describes fell: the five largest holdings, American Express, Apple, Bank of America, Coca-Cola and Chevron in both years, dropped from 71% to 65% of a $297.8bn equity portfolio. That is still $193.6bn in five names, equal to 27.0% of Berkshire shareholders' equity. Static risk language over a moving exposure is the normal state of Item 1A.
8.5 Disclosure that was withdrawn
One number left Item 1A. FY2024 stated that BNSF and BHE combined represent more than 90% of Berkshire's direct emissions. FY2025 says the vast majority. Nothing elsewhere in the 10-K restores the figure, so the climate exposure at the two capital intensive subsidiaries is now qualitative, and investors who track transition risk lose their only quantified anchor in the filing. Buffett's age also disappears, which is consistent with him no longer being the named allocator.
8.6 What could not be verified
Four items could not be verified from the filings. Berkshire names no counterparty behind mergers among major rail carriers, so the link to the Union Pacific and Norfolk Southern agreement is inference from timing. The withdrawn greenhouse gas percentage cannot be recomputed, because the 10-K reports no emissions figure. Item 1A does not state that Buffett remains Chairman, so that comes from the 8-K of 8 May 2025. No 10-Q amended Item 1A during 2025, so no change can be dated earlier than the 10-K filing of 2 March 2026.
9 Stock Price, Scenarios & Sensitivity
BRK.B last traded at $506.90 on 2 September 2026, 6.1% below the weekly closing high of $539.80 set on 28 April 2025, five days before Warren Buffett told the annual meeting that Greg Abel would take over. The stock has gone sideways for sixteen months while book value a share rose from $301.00 at the end of 2024 to $348.26 at 30 June 2026, and price to book fell from 1.51x to 1.46x. Berkshire bought $4,762m of its own stock in the first half of 2026, the Class B portion at a weighted average of $486.00 a share, 1.40 times the $348.26 book value at 30 June 2026.
The stock is unusual in one respect that governs every scenario below. Investments carried on the balance sheet, cash and Treasury Bills and fixed maturity securities and listed equities, come to $326.33 a share at 30 June 2026, or 64.4% of the price. The remaining $180.57 a share buys operating businesses that earned $14.82 a share after tax in 2025, excluding insurance investment income. The market therefore pays 12.2 times after tax operating earnings for the operating half of Berkshire. The three year outcome turns on that multiple, on the operating margin, and on what the equity portfolio does.

The 52 week range is $464.36 to $537.74. The stock is up 0.85% year to date. Thirty day historical volatility is 15.6% annualised.

Figure 29 sets repurchase spend against the price to book multiple at each reporting date. Berkshire spent $27.1bn on repurchases in 2021, with the stock at 1.32 times book at that year end, cut to $2.9bn in 2024 at 1.51 times, spent nothing in 2025 at 1.49 times, and restarted in March 2026 at $486.92 a Class B share, 1.46 times the $332.55 book value at 31 December 2025. The one hard constraint is that Berkshire will not repurchase if the purchase reduces consolidated cash, cash equivalents and Treasury Bills below $30,000m. That balance was $365,514m at 30 June 2026, so the constraint is not binding and the only real test is the price against intrinsic value, judged by the Chief Executive Officer after consultation with the Chairman. The 2026 restart is the clearest signal management has given on where it thinks intrinsic value sits. The prices paid were $486.92 in March, $476.01 in May and $487.98 in June for Class B, and $729,701.17, $716,231.37 and $733,775.06 for Class A.
The price to book figures pair the market price at each date with the book value at the preceding reporting date. The 2026 H1 point pairs the last trade of $506.90 on 2 September 2026 with book value at 30 June 2026.
The valuation frame
The frame has two columns, which is what Berkshire's own reporting supports.
Column one is investments at balance sheet value: cash and equivalents in insurance and other $35,096m, Treasury Bills $324,905m, fixed maturity securities $17,034m and equity securities $323,779m, together $700,814m at 30 June 2026. Equity method investments of $19,948m are excluded because their earnings sit inside the operating column under other.
Column two is operating earnings after tax excluding insurance investment income, capitalised at a multiple. Insurance investment income is left out because the assets that produce it already sit in column one. Acquisitions consume cash in column one and appear in the revenue growth and margin assumptions in column two. Nothing is counted twice.
Class B equivalent shares outstanding are 2,147,538,984 at 30 June 2026, down 9,796,155 or 0.45% since 31 December 2025.
Table 37. Three year scenario inputs to 31 December 2029
Every input is a number, so each case can be rebuilt from this table alone. The base case is an estimate under the stated assumptions, and no case is a price target.
| Input, 2027 to 2029 | Worst | Base | Best |
|---|---|---|---|
| Revenue growth a year | 0.0% | 4.0% | 6.5% |
| Operating pretax margin in 2029 | 8.5% | 11.2% | 12.5% |
| Tax rate on operating businesses | 15.2% | 15.2% | 15.2% |
| Yield on cash and Treasury Bills | 1.50% | 3.25% | 4.00% |
| Equity portfolio total return a year | (8.0)% | 6.0% | 9.0% |
| Capital deployed a year, USD m | 8,000 | 18,000 | 30,000 |
| Of which repurchases, USD m | 8,000 | 8,000 | 10,000 |
| Exit multiple on operating earnings | 8.0x | 12.0x | 15.0x |
Table 38. Three year scenario outputs at 31 December 2029
| Output at 31 December 2029 | Worst | Base | Best |
|---|---|---|---|
| Revenue, USD m | 398,436 | 448,186 | 481,291 |
| Operating pretax earnings, USD m | 33,867 | 50,197 | 60,161 |
| Operating earnings after tax, USD m | 28,715 | 42,560 | 51,009 |
| Equity portfolio, USD m | 241,828 | 397,026 | 437,765 |
| Cash, Treasury Bills and fixed maturities, USD m | 447,583 | 457,526 | 439,050 |
| Investments, USD m | 689,410 | 854,552 | 876,815 |
| Class B equivalent shares, millions | 2,092 | 2,092 | 2,078 |
| Investments a share, USD | 329 | 408 | 422 |
| Operating earnings a share, USD | 13.72 | 20.34 | 24.54 |
| Value a Class B share, USD | 439 | 653 | 790 |
| Return a year from $506.90 | (4.2)% | 7.9% | 14.3% |
Every case starts from the same FY2026 estimate: revenue of $398,436m, built from actual first half revenue of $195,483m plus second half 2025 revenue grown at the 7.3% first half rate; operating earnings after tax of $49,759m, of which $37,768m is operating businesses and $11,991m is insurance investment income; and an operating pretax margin of 11.2%. The roll runs 3.5 years from the 30 June 2026 balance sheet. Repurchases are executed at $506.90 in every case, which understates the share count reduction if the price falls. Deferred tax on unrealised equity gains of $217,258m is not modelled because nothing is sold.

The investments column alone is $329 a share in the worst case, 65% of today's price. That is the structural reason the downside case still only loses 4.2% a year: two thirds of the stock is a marked to market pile of Treasury Bills and Level 1 equities, and Treasury Bills do not fall.
Table 39. What the best case requires, and why it is possible
| Requirement | The number | Why it is credible | Why it may not happen |
|---|---|---|---|
| Capital deployed rises to $30,000m a year | OxyChem closed 2 January 2026 for $9,400m and Taylor Morrison closed 24 July 2026 for $6,800m, $16,200m in seven months | The capacity is there: $365,514m of cash and Treasury Bills against a $30,000m floor, and Berkshire bought $39,405m of equities against $27,780m sold in the first half, a net $11,625m after being a net seller of $4,500m a year earlier | Berkshire paid $396m for acquisitions in 2024 and $1,074m in 2025, so the $16,200m of seven month 2026 spend has no precedent in the two prior years |
| Operating pretax margin reaches 12.5% | Core pretax margin was 15.1% in the first half of 2026 against 13.5% a year earlier | Manufacturing, service and retailing earned $7,669m after tax in the half against $6,661m, and OxyChem adds a full year from 2027 | OxyChem is capital intensive: $7,000m of the $10,700m of assets acquired is property, plant and equipment. Chemical earnings track commodity spreads |
| Exit multiple of 15.0x | The market pays 12.2 times today | The multiple is the largest single lever in the model, worth $122 a share across the tested range | A multiple is a market judgement. Nothing in the filings sets it |
| Equity portfolio compounds at 9.0% a year | $323,779m at 30 June 2026, 97.0% of it Level 1 | The column marks to market with no lag and no valuation judgement | The same feature works in reverse. A 25% drawdown removes $80,945m, or $37.69 a share |
| Repurchases of $10,000m a year | $4,762m in the first half of 2026, the Class B portion at $486.00 a share against book of $348.26 | The programme has no size limit and the cash floor is $335,514m away | Repurchases stop the moment the price rises above what management judges intrinsic value to be. That is what happened through 2025 |
Table 40. Core assumptions and what drives demand
Operating earnings after tax by source, USD millions, from the first half management discussion tables.
| Earnings source | H1 2026 | H1 2025 | Change | What moves it |
|---|---|---|---|---|
| Insurance underwriting | 3,448 | 3,328 | 3.6% | Premium rates against claim frequency and severity. Float was $176bn at the end of 2025 |
| Insurance investment income | 5,738 | 6,260 | (8.3)% | The short rate on $324,905m of Treasury Bills. 100 basis points is $2,567m after tax, or $1.20 a share a year |
| BNSF | 2,935 | 2,680 | 9.5% | Carload volumes and rate per car, which track industrial production and intermodal imports |
| Berkshire Hathaway Energy | 2,005 | 1,799 | 11.5% | Regulated rate base, allowed returns and tax credits |
| Manufacturing, service and retailing | 7,669 | 6,661 | 15.1% | United States industrial and consumer demand |
| Other | 2,534 | 73 | n/a | Noncontrolled businesses and corporate items. This line is volatile and is held at its 2025 second half level in the FY2026 estimate |
| Operating earnings | 24,329 | 20,801 | 17.0% |
OxyChem consolidates from 2 January 2026 and Taylor Morrison from 24 July 2026. Neither is separately reported yet, so neither can be isolated inside the lines above.
Two positions carry their own scheduled events. The Occidental Petroleum preferred stock has a liquidation value of $8,500m and pays 8%, and Occidental may redeem it from 2029 at 105% of liquidation value, which removes $680m of annual pretax income inside the scenario window. Berkshire also holds warrants over 83.9m Occidental shares at $59.59. The American Express holding is 151.6m shares, 22.5% of that company.

Table 41. One way sensitivity, value a Class B share at 31 December 2029 (USD)
| Input | Low | Value at low | Base | Value at base | High | Value at high | Range |
|---|---|---|---|---|---|---|---|
| Exit multiple on operating earnings | 9.0x | 591 | 12.0x | 653 | 15.0x | 714 | 122 |
| Operating pretax margin 2029 | 9.7% | 615 | 11.2% | 653 | 12.7% | 691 | 76 |
| Equity portfolio return a year | 0.0% | 618 | 6.0% | 653 | 12.0% | 693 | 75 |
| Revenue growth a year | 1.0% | 629 | 4.0% | 653 | 7.0% | 677 | 48 |
| Capital deployed a year, USD m | 6,000 | 673 | 18,000 | 653 | 30,000 | 632 | 40 |
| Yield on cash and Treasury Bills | 1.75% | 645 | 3.25% | 653 | 4.75% | 661 | 16 |
Capital deployed runs the other way from the rest. In this frame deployment is a cash outflow with revenue growth held constant, so the row measures the cost of writing the cheque, and the return on the cheque appears in the revenue growth and margin rows. Deploying $30,000m a year and holding growth at 4.0% is the assumption of a buyer who overpays.

The two inputs that move the outcome most are the exit multiple and the 2029 operating pretax margin. The grid spans $562 to $760, a range of $198 a share, against a base case of $653 and a price of $506.90. Every cell in the grid sits above the current price, which is a statement about the frame rather than about the stock: the investments column of $408 a share in the base case is fixed across the grid, and only the $244 a share of capitalised operating earnings varies.
What would break the base case
The base case of $653 a share and 7.9% a year rests on four things that can each be falsified.
Multiple compression alone takes it apart. Holding every operating assumption, an exit multiple of 8.0x rather than 12.0x gives $571 a share and a return of 3.7% a year. Nothing in the filings fixes the multiple.
An equity drawdown does most of the rest. The portfolio was $323,779m at 30 June 2026 against a cost of $106,521m, so $217,258m of the position is unrealised gain. A 25% fall removes $80,945m, $37.69 a share, and no accounting treatment softens it because 97.0% of the portfolio is Level 1.
Underwriting can turn. Pretax underwriting earnings were $9,460m in 2025, $11,405m in 2024 and a loss of $22m in 2022. The base case holds the margin flat. A repeat of 2022 removes $9,482m of pretax earnings, $7,275m after tax at the 23.3% rate underwriting carried in 2025, $3.39 a share, and $41 a share at 12.0x.
A large writedown can appear without warning. The 2025 accounts carry an $8,255m after tax impairment inside net earnings but outside operating earnings, and the equity method line swung from $1,841m in 2024 to a loss of $9,590m in 2025. Kraft Heinz accounted for $4,796m of equity method loss in the first half of 2025 alone; the same line was a $403m gain in the first half of 2026.
An alternative frame gives a lower number. An investor who marks the investments column at fair value rather than balance sheet value, or who applies a holding company discount for the drag of Treasury Bills earning a short rate inside a corporate tax wrapper, will get less than $653 from the same operating assumptions. The frame here takes no discount and no premium.
The Class A share count is the only figure in this chapter reconstructed rather than read: the quarterly repurchase tables print Class A average prices but not Class A share counts, so the 511 Class A shares come from the movement in Class A treasury shares, and the price implied by the residual value falls inside the range of prices Berkshire disclosed paying.
Class A shares outstanding fell 14,734 in the first half while only 511 were repurchased. Class A shares issued fell 14,223 and Class B shares issued rose 21,334,500, which is exactly 14,223 multiplied by 1,500. The 14,223 gap is conversion of Class A into Class B.
Sources
SEC filings in this analysis are retrieved through the SEC-API.io MCP server. Berkshire Hathaway Inc., CIK 1067983.
Filings cited in this report
| Filing | Period or event | Accession number |
|---|---|---|
| 10-K | FY2025, filed 2026-03-02 | 0001193125-26-083899 |
| 10-K | FY2024 | 0000950170-25-025210 |
| 10-K | FY2023 | 0000950170-24-019719 |
| 10-K | FY2022 | 0000950170-23-004451 |
| 10-K | FY2021 | 0001564590-22-007322 |
| 10-Q | Q2 2026, filed 2026-08-10 | 0001193125-26-341032 |
| 10-Q | Q1 2026, filed 2026-05-04 | 0001193125-26-202243 |
| 10-Q | Q3 2025 | 0001193125-25-261548 |
| 10-Q | Q2 2025 | 0000950170-25-101578 |
| 10-Q | Q1 2025 | 0000950170-25-063112 |
| 10-Q | Q3 2024 | 0000950170-24-120241 |
| 10-Q | Q2 2024 | 0000950170-24-090305 |
| 10-Q | Q1 2024 | 0000950170-24-053185 |
| 10-Q | Q3 2022 | 0000950170-22-022287 |
| 10-Q | Q2 2022 | 0001564590-22-028282 |
| 10-Q | Q1 2022 | 0001564590-22-016907 |
| 8-K, Exhibit 99.1 | Q4 and full year 2025 earnings release | 0001193125-26-085801 |
| 8-K, Exhibit 99.1 | Q1 2026 earnings release and annual meeting items | 0001193125-26-212148 |
| 8-K, Exhibit 99.1 | Q2 2026 earnings release | 0001193125-26-344495 |
| 8-K, Exhibit 99.1 | Q3 2025 earnings release | 0001193125-25-262260 |
| 8-K, Exhibit 99.1 | Leadership appointments, 2025-12-08 | 0001193125-25-314935 |
| 8-K, Item 8.01 | Repurchase programme restart, 2026-03-04 | 0001193125-26-092557 |
| 8-K/A, Item 5.02 | Chief executive appointment and salary | 0001193125-26-004727 |
| 8-K, Item 5.03 | Bylaws amended and restated, 2025-09-30 | 0001193125-25-229405 |
| 8-K, Item 8.01 | Yen senior notes, November 2025 | 0001193125-25-290864 |
| 8-K, Item 8.01 | Yen senior notes, April 2026 | 0001193125-26-159326 |
| 424(b)(5) | Registration fee table, November 2025 notes | 0001193125-25-286108 |
| 424(b)(5) | Registration fee table, April 2026 notes | 0001193125-26-154274 |
| DEF 14A | Annual meeting 2026, filed 2026-03-13 | 0001193125-26-106253 |
Schedule 13D and 13G accessions are listed in Table 27. Forms 3, 4 and 5 accessions are cited in chapter 7. The nine peer 10-K filings and their accession numbers are in Table 18.
Sector figures in Table 17 come from outside the filings and are credited in that table:
- AM Best, Best's Rankings: 2025 US Property/Casualty NPW Rise 5%
- Verisk and APCIA, Strong 2025 Underwriting Income Masks Persistent Property/Casualty Insurance Pressures
- Guy Carpenter rate on line index, 1 January 2026 renewals, reported by Artemis
Share prices, the 52 week range and the volatility figure are market data and carry no named provider. No market derived figure is sourced to SEC-API.io. Annual meeting remarks of 2 May 2026 are reported speech and are credited to CNBC, "Warren Buffett Watch", 3 May 2026; they sit outside the SEC-API.io credit.
Figures as read from filings sit in each chapter's model.py, with the accession number for every figure recorded in that file. Ratios and scenarios are computed in each chapter's analysis.py and rerun with the model.
Final check. This analysis was reviewed on 2 September 2026. Thirty two figures and forty one tables are titled and numbered in reading order with no gaps, and the filing index above is a source list rather than a numbered table. Two discrepancies are carried forward unadjusted and are stated where they arise: the OxyChem purchase price of $9.5bn in the FY2025 Form 10-K against $9.4bn in the Q2 2026 Form 10-Q, a post closing adjustment recorded after the 10-K was filed; and the proxy percentages of Class B held by Vanguard and BlackRock, 11.4% and approximately 8.8%, which reproduce only on the 1,378,545,639 Class B shares outstanding at 21 July 2025 and not on the 4 March 2026 record date count used in Tables 25 and 26.
Disclaimer
This document is not financial advice. Each scenario is a range under stated assumptions. No scenario is a price target or a recommendation.