Walmart Inc. (WMT), Financial Analysis
Insights derived from analysing SEC filings. Independent analysis of Walmart Inc. common stock, not a publication of the SEC. Figures are read from the fiscal 2024, fiscal 2025 and fiscal 2026 Forms 10-K, the fiscal 2027 Forms 10-Q, the Forms 8-K and their earnings exhibits, the DEF 14A, Schedules 13D and 13G, Forms 13F, Forms 3, 4, 5 and 144, and the equivalent filings of seven peers. Accession numbers for every filing used appear in Table 34.
Fiscal years end 31 January, so FY2026 is the year to 31 January 2026. Amounts are in $ millions unless stated. Share prices are the last trade recorded on 2 September 2026 and come from a market data feed.
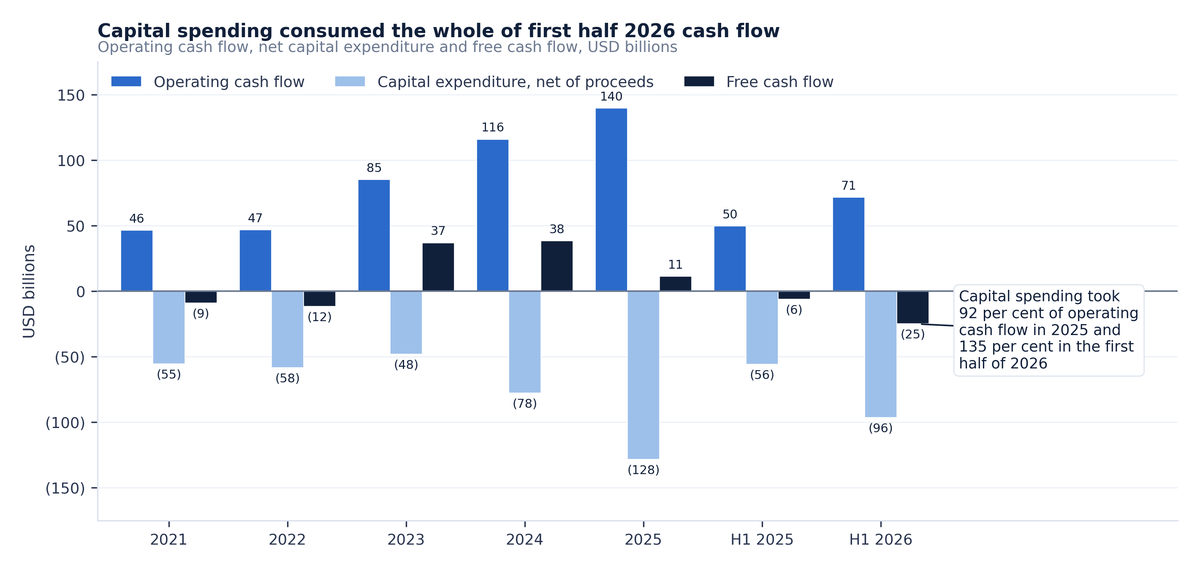
Three findings run through the nine chapters and are best read together. FY2026 GAAP diluted EPS rose 13.3% while adjusted EPS rose 5.2%, and the whole of the gap is a $2,869m swing in the marks on equity and other investments. Free cash flow of $14,923m no longer covers the $15,595m paid out in dividends and buybacks, a cover of 0.96 times against 1.70 times in FY2024. And the raised FY2027 guide implies second half adjusted operating income growth of 0.8% to 3.7% against 13.6% delivered in the first half, because a $2.9bn tariff refund received in the July quarter is being reinvested in price. At $106.54 the stock trades on 37.6 times the midpoint of the FY2027 adjusted earnings guide.
1 Revenue & Business Model
Walmart is a merchandise business with a small, fast growing income stream bolted to it. In fiscal 2026 net sales of $706.4bn were 99.1% of total revenues of $713.2bn. The residual $6.8bn of membership and other income was 0.9% of revenue and 22.6% of consolidated operating income of $29.8bn. That asymmetry is the investment argument for the stock: revenue compounds at 5.6% a year and looks like a mature retailer, while the profit mix moves toward membership, advertising and marketplace income that the filings barely size.
Three shifts define the five years to fiscal 2026. Digital sales went from 12.9% to 21.3% of net sales. Inside Walmart U.S., general merchandise fell from 32.0% to 23.8% of segment net sales while health and wellness rose from 10.9% to 14.4%. Membership fees compounded at 18.9% against 5.6% for net sales. Geography barely moved: revenue earned outside the United States rose from 17.9% to 18.5% of total revenues across five years.
Walmart serves approximately 280 million customers a week through 10,955 retail units in 19 countries, staffed by approximately 2.1 million associates and supplied by 371 distribution facilities. Pricing is everyday low price supported by everyday low cost. The gross profit rate was 24.21% of net sales in fiscal 2026 against 23.73% in fiscal 2024.
How the revenue is built
Table 1. Revenue build, fiscal 2022 to fiscal 2026 ($m)
| FY2022 | FY2023 | FY2024 | FY2025 | FY2026 | CAGR | |
|---|---|---|---|---|---|---|
| Net sales | 567,762 | 605,881 | 642,637 | 674,538 | 706,413 | 5.6% |
| Membership and other income | 4,992 | 5,408 | 5,488 | 6,447 | 6,750 | 7.8% |
| Total revenues | 572,754 | 611,289 | 648,125 | 680,985 | 713,163 | 5.6% |
| Of which membership fees | 2,200 | 2,600 | 3,100 | 3,800 | 4,400 | 18.9% |
| Membership fees, share of membership and other income | 44.1% | 48.1% | 56.5% | 58.9% | 65.2% | n/a |
| Net sales, share of total revenues | 99.13% | 99.12% | 99.15% | 99.05% | 99.05% | n/a |
Membership fee income is disclosed only to one decimal place in billions, so the fee series above carries that precision and no more. Walmart names advertising, marketplace and fulfilment services, financial services and healthcare as the offerings that expand the ecosystem, and attributes part of the gross margin gain to them, but discloses revenue for none of them. Advertising net sales sit inside net sales and inside the eCommerce measure. Membership fees are the only ecosystem stream disclosed in dollars.
Revenue by region

United States revenue grew at a 5.4% five year rate to $581.2bn and revenue earned outside the United States at 6.5% to $132.0bn. The gap is narrower than the underlying volume gap because currency translation removed $2.8bn of net sales in fiscal 2026 and $3.2bn in fiscal 2025.
Walmart's geographic disclosure runs to two lines, United States and outside the United States, with no hedging or reconciling item between them. Country detail exists only one level down, as net sales inside the Walmart International segment, and only for three named markets plus a residual.
Table 2. Walmart International net sales by market ($m)
| FY2022 | FY2023 | FY2024 | FY2025 | FY2026 | CAGR | |
|---|---|---|---|---|---|---|
| Mexico and Central America | 35,964 | 40,496 | 49,726 | 51,970 | 52,492 | 9.9% |
| Canada | 21,773 | 22,300 | 22,639 | 23,035 | 23,724 | 2.2% |
| China | 13,852 | 14,711 | 17,011 | 19,975 | 24,623 | 15.5% |
| United Kingdom | 3,811 | 0 | 0 | 0 | 0 | n/a |
| Other | 25,559 | 23,476 | 25,265 | 26,905 | 29,584 | 3.7% |
| Walmart International net sales | 100,959 | 100,983 | 114,641 | 121,885 | 130,423 | 6.6% |

China is the fastest growing named market at a 15.5% five year rate and passed Canada in fiscal 2026. The residual "Other" line was $29.6bn, larger than Canada, and covers Chile, India and eight African countries without a country split. India is where Flipkart and PhonePe sit, so the largest single unknown in Walmart's geographic disclosure is also the one carrying its highest growth digital assets.
Revenue by segment

Three reportable segments, unchanged in number across all five years. Walmart U.S. holds 68.4% of consolidated net sales against 69.3% in fiscal 2022, Walmart International 18.5% against 17.8%, and Sam's Club U.S. 13.2% against 13.0%. The segment named Sam's Club in the fiscal 2024 filing is named Sam's Club U.S. in the two filings since, with identical reported net sales in the overlapping years, so the change is a caption and not a restatement.
Table 3. Segment profit build, fiscal 2026 ($m)
| Walmart U.S. | Walmart International | Sam's Club U.S. | Corporate and reconciling items | Consolidated | |
|---|---|---|---|---|---|
| Net sales | 482,975 | 130,423 | 93,015 | n/a | 706,413 |
| Gross profit | 132,615 | 27,847 | 10,556 | n/a | 171,018 |
| Operating expenses | 110,081 | 24,309 | 10,639 | n/a | 147,943 |
| Merchandise result | 22,534 | 3,538 | (83) | (2,914) | 23,075 |
| Membership and other income | 2,624 | 1,565 | 2,525 | 36 | 6,750 |
| Segment operating income | 25,158 | 5,103 | 2,442 | (2,878) | 29,825 |
| Operating margin on net sales | 5.2% | 3.9% | 2.6% | n/a | 4.2% |
Walmart does not disclose gross profit or operating expenses for corporate and reconciling items, so that column's merchandise result of (2,914) is the balancing figure between the three segments and the consolidated line rather than a reported number.
Table 4. Merchandise result before membership and other income ($m)
| FY2024 | FY2025 | FY2026 | |
|---|---|---|---|
| Walmart U.S. | 20,169 | 21,288 | 22,534 |
| Walmart International | 3,501 | 4,023 | 3,538 |
| Sam's Club U.S. | 141 | 81 | (83) |
Sam's Club U.S. is the clearest case of the model. In fiscal 2026 its merchandise operations lost $83m before membership and other income of $2,525m produced segment operating income of $2,442m. The merchandise result has fallen for three straight years, from $141m to $81m to a loss. A club membership costs $50 a year and a Plus membership $110, and that fee line now carries the entire segment profit.
Walmart International's reported operating income fell 7.2% to $5,103m. Excluding the $0.7bn charge for PhonePe's modification of share based payment arrangements ahead of a possible public offering, core operating income was about $5,803m, up 5.5%. The charge is disclosed to one decimal place, so the core figure is approximate to that precision. Both readings are defensible: the charge is real cash compensation cost, and it is also nonrecurring by its own description.
Revenue by product segment

Walmart U.S. runs three strategic merchandise units plus a residual. Grocery grew at 6.9% a year to $285.5bn and holds 59.1% of segment net sales. Health and wellness was the fastest of the three strategic merchandise units at 12.9% a year to $69.5bn, lifting its share from 10.9% to 14.4%. General merchandise shrank at a (2.2%) rate to $115.1bn and lost 8.2 points of segment mix. The Other categories line, which holds fuel, financial services and related products, grew 23.2% a year off a small base to $12.9bn.
The mix is moving toward low ticket, high frequency, pharmacy weighted volume and away from discretionary general merchandise. That supports traffic and supports the advertising and membership businesses that monetise traffic, and it works against average gross margin per transaction.
Table 5. Sam's Club U.S. net sales by merchandise category, current presentation ($m)
| FY2024 | FY2025 | FY2026 | |
|---|---|---|---|
| Grocery | 57,565 | 61,253 | 64,706 |
| Fuel and other | 13,707 | 12,960 | 11,570 |
| General merchandise | 10,947 | 11,215 | 11,549 |
| Health and wellness | 3,960 | 4,810 | 5,190 |
| Sam's Club U.S. net sales | 86,179 | 90,238 | 93,015 |
Sam's Club U.S. category detail cannot be shown across five years, because Walmart recast the split twice in three annual filings. Fiscal 2024 grocery reads 56,449 in the fiscal 2024 filing, 56,455 in the fiscal 2025 filing and 57,565 in the fiscal 2026 filing; fiscal 2024 health and wellness fell by (1,045) between the last two presentations. The five caption basis of the fiscal 2024 filing became a four caption basis in fiscal 2025. Each presentation still totals the same segment net sales of 86,179 for that year, so this is a redrawing of category boundaries and not a change in reported revenue. Table 5 uses the current basis only, and the fuel decline in it is a price effect: lower fuel prices cut Sam's Club comparable sales by 1.9% in fiscal 2026 and 1.5% in fiscal 2025.
The digital channel

eCommerce net sales reached $150.4bn, a 19.7% five year rate against 5.6% for the group, taking the digital share of net sales from 12.9% to 21.3%. Walmart U.S. contributed $99.6bn of that, International $35.8bn and Sam's Club U.S. $15.0bn. Digital sales added 4.3 points to Walmart U.S. comparable sales of 4.3% in fiscal 2026 and 3.3 points to Sam's Club U.S. comparable sales of 2.9%, so the whole of comparable growth in both United States segments came from the digital channel.
Walmart's eCommerce definition is wide. It counts every sale initiated digitally, including store fulfilled pickup and delivery and including advertising net sales. Walmart attributes the growth primarily to store fulfilled pickup and delivery, so the store estate is the fulfilment network. Pickup or delivery runs from over 8,400 locations globally.
What this means for the stock
Revenue growth is a 5% to 6% business and has been for five years. The variable is mix. Membership fees, advertising and marketplace fees carry higher incremental margin than merchandise, and their growth is what turned a 23.73% gross profit rate in fiscal 2024 into 24.21% in fiscal 2026 while the merchandise mix moved the other way. The investor cannot size that shift directly, because Walmart discloses membership fees and nothing else. Sam's Club U.S. is the visible proxy, and there the fee line already exceeds segment operating income.
2 Financial Analysis & Ratios
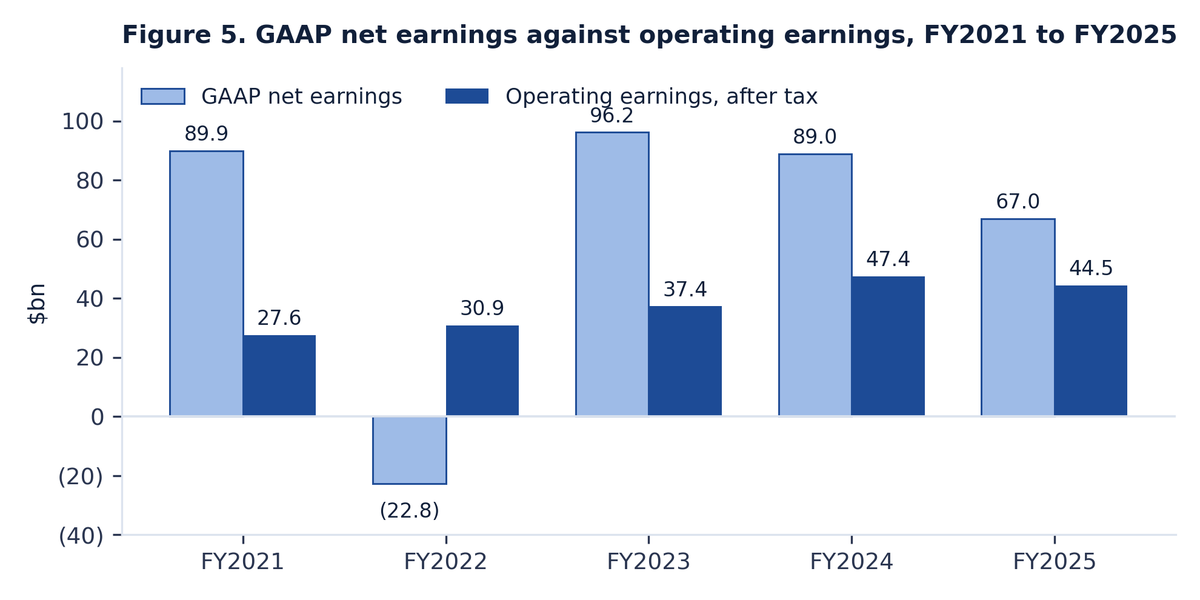
Total revenues rose 4.7% to $713,163m and adjusted operating income rose 5.0% to $30,982m, while GAAP diluted EPS rose 13.3% to $2.73 against adjusted EPS of $2.64, up 5.2%. The whole of that gap is a $2,869m swing in the marks on equity and other investments, from a $794m loss in FY2025 to a $2,075m gain in FY2026. Operating margin fell 13 bps to 4.18%. For the equity the durable line is the adjusted one: $2.64 delivered, $2.80 to $2.87 guided for FY2027.
Two structural facts sit under the FY2026 result. Capital expenditure reached 3.7% of revenue against 2.3% four years earlier, and return on invested capital fell to 16.1% from 17.2%. Free cash flow of $14,923m no longer covers the $15,595m paid out in dividends and buybacks, a cover of 0.96 times against 1.70 times in FY2024.
What changed in FY2026
Table 6. Consolidated results, FY2026 against FY2025 ($m except per share)
| FY2025 | FY2026 | Change | Change % | |
|---|---|---|---|---|
| Net sales | 674,538 | 706,413 | 31,875 | 4.7% |
| Membership and other income | 6,447 | 6,750 | 303 | 4.7% |
| Total revenues | 680,985 | 713,163 | 32,178 | 4.7% |
| Cost of sales | 511,753 | 535,395 | 23,642 | 4.6% |
| Gross profit | 162,785 | 171,018 | 8,233 | 5.1% |
| Selling, general and administrative expenses | 139,884 | 147,943 | 8,059 | 5.8% |
| Operating income | 29,348 | 29,825 | 477 | 1.6% |
| Adjusted operating income | 29,504 | 30,982 | 1,478 | 5.0% |
| Interest, net | (2,245) | (2,431) | (186) | (8.3%) |
| Other gains and losses | (794) | 2,075 | 2,869 | n/a |
| Income before income taxes | 26,309 | 29,469 | 3,160 | 12.0% |
| Provision for income taxes | 6,152 | 7,199 | 1,047 | 17.0% |
| Consolidated net income | 20,157 | 22,270 | 2,113 | 10.5% |
| Net income attributable to Walmart | 19,436 | 21,893 | 2,457 | 12.6% |
| GAAP diluted EPS | $2.41 | $2.73 | $0.32 | 13.3% |
| Adjusted EPS | $2.51 | $2.64 | $0.13 | 5.2% |
| Diluted weighted average shares (m) | 8,081 | 8,022 | (59) | (0.7%) |
| Operating cash flow | 36,443 | 41,565 | 5,122 | 14.1% |
| Capital expenditure | 23,783 | 26,642 | 2,859 | 12.0% |
| Free cash flow | 12,660 | 14,923 | 2,263 | 17.9% |
| Dividends paid | 6,688 | 7,507 | 819 | 12.2% |
| Share repurchases | 4,494 | 8,088 | 3,594 | 80.0% |
| Gross margin, % of net sales | 24.13% | 24.21% | 8 bps | |
| SG&A rate, % of net sales | 20.74% | 20.94% | 21 bps | |
| Operating margin, % of revenue | 4.31% | 4.18% | (13 bps) | |
| Adjusted operating margin | 4.33% | 4.34% | 1 bps | |
| Net margin | 2.85% | 3.07% | 22 bps | |
| Effective tax rate | 23.38% | 24.43% | 105 bps |
Walmart reports no fourth quarter as a discrete period in any audited filing, so every fourth quarter amount in this report is read from the unaudited Exhibit 99.1 of the fourth quarter Form 8-K for the year concerned. Adjusted operating income, adjusted EPS, free cash flow and return on investment are Walmart's own measures outside GAAP and are defined in those same exhibits.
Gross margin of 24.21% of net sales is the highest since FY2022 and still 23 bps below it, led by Walmart U.S. and by advertising and membership income that carry almost no cost of sales. SG&A rose faster, up 21 bps to 20.94%, so operating margin fell. Advertising grew 46% to nearly $6.4bn in FY2026 and membership fee revenue grew 15.1% in the fourth quarter, both mix positive for gross margin and both reported inside the segments rather than as a separate line.
Share repurchases of $8,088m were the largest since FY2023 and lifted the payout to $15,595m, which exceeded free cash flow. Walmart announced a new $30,000m repurchase authorisation on 19 February 2026, of which $25,100m remained at 31 July 2026.

GAAP against core earnings
Walmart carries its stakes in JD.com, Symbotic and other holdings at fair value through income, so quarterly marks run through the income statement below operating income. Those marks are the largest single reason GAAP and adjusted earnings diverge. Management also excludes a set of charges from operating income, and that list changes from year to year, which limits comparison of the adjusted series across the five years. FY2023 excluded $3,325m of opioid legal charges and $849m of reorganisation charges; FY2026 excludes a $722m noncash share based compensation charge at PhonePe triggered by a modification of share payment plans ahead of a possible listing.
Table 7. Reconciliation of reported to adjusted results ($m except per share)
| FY2025 | FY2026 | |
|---|---|---|
| Operating income, as reported | 29,348 | 29,825 |
| Incremental noncash share based compensation, PhonePe | 722 | |
| Certain legal matters | 285 | |
| Business reorganisation charges | 255 | 150 |
| Opioid related legal matters | (99) | |
| Adjusted operating income | 29,504 | 30,982 |
| Constant currency effect | 114 | |
| Adjusted operating income, constant currency | 29,504 | 31,096 |
| Per diluted share | ||
| Reported diluted EPS | $2.41 | $2.73 |
| Equity and other investments, net (gains) and losses | $0.09 | $(0.20) |
| Incremental noncash share based compensation | $0.07 | |
| Certain legal matters | $0.03 | |
| Business reorganisation charges | $0.02 | $0.01 |
| Opioid related legal matter | $(0.01) | |
| Adjusted EPS | $2.51 | $2.64 |
| Reported effective tax rate | 23.4% | 24.4% |
| Adjusted effective tax rate | 23.6% | 23.9% |
Components may not sum because Walmart rounds each line to a cent.


Segment margin
Table 8. Segment operating income and margin, FY2022 to FY2026 ($m)
| FY2022 | FY2023 | FY2024 | FY2025 | FY2026 | |
|---|---|---|---|---|---|
| Walmart U.S. | |||||
| Net sales | 393,247 | 420,553 | 441,817 | 462,415 | 482,975 |
| Operating income | 21,587 | 20,620 | 22,154 | 23,882 | 25,158 |
| Operating margin | 5.49% | 4.90% | 5.01% | 5.16% | 5.21% |
| Walmart International | |||||
| Net sales | 100,959 | 100,983 | 114,641 | 121,885 | 130,423 |
| Operating income | 3,758 | 2,965 | 4,909 | 5,501 | 5,103 |
| Operating margin | 3.72% | 2.94% | 4.28% | 4.51% | 3.91% |
| Sam's Club U.S. | |||||
| Net sales | 73,556 | 84,345 | 86,179 | 90,238 | 93,015 |
| Operating income | 2,259 | 1,964 | 2,192 | 2,404 | 2,442 |
| Operating margin | 3.07% | 2.33% | 2.54% | 2.66% | 2.63% |
| Corporate and support | (1,662) | (5,121) | (2,243) | (2,439) | (2,878) |
| Consolidated operating income | 25,942 | 20,428 | 27,012 | 29,348 | 29,825 |
| Consolidated operating margin | 4.53% | 3.34% | 4.17% | 4.31% | 4.18% |
Walmart U.S. margin has recovered for three consecutive years and still sits 28 bps below FY2022. Walmart International gave back 60 bps in FY2026 on the PhonePe charge; excluding it and the currency effect, International adjusted operating income grew 8.0%. Corporate and support cost grew 18.0% to $2,878m, faster than any segment.
Ratio analysis
Table 9. Ratio analysis, FY2022 to FY2026
| FY2022 | FY2023 | FY2024 | FY2025 | FY2026 | |
|---|---|---|---|---|---|
| Growth | |||||
| Total revenue growth | n/a | 6.7% | 6.0% | 5.1% | 4.7% |
| Operating income growth | n/a | (21.3%) | 32.2% | 8.6% | 1.6% |
| Adjusted operating income growth | n/a | (5.6%) | 10.2% | 8.9% | 5.0% |
| Adjusted EPS growth | n/a | (2.3%) | 5.7% | 13.1% | 5.2% |
| Margin | |||||
| Gross margin | 24.44% | 23.46% | 23.73% | 24.13% | 24.21% |
| SG&A rate | 20.75% | 20.98% | 20.38% | 20.74% | 20.94% |
| Operating margin | 4.53% | 3.34% | 4.17% | 4.31% | 4.18% |
| Adjusted operating margin | 4.55% | 4.02% | 4.18% | 4.33% | 4.34% |
| EBITDA margin | 6.39% | 5.13% | 6.00% | 6.21% | 6.17% |
| Net margin | 2.39% | 1.91% | 2.39% | 2.85% | 3.07% |
| Return | |||||
| Return on equity | 16.7% | 14.6% | 19.3% | 22.2% | 23.0% |
| Return on assets | 5.6% | 4.6% | 6.6% | 7.9% | 8.2% |
| Return on invested capital | 16.2% | 11.3% | 16.3% | 17.2% | 16.1% |
| Adjusted return on invested capital | 16.3% | 13.6% | 16.3% | 17.3% | 16.7% |
| Leverage | |||||
| Total debt | 42,831 | 44,622 | 46,891 | 45,790 | 51,523 |
| Net debt | 28,071 | 35,997 | 37,024 | 36,753 | 40,796 |
| Total debt to EBITDA | 1.17x | 1.42x | 1.21x | 1.08x | 1.17x |
| Net debt to EBITDA | 0.77x | 1.15x | 0.95x | 0.87x | 0.93x |
| Operating income to net interest | 14.1x | 10.9x | 12.6x | 13.1x | 12.3x |
| Liquidity | |||||
| Current ratio | 0.93x | 0.82x | 0.83x | 0.82x | 0.79x |
| Quick ratio | 0.28x | 0.21x | 0.24x | 0.24x | 0.24x |
| Free cash flow cover of dividends and buybacks | 0.69x | 0.75x | 1.70x | 1.13x | 0.96x |
| Efficiency | |||||
| Inventory turns | 8.46x | 8.20x | 8.79x | 9.19x | 9.29x |
| Days inventory | 43.2 | 44.5 | 41.5 | 39.7 | 39.3 |
| Days payable | 44.4 | 42.9 | 41.2 | 41.2 | 41.5 |
| Days receivable | 4.7 | 4.8 | 4.7 | 5.0 | 5.4 |
| Cash conversion cycle, days | 3.5 | 6.4 | 5.1 | 3.6 | 3.2 |
| Asset turnover | 2.30x | 2.50x | 2.62x | 2.65x | 2.61x |
| Capital expenditure to revenue | 2.3% | 2.8% | 3.2% | 3.5% | 3.7% |
| Free cash flow to revenue | 1.9% | 2.0% | 2.3% | 1.9% | 2.1% |
| Free cash flow to net income | 81.0% | 102.6% | 97.5% | 65.1% | 68.2% |
Returns use average balances across the opening and closing balance sheet. Return on assets is consolidated net income over average total assets, which is Walmart's own definition and reproduces its stated 8.2% for FY2026 and 7.9% for FY2025. Return on invested capital is operating income after tax at the effective rate, over average total debt plus total equity less cash. Total debt includes short term borrowings, long term debt and finance lease obligations, current and noncurrent, which is Walmart's own debt definition and reproduces the $57.2bn it reported at 31 July 2026.
Return on equity of 23.0% is the highest of the five years and the wrong metric to lean on. It rose while return on invested capital fell, because net income carried the investment gain, buybacks held the equity base down and total debt rose $5,733m. Return on invested capital of 16.1% is the second lowest of the five years and sits 114 bps below FY2025 despite record adjusted operating income. Invested capital grew 5.2% a year over five years while adjusted operating income grew 4.4%.

The FY2023 cash flow comparison carries a discrepancy between filings. The 8-K earnings release of 21 February 2023 reported operating cash flow of $29,101m and free cash flow of $12,244m; the audited FY2023 10-K reports $28,841m, a difference of $260m. The reconciling item is the movement in accounts payable, restated from $(1,165)m in the release to $(1,425)m in the 10-K, and no other line moved. Every FY2023 figure in this report uses the audited 10-K amounts, so free cash flow reads $11,984m rather than the $12,244m first announced.


The current ratio of 0.79 times is the lowest of the five years. Negative working capital is financed by $63,061m of accounts payable, and interest cover on operating income is 12.3 times. Short term borrowings more than doubled to $6,596m, which is what pushed the current ratio down; total debt to EBITDA of 1.17 times is unchanged against FY2022.
The first half of FY2027
Table 10. First half FY2027 against first half FY2026 ($m except per share)
| H1 FY2026 | H1 FY2027 | Change | Change % | |
|---|---|---|---|---|
| Total revenues | 343,011 | 365,688 | 22,677 | 6.6% |
| Gross profit | 82,657 | 89,922 | 7,265 | 8.8% |
| Selling, general and administrative expenses | 71,516 | 76,950 | 5,434 | 7.6% |
| Operating income | 14,421 | 16,876 | 2,455 | 17.0% |
| Adjusted operating income | 15,011 | 17,057 | 2,046 | 13.6% |
| Adjusted operating income, constant currency | 15,011 | 16,745 | 1,734 | 11.6% |
| Other gains and losses | 2,111 | (925) | (3,036) | n/a |
| Income before income taxes | 15,313 | 15,160 | (153) | (1.0%) |
| Provision for income taxes | 3,523 | 3,141 | (382) | (10.8%) |
| Net income attributable to Walmart | 11,513 | 11,696 | 183 | 1.6% |
| GAAP diluted EPS | $1.43 | $1.46 | $0.03 | 2.1% |
| Adjusted EPS | $1.29 | $1.46 | $0.17 | 13.2% |
| Operating cash flow | 18,352 | 19,710 | 1,358 | 7.4% |
| Capital expenditure | 11,409 | 14,181 | 2,772 | 24.3% |
| Free cash flow | 6,943 | 5,529 | (1,414) | (20.4%) |
| Gross margin | 24.33% | 24.86% | 53 bps | |
| Operating margin | 4.20% | 4.61% | 41 bps | |
| Effective tax rate | 23.01% | 20.72% | (229 bps) |
The signs reverse against FY2026. GAAP EPS grew 2.1% while adjusted EPS grew 13.2%, because the prior year half carried a $2,111m investment gain and this one carries a $925m loss. The reported tax rate of 20.7% includes a discrete benefit from a change in unrecognised tax benefits; Walmart puts the adjusted rate at 23.9%. Second quarter gross margin gained 96 bps, which Walmart attributes primarily to tariff refunds received, partly returned to customers as price investment, and says the remaining refunds will go the same way. Read without that, the underlying second quarter operating income growth was at the top end of its own guidance.
Cash moved the other way. Capital expenditure rose 24.3% in six months and free cash flow fell 20.4% to $5,529m. Total debt reached $57,243m at 31 July 2026 against $51,523m at the year end, inventory rose 6.7% to $61,600m and equity attributable to Walmart fell to $98,238m after $5,100m of buybacks.

Management raised the FY2027 outlook on 20 August 2026 to net sales growth of 4.0% to 5.0% and adjusted operating income growth of 7.0% to 8.5%, both in constant currency, with adjusted EPS of $2.80 to $2.87. At the midpoint the guidance asks for adjusted operating income to grow roughly twice as fast as sales, which needs the gross margin gain to hold once the tariff refunds stop. Chapter 3 sets out what the raise implies for the second half.
3 MD&A & Management Commentary
Walmart's own commentary now turns on one item. A $2.9bn tariff refund landed in the quarter ended 31 July 2026, went through cost of sales, and management is reinvesting it in price. Reported operating income rose 28.8% in the quarter. Adjusted, in constant currency, it rose 17.4%. The raised fiscal 2027 guidance implies second half adjusted operating income growth of 0.8% to 3.7% against 13.6% delivered in the first half. The chief financial officer says as much in the release itself. For a holder of the stock, the second half is where the refund gets handed to the customer, and the guidance already carries that.
Management's second theme is cost it does not control. Self insured general liability claims added roughly $0.9bn to fiscal 2026 operating expense and are still named as a driver in the July 2026 quarter. Fuel in distribution and fulfilment cost 250 basis points of consolidated operating income growth in the April quarter. Pharmacy deflation from maximum fair price regulation took 125 basis points off Walmart U.S. comparable sales in the July quarter.
Against that, the ecosystem lines management leads with keep compounding. Global advertising grew 38% and membership fee revenue 17% in the July quarter, and eCommerce net sales grew $8.2bn, or 23%.
What management flags
Table 11. Trends and risks Walmart names itself, with the filing or call and the date
| Trend management names | What management says | Size disclosed | Source | Date |
|---|---|---|---|---|
| Tariffs and trade restrictions, including refunds | Refunds received under the CBP process were credited to cost of sales, and a significant portion was reinvested in customer facing initiatives, mainly price. | $2.9bn received; about 0.5% of annual U.S. net sales | Form 10-Q, period 31 Jul 2026; earnings call | 28 Aug 2026 |
| Import exposure | Less than one third of U.S. merchandise is imported, sourced mostly from China, Vietnam, Mexico, India and Canada. | Less than one third of U.S. sales | Form 10-K, period 31 Jan 2026 | 13 Mar 2026 |
| Price investment through the second half | Prioritising the remaining refunds into price is why Q2 and Q3 should be read together. | Guidance raised, not the run rate | Form 8-K exhibit 99.1 | 20 Aug 2026 |
| Self insured general liability claims | Rising costs to resolve claims across retail and related industries. Still a named driver four quarters later. | About $0.9bn added in FY2026 | Form 10-K, period 31 Jan 2026 | 13 Mar 2026 |
| Associate healthcare benefit costs | Increased enrolment and medical cost inflation. New to the fiscal 2027 commentary. | Not quantified | Form 10-Q, period 31 Jul 2026 | 28 Aug 2026 |
| Fuel cost in distribution and fulfilment | Higher fuel costs reduced consolidated operating income growth in the April quarter and continue to weigh on gross profit. | 250 bps in Q1 FY2027 | Form 8-K exhibit 99.1 | 21 May 2026 |
| Pharmacy deflation | Maximum fair price regulation effective January 2026 cut Walmart U.S. comparable sales. | 125 bps in Q2 FY2027 | Form 8-K exhibit 99.1 | 20 Aug 2026 |
| Depreciation from the capital programme | Capital investment is raising depreciation faster than sales. | Capex $26.6bn in FY2026, up $2.9bn | Form 10-K, period 31 Jan 2026 | 13 Mar 2026 |
| Higher margin ecosystem mix | Advertising, marketplace and membership are named as the mix shift that lifts gross profit rate. | Advertising up 38%, membership fees up 17% in Q2 FY2027 | Form 8-K exhibit 99.1 | 20 Aug 2026 |
| eCommerce economics | Store and club fulfilled delivery drives the growth and improved segment economics. | Net sales up $8.2bn, or 23%, in Q2 FY2027 | Form 10-Q, period 31 Jul 2026 | 28 Aug 2026 |
| PhonePe share based payment charge | Arrangements were modified in contemplation of a potential public offering. No tax benefit, so the effective rate rose. | $0.7bn in FY2026 | Form 10-K, period 31 Jan 2026 | 13 Mar 2026 |
| Currency | A fiscal 2026 headwind became a fiscal 2027 tailwind on net sales. | $(2.8)bn in FY2026; $3.9bn in H1 FY2027 | Form 10-K and Form 10-Q | 28 Aug 2026 |
| Flipkart event timing | Big Billion Days shifts between the third and fourth quarters and moves reported growth. | Over 100 bps off Q3 FY2027 sales growth | Form 8-K exhibit 99.1 | 20 Aug 2026 |
| Segment reporting change | Corporate overhead allocation was updated from February 2026 and prior periods were revised. | Not quantified by segment | Form 10-Q, period 31 Jul 2026 | 28 Aug 2026 |
| Contingencies | Opioid matters, Asda equal value claims, the money transfer agent services investigation, driver platform litigation, and antitrust matters in Mexico and India. | No range estimable for several | Form 10-K and Form 10-Q | 28 Aug 2026 |
The company does not quantify the associate healthcare cost, and it does not split the tariff refund by segment or size the offsetting price investment. Both gaps sit directly under the numbers that moved most.
GAAP against core earnings in the quarter

The 28.8% headline is built on a prior year quarter that carried $440m of legal charges and $150m of reorganisation charges. Strip those from the base and take out a $135m currency tailwind, and the underlying move is 17.4%. The gap between the two framings is 11.4 percentage points. Sitting inside the underlying figure is the refund itself: $2.9bn is 6.1% of the quarter's gross profit, 30.9% of its operating income, and 1.4 times the year on year increase in operating income, before the price investment management set against it. That offset is not quantified in either filing.
Below the operating line the direction reverses. Equity investment marks turned from a $2.7bn net gain in the July 2025 quarter to a $1.2bn net loss in July 2026, so reported net income fell 8.7% while operating income rose 28.8%. A change in unrecognised tax benefits cut the effective rate to 18.5% from 23.3%, worth $0.11 of the $0.80 reported EPS on the company's own bridge.
Table 12. Reported to core earnings, quarter and half ended 31 July 2026
| Line | Q2 FY2027 | H1 FY2027 |
|---|---|---|
| Operating income, as reported ($m) | 9,383 | 16,876 |
| Business reorganisation charges ($m) | 0 | 181 |
| Adjusted operating income ($m) | 9,383 | 17,057 |
| Currency exchange rate fluctuations ($m) | (135) | (312) |
| Adjusted operating income, constant currency ($m) | 9,248 | 16,745 |
| Growth on the prior year, as reported | 28.8% | 17.0% |
| Growth on the prior year, adjusted | 19.1% | 13.6% |
| Growth on the prior year, adjusted constant currency | 17.4% | 11.6% |
| Diluted EPS, as reported ($) | 0.80 | 1.46 |
| Equity and other investment marks ($) | 0.12 | 0.10 |
| Certain tax matter ($) | (0.11) | (0.11) |
| Business reorganisation charges ($) | 0.00 | 0.01 |
| Adjusted EPS ($) | 0.81 | 1.46 |
| Effective tax rate, as reported | 18.5% | 20.7% |
| Effective tax rate, adjusted | 24.8% | 23.9% |
Two adjusted operating income figures for fiscal 2026 circulate in Walmart's own disclosure. The itemised reconciliation in Table 7 gives $30,982m. The rounded base management guides fiscal 2027 growth from is $31.0bn, which sits $1,175m above GAAP operating income of $29,825m against the $1,157m the reconciliation itemises. Chapter 9 sets out what that rounding does and does not change in a margin forecast.
The guidance path

Table 13. Fiscal 2027 guidance and what it implies
| Consolidated metric | 19 Feb 2026 | 21 May 2026 | 20 Aug 2026 |
|---|---|---|---|
| Net sales growth, constant currency | 3.5% to 4.5% | Unchanged | 4.0% to 5.0% |
| Adjusted operating income growth, constant currency | 6.0% to 8.0% | Unchanged | 7.0% to 8.5% |
| Adjusted interest, net | Up about $200m to $300m | Unchanged | Unchanged |
| Effective tax rate | 23.5% to 24.5% | Unchanged | Unchanged |
| Adjusted EPS | $2.75 to $2.85 | Unchanged | $2.80 to $2.87 |
| Capital expenditure, % of net sales | About 3.5% | Unchanged | About 4.0% |
| Implied adjusted operating income ($m) | 32,860 to 33,480 | Unchanged | 33,170 to 33,635 |
| Implied second half adjusted operating income ($m) | n/a | n/a | 16,113 to 16,578 |
| Implied second half growth on the prior year | n/a | n/a | 0.8% to 3.7% |
The May guidance carried a specific caveat: it did "not assume any impact from IEEPA tariff refunds." The August raise is the refund arriving. The refund is $2.9bn. The raise adds $310m at the bottom of the implied adjusted operating income range and $155m at the top. The rest is going back to the customer.
The capital expenditure guide moved from about 3.5% to about 4.0% of net sales. At the midpoint of the August sales guide that is $25.8bn against $29.5bn, an increase of about $3.7bn. The 10-K, filed in March, projected $25bn to $27bn for the year, so the August rate sits above the range the annual report set. Depreciation from this programme is already a named operating expense driver.
For the third quarter, management guides net sales growth of 3.0% to 3.75% and adjusted operating income growth of 2.0% to 4.0% in constant currency, against 28.8% reported in the second quarter.
Segment commentary and the margin it produces

Table 14. What management attributes each segment's July quarter move to
| Segment | Net sales ($m) | Operating income ($m) | Gross profit rate (bps) | Operating expense rate (bps) | Management's attribution |
|---|---|---|---|---|---|
| Walmart U.S. | 125,189 | 8,120 | 158 | 72 | Tariff refunds and business mix lift gross profit; price investment and fuel offset. Claims, depreciation and healthcare costs deleverage expense. |
| Walmart International | 35,198 | 1,439 | (15) | (29) | Price investment, format mix and a discrete sales related reserve press margin. Cost control and format mix reduce expense. |
| Sam's Club U.S. | 25,713 | 678 | 45 | (26) | Tariff refunds lift gross profit; price investment and club fulfilled delivery costs offset. Higher fuel sales lever expense. |
The fiscal 2026 picture is the mirror image. The gross profit rate held, up 8 basis points, but operating margin fell 13 basis points because roughly $0.9bn of claims expense and a $0.7bn PhonePe charge landed in operating expense. Those two items alone are 23 basis points of net sales, and the PhonePe charge carried no tax benefit, which is what pushed the effective rate from 23.4% to 24.4%.
Return on assets and return on investment moved in opposite directions on a trailing twelve month basis to 31 July 2026. Return on assets fell to 8.0% from 8.3% on lower investment marks. Return on investment rose to 15.4% from 15.1% on higher operating income. The divergence is the same GAAP against core split as the EPS bridge, one period further on.
Where the framing and the numbers part company
Management's own release warns against the headline it prints. The chief financial officer wrote: "Our operating income outlook reflects the continued prioritization of tariff refunds received in Q2 into customer experience and price investments in the second half. For this reason, I encourage you to consider Q2 and Q3 performance together to assess the underlying growth of the business." The arithmetic in Table 13 supports the warning: first half adjusted operating income of $17,057m against the raised full year guide leaves 0.8% to 3.7% growth for the second half.
Two comparable sales figures exist for the same quarter, both Walmart's own. The 10-Q reports Walmart U.S. calendar comparable sales of 3.3% including fuel on the fiscal calendar. The release reports 2.6% excluding fuel on the retail 4-5-4 calendar. For Sam's Club U.S. the gap is wider, 8.6% against 4.4%, because fuel added 4.2 percentage points on the calendar basis. Both bases are disclosed and defined. Neither is bridged to the other, so a reader comparing across quarters has to pick one and hold it.
The 20 August release quantifies the health and wellness drag twice on different bases and does not reconcile them: 80 basis points as a net headwind to Walmart U.S. comparable sales in the headline, and 125 basis points for pharmacy deflation in the Walmart U.S. section. On the earnings call the chief financial officer gave the quarter as "closer to 125 basis points" and the full year estimate as the same.
The February 2026 change to corporate overhead allocation is neutral to consolidated operating income. Prior year segment operating income totals $8,436m for the July 2025 quarter on both the original and the revised presentation. It changes published segment growth rates. Sam's Club U.S. prior year operating income was revised down $19m to $470m, which lifts the reported growth rate for the quarter from 38.7% on the original base to 44.3% on the revised one. Walmart U.S. was revised up $12m, trimming its reported growth from 20.8% to 20.6%. The 10-Q states the revision but does not quantify it by segment.
Sourcing disclosure moved without comment. The fiscal 2026 10-K names the largest import sources as China, Mexico, Vietnam, India and Canada. The July 2026 10-Q names them as China, Vietnam, Mexico, India and Canada. Vietnam has moved ahead of Mexico.
4 Sector & Competitor Analysis
Walmart is the scale leader of a slow growing sector and the only company in its peer set that pairs a below median return on capital with an above median earnings rating. Fiscal 2026 revenue of $713.2bn grew 4.7%, the middle of an eight company peer set, on a 4.18% operating margin that ranks fifth of eight. Return on invested capital of 15.4% on the definition used here sits just under the peer median of 16.4%. Net financial debt of 0.9 times EBITDA leaves capacity unused. The stock trades at 39.0 times reported diluted earnings against a peer median of 29.0 times, second only to Costco at 51.1 times. Costco earns 36.8% on capital, more than twice Walmart's return, for a third more rating. The counterargument is the mix set out in Chapter 1: fee, advertising and marketplace income funds 23% of consolidated operating income and carries no merchandise cost, and eCommerce is 21.3% of net sales.
The sector
United States retail trade ran at $2,012.0bn in the second quarter of 2026, an annual rate of about $8.0 trillion. Adding food services lifts the July 2026 monthly figure to $763.6bn, up 5.0% on July 2025 and down 0.6% on June. Electronic commerce took 17.1% of retail sales on a seasonally adjusted basis, $340.2bn in the quarter. Both series come from the U.S. Census Bureau.
Walmart U.S. and Sam's Club U.S. net sales of $576.0bn equal 7.2% of that annualised retail trade base. Amazon is second on United States sales at $489.7bn, and no other peer is within a factor of two of either. The channel Walmart sells most through, warehouse clubs and supercentres, is the smallest of the four the Census tracks at an $801bn annual rate.

Three forces set margins in this sector, and each shows in the filings.
Scale on purchasing sets the gross margin floor. Costco runs a 12.8% gross margin and BJ's 18.6%, the two thinnest in the peer set, and both recover profit through fees. Membership fees of $5,323m are 51% of Costco's operating income and membership fee income of $500m is 61% of BJ's. Fee revenue carries no merchandise cost, so a club can price goods close to cost and still clear a return.
Density of fulfilment sets the operating margin. Walmart U.S. earns 5.21% on net sales, Walmart International 3.91% and Sam's Club U.S. 2.63%. The spread reflects the cost of serving customers across formats and geographies.
Mix into fee, advertising and marketplace income sets the direction of margin. Walmart's membership and other income of $6,750m is 0.95% of total revenue and 23% of operating income, so its growth moves the consolidated rate.
The peer set and the rule that picks it
The rule is a size screen on the company's own industry code, widened to the two adjacent channels Walmart names in its own competition disclosure. Item 1 of the fiscal 2026 Form 10-K names discount, department, grocery, drug, dollar, variety and specialty stores, supermarkets, supercentres, membership only warehouse clubs, and eCommerce and omnichannel operators as its competitors.
Selection rule: every active United States filer under SIC 5331, Retail Variety Stores, with revenue above $15bn in its latest annual report, plus the largest listed operator of each adjacent channel named above, retail grocery under SIC 5411 and online and marketplace retail under SIC 5961. Delisted filers are excluded. The screen returns Costco, Target, Dollar General, Dollar Tree and BJ's Wholesale from SIC 5331, and Kroger and Amazon from the adjacent channels. It excludes the only two other active SIC 5331 filers, Ollie's Bargain Outlet at $2,649m of revenue for the year to 31 January 2026 and PriceSmart at $5,270m for the year to 31 August 2025.
Table 15. The peer set, the channel each occupies, and the filing each figure is read from
| Ticker | Company | Channel | SIC | Fiscal period | Form | Accession |
|---|---|---|---|---|---|---|
| WMT | Walmart Inc. | Supercentre and club | 5331 | Year to 31 Jan 2026 | 10-K | 0000104169-26-000055 |
| AMZN | Amazon.com, Inc. | Online and marketplace | 5961 | Year to 31 Dec 2025 | 10-K | 0001018724-26-000004 |
| COST | Costco Wholesale Corporation | Warehouse club | 5331 | Year to 31 Aug 2025 | 10-K | 0000909832-25-000101 |
| KR | The Kroger Co. | Supermarket | 5411 | Year to 31 Jan 2026 | 10-K | 0001104659-26-037723 |
| TGT | Target Corporation | Discount general merchandise | 5331 | Year to 31 Jan 2026 | 10-K | 0000027419-26-000016 |
| DG | Dollar General Corporation | Small box discount | 5331 | Year to 30 Jan 2026 | 10-K | 0001104659-26-032325 |
| BJ | BJ's Wholesale Club Holdings | Warehouse club | 5331 | Year to 31 Jan 2026 | 10-K | 0001531152-26-000007 |
| DLTR | Dollar Tree, Inc. | Small box discount | 5331 | Year to 31 Jan 2026 | 10-K | 0000935703-26-000025 |
Fiscal calendars do not line up. Six of the eight close within two days of 31 January 2026. Amazon closes on 31 December 2025 and Costco on 31 August 2025. Costco's year overlaps Walmart's fiscal 2026 by seven months and is the only one in the set that carries no 2026 trading at all. Amazon's revenue of $716.9bn exceeds Walmart's $713.2bn, but the two periods share eleven of twelve months. Walmart also consolidates operations outside the United States and Canada on a one month lag and on a calendar year basis, so its international figures cover the twelve months to 31 December 2025.
Like for like comparison
Table 16. Peer comparison on one set of definitions, latest reported fiscal year
| Ticker | Fiscal period | Revenue $bn | Growth % | Gross margin % | Operating margin % | Return on capital % | Net debt / EBITDA x | Including operating leases x | Price / earnings x | EV / EBITDA x | Market value $bn |
|---|---|---|---|---|---|---|---|---|---|---|---|
| WMT | Year to 31 Jan 2026 | 713.2 | 4.7 | 24.9 | 4.18 | 15.4 | 0.9 | 1.3 | 39.0 | 20.1 | 845 |
| AMZN | Year to 31 Dec 2025 | 716.9 | 12.4 | 50.3 | 11.16 | 17.4 | (0.3) | 0.3 | 35.5 | 18.6 | 2,749 |
| COST | Year to 31 Aug 2025 | 275.2 | 8.2 | 12.8 | 3.77 | 36.8 | (0.6) | (0.4) | 51.1 | 31.6 | 413 |
| KR | Year to 31 Jan 2026 | 147.6 | 0.4 | 23.3 | 1.28 | 8.0 | 2.7 | 4.1 | 37.9 | 9.6 | 36 |
| TGT | Year to 31 Jan 2026 | 104.8 | (1.7) | 27.9 | 4.88 | 14.7 | 1.3 | 1.8 | 20.2 | 10.4 | 75 |
| DG | Year to 30 Jan 2026 | 42.7 | 5.2 | 30.7 | 5.16 | 14.2 | 1.1 | 4.5 | 19.4 | 10.1 | 29 |
| BJ | Year to 31 Jan 2026 | 21.5 | 4.7 | 18.6 | 3.81 | 22.4 | 0.5 | 2.4 | 21.3 | 11.1 | 12 |
| DLTR | Year to 31 Jan 2026 | 19.4 | 10.4 | 36.4 | 8.52 | 22.7 | 0.7 | 2.8 | 22.4 | 11.6 | 25 |
Definitions, applied identically to every company. Revenue is total revenue on the face of the income statement. Growth compares that figure with the prior year on the same basis. Gross margin is revenue less the cost line immediately below it, divided by revenue. Return on capital is operating income after the company's own effective tax rate, divided by year end equity including noncontrolling interests plus short term borrowings, current and noncurrent long term debt and finance lease liabilities, less cash, cash equivalents and short term investments. That base is not the average balance definition used in Table 9, which is why Walmart reads 15.4% here and 16.1% there. Operating lease liabilities are excluded from the base because operating lease cost is charged in full inside operating income; the final leverage column adds them back for readers who prefer a capitalised rent view. EBITDA is operating income plus depreciation and amortisation from the cash flow statement. Price to earnings uses diluted earnings per share as filed and the last trade on 2 September 2026. Market value uses the share count on the cover page of each issuer's most recent periodic report.
Two gross margins in Table 16 rest on cost definitions that differ from the rest. Amazon's cost of sales excludes fulfilment, shipping and technology costs, which is why it reads 50.3%. Kroger's merchandise costs exclude rent and depreciation, which lifts its 23.3%. Read the operating margin column instead for those two.

Walmart ranks fourth or fifth of eight on every one of the five measures and reaches neither extreme on any of them. It grows at 4.7% against a range of (1.7)% to 12.4%. It converts 4.18% of revenue into operating income against a range of 1.28% to 11.16%. It earns 15.4% on capital against 8.0% to 36.8%. It carries 0.9 times leverage against a range from net cash at Costco and Amazon to 2.7 times at Kroger. Its gross margin is 24.9% against a range of 12.8% to 50.3%.
Amazon's 11.16% operating margin overstates the retail comparison. Amazon Web Services contributed $45,606m of operating income on $128,725m of net sales, 57% of the group total. Amazon's two retail segments earned $34,369m on $588,199m of net sales, a 5.84% margin. Against that number Walmart U.S. at 5.21% is close, and the consolidated 4.18% is diluted by international and club operations. Table 3 shows where the dilution occurs: Walmart U.S. produces 77% of segment operating income on 68% of net sales, and Sam's Club U.S. produces 7% on 13%, a club margin close to BJ's 3.81% and Costco's 3.77%. Consolidated operating income is 4.22% of net sales and 4.18% of total revenue, the difference being the membership and other income line in the denominator.
Reported earnings against core earnings across the peer set
Three peers report figures that a single distorting item moves materially. Each item is disclosed by the company itself.
Table 17. Reported to core earnings, latest fiscal year ($m except per share)
| Item | KR | AMZN | WMT |
|---|---|---|---|
| Nature of the item | Fulfilment network impairment and related charges | Other income, net, below operating income | Other gains and losses, below operating income |
| Operating income, reported | 1,890 | 79,975 | 29,825 |
| Item inside operating income | (2,497) | n/a | n/a |
| Operating income, core | 4,387 | 79,975 | 29,825 |
| Operating margin, reported % | 1.28 | 11.16 | 4.18 |
| Operating margin, core % | 2.97 | 11.16 | 4.18 |
| Net income, reported | 1,016 | 77,670 | 21,893 |
| Item after tax | (1,908) | 12,240 | 1,568 |
| Net income, core | 2,924 | 65,430 | 20,325 |
| Diluted earnings per share, reported | 1.54 | 7.17 | 2.73 |
| Diluted earnings per share, core | 4.43 | 6.04 | 2.53 |
| Price to earnings, reported x | 37.9 | 35.5 | 39.0 |
| Price to earnings, core x | 13.2 | 42.2 | 42.0 |
The Kroger adjustment is the largest in the set and reverses the reading of Table 16. Kroger charged $2,497m against operating income for fulfilment network impairment, $1,908m after tax. Excluding it, Kroger's operating margin is 2.97% rather than 1.28% and the stock trades at 13.2 times rather than 37.9 times, the cheapest rating among the eight rather than the second dearest.
The adjustments run the other way for Walmart and Amazon. Amazon booked $17,336m of nonoperating income, of which $15,229m sits in a single other income line, and three valuation items account for $14,748m of that line: $7,709m of upward price adjustments on equity securities without a readily determinable fair value, $5,600m reclassified from available for sale debt securities, and $1,439m of unrealised gains on marketable equity securities. Walmart's $2,075m of other gains, $1,568m after tax, lifts its reported diluted earnings per share from $2.53 to $2.73. On core earnings Walmart trades at 42.0 times and Amazon at 42.2 times, a difference of 0.2 times against 3.5 times on reported figures.
What the market pays for return

Only Costco and Amazon sit above the peer median on both return and rating. Walmart sits below the median on return and well above it on rating, alone in that quadrant with Kroger, whose position is an artefact of the impairment corrected in Table 17. Target, Dollar General, Dollar Tree and BJ's all sit below the median rating, and two of them, Dollar Tree at 22.7% and BJ's at 22.4%, earn a higher return on capital than Walmart at 15.4%.
The enterprise value multiple narrows the gap but does not close it. Walmart trades at 20.1 times EBITDA against a peer set that runs from 9.6 times for Kroger to 31.6 times for Costco, with Target, Dollar General, Dollar Tree and BJ's clustered between 10.1 and 11.6 times. Walmart is rated nearly twice the small box and discount cohort on operating cash earnings while growing at a similar rate: 4.7% against 5.2% for Dollar General and 4.7% for BJ's.
Two facts support the rating. Walmart's $150.4bn of eCommerce net sales is a business the discount cohort does not have at scale, and its fee, advertising and marketplace income grows without merchandise cost. Two facts weigh against it. Return on capital at 15.4% is below the peer median of 16.4%, and the shares carry a rating 34% above the peer median of 29.0 times on revenue growth of 4.7%.
5 Material Events & Contracts
Walmart disclosed twenty material events across eighteen Form 8-K and Form 8-K/A filings in the twelve months to 2 September 2026. None of them changed what the company sells or where it sells it. There were no acquisitions, no divestitures, no impairments, no litigation triggers, no covenant events and no change of auditor. The change was concentrated in two places: the top of the house, where the chief executive, all three segment chief executives, the controller and the board slate turned over inside ninety days, and the balance sheet, where a $4.25bn note offering, a $30.0bn repurchase authorisation and a move from the NYSE to Nasdaq all landed within six months. Walmart is a domestic filer and files no Form 6-K.
For the stock, the succession is the event that carries risk and the capital return is the event that carries support. John Furner took over a company compounding revenue at 4.7% for fiscal 2026 and guiding to 4.0% to 5.0% for fiscal 2027, and the board handed him a $30.0bn buyback authorisation, roughly 3.7 years of repurchase at the fiscal 2026 pace of $8.1bn, in his first month in the chair.

Table 18. Material events, twelve months to 2 September 2026
Sorted newest first. Item numbers list only those relied on, so a filing's cover may name more. Two filings each carry two distinct events and so appear twice.
| Date | Form and item | Event | Accession number |
|---|---|---|---|
| 20 Aug 2026 | 8-K, 2.02, 9.01 | Second quarter fiscal 2027 results: revenue of $187.9bn up 5.9%, operating income up 28.8%, GAAP EPS of $0.80 and adjusted EPS of $0.81, with the fiscal 2027 adjusted EPS outlook raised to $2.80 to $2.87. | 0000104169-26-000145 |
| 5 Jun 2026 | 8-K, 5.03 | A charter amendment limiting the liability of certain officers as far as Delaware law permits was filed in Delaware on 4 June 2026 and took effect on filing, alongside a restated certificate of incorporation. | 0000104169-26-000111 |
| 5 Jun 2026 | 8-K, 5.07 | At the 4 June 2026 annual meeting all eleven director nominees were elected, Ernst & Young LLP was ratified, say on pay passed and all four shareholder proposals were rejected. | 0000104169-26-000111 |
| 21 May 2026 | 8-K, 2.02, 9.01 | First quarter fiscal 2027 results: revenue of $177.8bn up 7.3%, operating income up 5.0%, GAAP EPS of $0.67 and adjusted EPS of $0.66, with the fiscal 2027 outlook reiterated. | 0000104169-26-000095 |
| 30 Apr 2026 | 8-K, 8.01, 9.01 | Five tranches of senior unsecured notes totalling $4.25bn priced on 27 April 2026 for net proceeds of $4,230,348,500, with the underwriting and pricing agreements and ten note exhibits filed. | 0001193125-26-194086 |
| 27 Mar 2026 | 8-K, 8.01 | Suresh Kumar, Global Chief Technology Officer and Chief Development Officer, adopted a Rule 10b5-1 plan for up to 199,610 shares sold monthly from 29 June 2026 to 31 December 2026, subject to a price floor. | 0000104169-26-000067 |
| 13 Mar 2026 | 8-K, 8.01 | Three Rule 10b5-1 plans were reported: Doug McMillon for 155,328 shares, Dan Bartlett for up to $15.0m of stock through July 2029 and David Guggina for up to 21,108 shares. | 0000104169-26-000057 |
| 19 Feb 2026 | 8-K, 2.02, 9.01 | Fourth quarter and full year fiscal 2026 results: full year revenue of $713.2bn up 4.7%, a new $30.0bn repurchase authorisation and a fiscal 2027 annual dividend raised to $0.99 per share. | 0000104169-26-000032 |
| 30 Jan 2026 | 8-K/A, 5.02 | Kathryn McLay signed a separation agreement on 28 January 2026 for payments totalling $2,820,000 over two years and accelerated vesting of 24,051 restricted shares, with a two year noncompete. | 0000104169-26-000028 |
| 16 Jan 2026 | 8-K, 5.02, 9.01 | Segment leadership was reset effective 1 February 2026: David Guggina to Walmart U.S., Chris Nicholas to Walmart International and Latriece Watkins to Sam's Club U.S., with Kathryn McLay departing. | 0000104169-26-000023 |
| 16 Jan 2026 | 8-K/A, 5.02 | John Furner's fiscal 2027 package was set at a $1,500,000 salary, a 240% target cash incentive, a $17,000,000 annual equity award and a $10,000,000 one time performance based restricted stock unit award. | 0000104169-26-000024 |
| 8 Jan 2026 | 8-K, 5.02, 9.01 | Shishir Mehrotra joined the board and was appointed to the Compensation and Management Development Committee and the Technology and eCommerce Committee. | 0000104169-26-000008 |
| 29 Dec 2025 | 8-K, 8.01 | Chris Nicholas adopted a Rule 10b5-1 plan for 2,900 shares a month over twelve months from April 2026, a maximum of 34,800 shares. | 0000104169-25-000238 |
| 20 Nov 2025 | 8-K, 2.02, 9.01 | Third quarter fiscal 2026 results: revenue of $179.5bn up 5.8%, GAAP EPS of $0.77 and adjusted EPS of $0.62, with the fiscal 2026 adjusted EPS outlook raised to $2.58 to $2.63. | 0000104169-25-000177 |
| 20 Nov 2025 | 8-K, 3.01, 7.01 | Walmart told the NYSE it would withdraw the listings of its common stock and nine note series and move them to Nasdaq, with NYSE trading ending 8 December 2025 and Nasdaq trading opening 9 December 2025. | 0000104169-25-000177 |
| 14 Nov 2025 | 8-K, 5.02, 9.01 | Doug McMillon gave notice he would retire as president and chief executive on 31 January 2026, and the board appointed John Furner his successor and elected him a director. | 0000104169-25-000172 |
| 22 Oct 2025 | 8-K, 5.02 | Dwayne Milum was appointed Senior Vice President and Controller, and so principal accounting officer, effective 1 February 2026, with David Chojnowski moving to Senior Vice President, Treasurer and Tax. | 0000104169-25-000168 |
| 22 Sep 2025 | 8-K, 8.01 | Chief People Officer Donna Morris adopted a Rule 10b5-1 plan covering up to 148,665 shares vesting in January 2026, less shares withheld for taxes. | 0000104169-25-000153 |
| 19 Sep 2025 | 8-K, 8.01 | Daniel Danker, EVP of AI Acceleration, Product and Design, adopted a Rule 10b5-1 plan covering up to 109,976 shares from two vesting dates, less shares withheld for taxes. | 0000104169-25-000151 |
| 5 Sep 2025 | 8-K, 8.01 | Chief Financial Officer John David Rainey adopted a Rule 10b5-1 plan for 20,000 shares on each of 2 February 2026 and 2 March 2026, a maximum of 40,000 shares. | 0000104169-25-000143 |
Leadership turned over in ninety days
Six of the twenty events are Item 5.02 disclosures, and they run in sequence. Doug McMillon gave notice on 11 November 2025, the board named John Furner on 13 November 2025, Furner's pay was fixed on 15 January 2026 and the three segment chief executives were named on 16 January 2026. Every appointment took effect on the same date, 1 February 2026, the first day of fiscal 2027.
The compensation attached to the change is disclosed and modest against the size of the company. Furner's fiscal 2027 package is a $1,500,000 salary, a 240% target cash incentive with a 300% cap, a $17,000,000 annual equity award split 85% performance units and 15% restricted stock, and a $10,000,000 one time performance unit award vesting one third after year one and two thirds after year two. Guggina, Nicholas and Watkins carry salaries of $975,000, $1,000,000 and $925,000 with equity awards of about $8,000,000, $9,000,000 and $7,000,000. McMillon stays on the payroll through 31 January 2027 at $1.5m a year, drops out of the Management Incentive Plan after 31 January 2026, and has 11,524 restricted shares and 195,898 performance shares pulled forward from January 2028 to January 2027. His noncompete runs to 31 January 2029. Kathryn McLay's exit cost $2,820,000 over two years plus acceleration of 24,051 restricted shares, with all other unvested equity forfeited.
One gap sits in the record. Fourteen directors signed the fiscal 2026 Form 10-K on 13 March 2026, and eleven stood for election on 4 June 2026. McMillon's departure from the board at that meeting was disclosed in the 14 November 2025 8-K. Timothy P. Flynn and Brian Niccol do not appear on the slate, and no 8-K in the window reports either departure.
The April 2026 note offering is the only new financing contract

Walmart priced $4.25bn of senior unsecured notes on 27 April 2026 and settled on 30 April 2026, in five tranches maturing 2029 to 2036 with fixed coupons of 4.000% to 4.750% plus a $350m floating rate tranche. Four of the five priced inside par, between 99.786 and 99.937, so the $4,245,848,500 gross offering price sits $4,151,500 below principal. The $15,500,000 underwriting discount is 36.5 basis points of principal, which is thin pricing for a ten year maximum tenor. The notes were issued off the 19 July 2005 indenture with The Bank of New York Mellon Trust Company, N.A. as successor trustee, under shelf registration Form S-3ASR file 333-275878, and rank equally with all other senior unsecured obligations.
The raise falls in fiscal 2027 and does not sit inside the $3,983m of long term debt proceeds the fiscal 2026 Form 10-K reports for the year to 31 January 2026. Total long term debt was $38,166m at that date against short term borrowings of $6,600m, $15,000m of undrawn committed United States credit lines and $2,000m of syndicated and fronted letters of credit, of which $1,700m was issued.
Capital return was reset upward at the year end
The 19 February 2026 8-K carried the two decisions that matter for shareholder yield. The board approved a new $30.0bn repurchase authorisation with no expiry, which from 23 February 2026 replaced the $4.0bn left under the $20.0bn authorisation approved in November 2022. The fiscal 2027 annual dividend was set at $0.99 per share against $0.94, a 5.3% increase, payable in four instalments of $0.2475.
The buyback tells its own story about price. Walmart repurchased 85.0 million shares for $8,088m in fiscal 2026 at an average of $95.13, having called the first quarter of that year opportunistic. In the first half of fiscal 2027 it bought 42.3 million shares for $5,104m at an average of $120.71, against 67.4 million shares for $6,200m at $92.03 in the same half a year earlier: 31% more per share for 37% fewer shares. The 10-Q attributes the lower spend to that prior year opportunism. $25.1bn of the new authorisation remained at 31 July 2026.
The Nasdaq move was mechanical
On 19 November 2025 Walmart told the NYSE it would voluntarily withdraw the listings of its common stock and nine listed note series and transfer them to Nasdaq. NYSE trading ended at the close on 8 December 2025 and Nasdaq trading opened on 9 December 2025. Every ticker was retained, from WMT for the common stock to WMT39 for the 4.875% notes due 2039, and no economics changed. The one consequence that reaches the governance record is in Chapter 6: the 2026 proxy is the first to test director independence against the Nasdaq Listing Rules.
Insider plans are frequent but small

Six of the twenty events are Rule 10b5-1 plan adoptions covering eight executives, the heaviest single category in the log. The share caps total 709,487 shares, which is 0.0089% of the shares outstanding at the 10 April 2026 record date. Dan Bartlett's plan is capped at $15.0m through July 2029, so it carries no share figure. Every plan states that the executive keeps no discretion over timing, and each named executive remains subject to a stock ownership requirement of five times base salary. Chris Nicholas adopted his plan on 24 December 2025 while running Sam's Club U.S., and was named chief executive of Walmart International three weeks later on 16 January 2026, so the plan predates the promotion that changed the shares behind it. Chapter 7 sets out what those plans executed.
Table 19. Material contracts disclosed in the fiscal 2026 Form 10-K and in Form 8-K filings
| Counterparty | Subject | Term | Filing |
|---|---|---|---|
| Citigroup Global Markets, J.P. Morgan Securities, Mizuho Securities USA, Barclays Capital, HSBC Securities (USA) and U.S. Bancorp Investments, as representatives | Underwriting agreement and pricing agreement for $4.25bn of senior unsecured notes | Signed 27 April 2026, settled 30 April 2026 | 8-K 0001193125-26-194086, exhibit 1.1 |
| The Bank of New York Mellon Trust Company, N.A., as successor trustee | Indenture dated 19 July 2005 as supplemented, plus five series terms certificates and five global note forms | Notes mature 2029 to 2036; the indenture itself has no stated end | 8-K 0001193125-26-194086, exhibits 4.1 to 4.10; 10-K 0000104169-26-000055, exhibits 4.4 to 4.7 |
| Flipkart Private Limited | Share issuance and acquisition agreement, with parts omitted under a confidential treatment request | Dated 9 May 2018, still listed as a live exhibit | 10-K 0000104169-26-000055, exhibit 10.15, incorporated by reference |
| Flipkart Private Limited selling shareholders and Fortis Advisors LLC | Counterpart form of share purchase agreement with Wal-Mart International Holdings | Dated 9 May 2018, still listed as a live exhibit | 10-K 0000104169-26-000055, exhibit 10.16, incorporated by reference |
| Ernst & Young LLP | Appointment as independent registered public accounting firm, ratified by shareholders | Fiscal year ending 31 January 2027 | 8-K 0000104169-26-000111, Item 5.07 |
| C. Douglas McMillon | Retirement agreement: $1.5m salary from 1 February 2026 and accelerated vesting of 11,524 restricted and 195,898 performance shares | Employment to 31 January 2027; noncompete extended to 31 January 2029 | 8-K 0000104169-25-000172; 10-K 0000104169-26-000055, exhibit 10.18 |
| Kathryn McLay | Separation agreement: $2,820,000 of payments and acceleration of 24,051 restricted shares | Signed 28 January 2026; noncompete two years from 30 April 2026 | 8-K/A 0000104169-26-000028; 10-K 0000104169-26-000055, exhibit 10.19 |
| John R. Furner | Covenant not to compete on the form filed as exhibit 10(p) to the fiscal 2011 Form 10-K | Two year noncompete and nonsolicit, with two years of salary continuation | 8-K 0000104169-25-000172 |
| David Guggina, Chris Nicholas and Latriece Watkins | Post termination agreements and covenants not to compete dated 2020, 2018 and 2014 | Two year noncompete, with two years of salary continuation | 8-K 0000104169-26-000023 |
| Dwayne Milum | Post termination agreement and covenant not to compete signed on promotion to Controller | One year noncompete, with up to one year of salary continuation | 8-K 0000104169-25-000168 |
What the exhibit index does not contain
Walmart files almost no commercial contracts. The fiscal 2026 exhibit index lists twenty Exhibit 10 items, of which eighteen are marked as management contracts or compensatory arrangements. The only two commercial agreements are the pair of 2018 Flipkart documents, both incorporated by reference and both still carrying confidential treatment for omitted portions. Supplier, logistics, technology and real estate agreements are absent because no single one is material to a company with $713.2bn of revenue. The scale of that off exhibit commitment is visible only in aggregate: $41.4bn of unrecorded purchase obligations at 31 January 2026, of which $18.3bn falls due within a year. An investor cannot read the terms of any individual one of those from the filings.
The $15.0bn of undrawn committed United States credit lines is likewise disclosed only as an amount. No credit agreement is filed as an exhibit and no lender is named, so the covenant package behind Walmart's commercial paper backstop is not visible in the public record.
6 Ownership, Voting Power & Annual Meeting
Walmart has one class of common stock and one vote per share. The control premium comes from an irrevocable proxy inside the Walton family that gathers 3,516,197,849 shares, 44.11% of the 7,970,990,515 shares outstanding at the 10 April 2026 record date, into a single voting hand at Walton Enterprises, LLC. That block is a minority of the class and still decides most outcomes. At the 4 June 2026 annual meeting it exceeded, on its own, the threshold for every item settled by a majority of the shares present and entitled to vote: the say on pay resolution and all four shareholder proposals. It fell short on only two items, the auditor ratification by 66,075,692 shares and the charter amendment by 469,297,408 shares, because each of those carries a wider denominator.
For the stock this cuts two ways. A holder buying WMT buys into a company where no external investor can force a board change, no activist stake is viable and no takeover is possible without the family. The largest institution on the register, the Vanguard complex at 425,802,131 shares, holds 5.34% of the class, one eighth of the family block. Against that, strip the block from the winning side of every ballot and the outcome does not change on any of the eighteen items voted. The lowest supported director still clears 91.76% of the remaining votes cast, and the best supported shareholder proposal still reaches only 14.78%.
The wedge sits inside the family
The proxy reports Walton Enterprises with 3,516,197,849 shares and the Walton Family Holdings Trust with 513,524,456. Those figures overlap. Footnotes 3 and 4 of the DEF 14A separate them: Walton Enterprises holds sole dispositive power over 3,002,673,393 shares of its own, and sole voting power over a further 513,524,456 shares that the trust owns, under an irrevocable proxy the trust granted in December 2024. The trust keeps the economics of its shares and votes none of them.
Table 20. Economic ownership against voting power, 10 April 2026
Holders of more than five percent of the class, from the DEF 14A. Percentages are of the 7,970,990,515 shares outstanding on the record date.
| Holder | Economic shares | Economic percent | Voting shares | Voting percent |
|---|---|---|---|---|
| Walton Enterprises, LLC | 3,002,673,393 | 37.67% | 3,516,197,849 | 44.11% |
| Walton Family Holdings Trust | 513,524,456 | 6.44% | 0 | 0.00% |
| Walton family block, combined | 3,516,197,849 | 44.11% | 3,516,197,849 | 44.11% |
| All other holders | 4,454,792,666 | 55.89% | 4,454,792,666 | 55.89% |
| Directors and executive officers, 24 persons | 7,044,961 | 0.09% | 7,044,961 | 0.09% |
Economic shares are sole dispositive power. The directors and officers line sits inside the all other holders line and excludes the two Walton entities.

At block level the two columns are identical, because the proxy moves votes among family entities. The gap only appears entity by entity, and it matters for anyone reading the two Schedule 13D lines as separate stakes. Walton Enterprises votes 44.11% while owning 37.67%. The trust owns 6.44% and votes nothing.
Four managing member trusts control Walton Enterprises and act by majority vote: WELLCO Mgmt Trust #1 through #4, whose trustees are Carrie Walton Penner, Benjamin Walton, Rob Walton and Samuel Walton; Alice Proietti, James Walton, Jim Walton, Steuart Walton and Thomas Walton; Alice Walton; and Lukas Walton. Control of the block therefore turns on a majority among four trusts.
What the block can carry on its own
Walmart applies three different vote standards, and the block clears two of them alone.
Table 21. Vote standards and the reach of the family block
| Item | Standard | Denominator | Majority needed | Block as percent | Surplus or shortfall |
|---|---|---|---|---|---|
| Election of directors | Majority of the votes cast | 6,526,039,822 | 3,263,019,911 | 53.88% | 253,177,938 |
| Say on pay and the four shareholder proposals | Majority of shares present and entitled to vote | 6,530,575,436 | 3,265,287,718 | 53.84% | 250,910,131 |
| Ratify Ernst & Young | Majority of shares present | 7,164,547,083 | 3,582,273,542 | 49.08% | (66,075,692) |
| Charter amendment | Majority of shares outstanding | 7,970,990,515 | 3,985,495,258 | 44.11% | (469,297,408) |
The director denominator is the largest votes cast total of the eleven nominees, which is the hardest bar of the eleven. Abstentions and broker nonvotes do not count as votes cast. The auditor ratification drew no broker nonvotes, which widens its denominator to the full shares present.
The 2026 proxy makes no controlled company claim, and at 44.11% the block is short of the majority of voting power such a designation requires. The board keeps a majority of independent directors: of the eleven elected on 4 June 2026, eight are independent under the Nasdaq Listing Rules, and the board did not determine independence for Greg Penner or Steuart Walton. John Furner is not independent as chief executive.
The 2026 annual meeting
Turnout was 89.88%. Holders of 7,164,547,083 of the 7,970,990,515 shares outstanding were present or represented. Broker nonvotes were 633,971,647, 8.85% of the shares present, and identical on every item except the auditor ratification, where brokers may vote without instruction.
Table 22. Annual meeting results, 4 June 2026
All eleven nominees were elected, all three company proposals passed and all four shareholder proposals were rejected.
| Item | Board | For | Against | Abstain | Broker nonvotes |
|---|---|---|---|---|---|
| Cesar Conde | FOR | 6,475,579,143 | 50,164,479 | 4,831,814 | 633,971,647 |
| Sarah J. Friar | FOR | 6,514,321,598 | 11,700,270 | 4,553,568 | 633,971,647 |
| John R. Furner | FOR | 6,485,530,053 | 40,316,465 | 4,728,918 | 633,971,647 |
| Carla A. Harris | FOR | 6,352,545,569 | 173,494,253 | 4,535,614 | 633,971,647 |
| Thomas W. Horton | FOR | 6,413,736,523 | 111,888,677 | 4,950,236 | 633,971,647 |
| Marissa A. Mayer | FOR | 6,466,604,047 | 59,398,938 | 4,572,451 | 633,971,647 |
| Shishir Mehrotra | FOR | 6,492,644,977 | 32,899,188 | 5,031,271 | 633,971,647 |
| Robert E. Moritz, Jr. | FOR | 6,465,496,802 | 60,064,343 | 5,014,291 | 633,971,647 |
| Gregory B. Penner | FOR | 6,348,541,000 | 177,035,049 | 4,999,387 | 633,971,647 |
| Randall L. Stephenson | FOR | 6,274,541,334 | 247,546,757 | 8,487,345 | 633,971,647 |
| Steuart L. Walton | FOR | 6,484,158,261 | 41,690,946 | 4,726,229 | 633,971,647 |
| 2. Ratify Ernst & Young LLP | FOR | 6,985,709,983 | 172,769,575 | 6,067,525 | 0 |
| 3. Advisory vote on named executive officer pay | FOR | 6,263,129,484 | 256,160,712 | 11,285,240 | 633,971,647 |
| 4. Charter amendment limiting officer liability | FOR | 6,153,086,052 | 370,166,105 | 7,323,279 | 633,971,647 |
| 5. Cumulative voting for board elections | AGAINST | 122,306,285 | 6,390,550,159 | 17,718,992 | 633,971,647 |
| 6. Report on workplace health and safety governance | AGAINST | 433,230,655 | 6,013,774,452 | 83,570,329 | 633,971,647 |
| 7. Report on immigration policy and enforcement | AGAINST | 278,449,353 | 6,174,725,696 | 77,400,387 | 633,971,647 |
| 8. Report on workforce impact of AI and automation | AGAINST | 323,453,709 | 6,138,362,361 | 68,759,366 | 633,971,647 |
The proponents were the National Legal and Policy Center on cumulative voting, Oxfam America, Inc. on workplace health and safety, SOC Investment Group on immigration policy and United for Respect on the workforce impact of AI.
Support ranged from 99.82% of votes cast for Sarah Friar to 96.20% for Randall Stephenson, the only nominee to draw more than 200 million votes against. Gregory Penner, the chairman, and Carla Harris drew the next largest opposition at 177,035,049 and 173,494,253 votes. Say on pay carried 96.07% of votes cast and the charter amendment 94.33%, its 370,166,105 votes against the largest opposition on any company proposal.

No filing discloses how Walton Enterprises voted. The second bar in Figure 24 is a scenario that removes the block from the side the board recommended, and it is the most favourable reading available to the proponents. Even on that basis the workplace health and safety proposal reaches 14.78% and the cumulative voting proposal 4.08%, both far below a majority of the 6,530,575,436 shares present and entitled to vote. The same scenario applied to the director slate leaves Stephenson at 91.76% and Penner at 94.12%. The block is decisive, and on this record every outcome holds without it.
The cumulative voting proposal is the one item aimed directly at the control structure. Its proponent argued that the Walton family controls roughly half the voting power and that this limits the ability of other shareholders to influence board composition. It drew 122,306,285 votes for against 6,390,550,159 against, the weakest showing of the four.
Institutional ownership is broad and thin
More than four thousand institutions report the stock each quarter, and the four largest hold 13.49% of the class between them, less than a third of the family block.
Table 23. Largest Form 13F managers, shares held by quarter
| Manager | 30 Sep 2025 | 31 Dec 2025 | 31 Mar 2026 | 30 Jun 2026 | 30 Jun 2026, percent of class |
|---|---|---|---|---|---|
| Vanguard complex | 436,365,997 | 440,720,205 | 422,399,856 | 425,802,131 | 5.34% |
| BlackRock, Inc. | 345,660,392 | 350,124,222 | n/a | 354,923,708 | 4.45% |
| State Street Corp | 184,805,978 | 184,703,850 | 185,928,865 | 188,036,646 | 2.36% |
| Geode Capital Management | 96,493,315 | 103,010,709 | 105,856,140 | 106,449,749 | 1.34% |
| Four managers together | 1,063,325,682 | 1,078,558,986 | n/a | 1,075,212,234 | 13.49% |
Percent of class is of the 7,970,990,515 shares outstanding at the record date. The Vanguard line sums every Vanguard filer reporting the CUSIP: two filers in the 2025 quarters and nine from the March 2026 quarter. The BlackRock Form 13F for the March 2026 quarter could not be retrieved from the data service after repeated attempts, so that cell reads n/a rather than an estimate, and the March 2026 total for the four managers is left blank for the same reason.

The number of managers reporting CUSIP 931142103 rose from 4,138 for the September 2025 quarter to 4,565 for the March 2026 quarter, then eased to 4,493 for June 2026, a net gain of 355 managers or 8.6% across the four quarters. The June 2026 count is still accruing; a Form 13F for that period was filed as late as 2 September 2026. Shares held by the three managers with a complete four quarter series moved in a narrow band, from 717.7 million to 728.4 million and back to 720.3 million, a range of 2.0%. Ownership is broadening by holder count while the large index positions sit still. A total across every reporting manager is not computed here, because the Form 13F index returns whole filings rather than an aggregate; the filer counts are exact.
Schedule 13D and 13G history
Four beneficial ownership filings landed in the two years to 2 September 2026. Three concern the Walton family and one concerns Vanguard. None reports an activist position.
Table 24. Beneficial ownership filings, two years to 2 September 2026
| Filed | Form | Filer | What it reported | Accession |
|---|---|---|---|---|
| 19 Dec 2024 | SC 13D | Walton Enterprises, LLC and Walton Family Holdings Trust | First Schedule 13D after decades of Schedule 13G reporting. Managing member interests moved into four WELLCO Mgmt Trusts, eight trustees joined the trust, and the trust granted Walton Enterprises an irrevocable proxy. Walton Enterprises reported 3,606,663,095 voting shares, 44.90%, and the trust 603,989,702 shares, 7.52%. | 0001140361-24-049960 |
| 31 Jan 2025 | SC 13G/A No. 44 | S. Robson Walton, Jim C. Walton, Alice L. Walton and the John T. Walton Estate Trust | Group dissolution notice. Individual holdings fell to 7,029,557 shares, 31,521,372 shares and 20,245,740 shares, each under 0.4% of the class, with the estate trust at nil. | 0001140361-25-002729 |
| 3 Mar 2026 | SC 13D/A No. 1 | Walton Enterprises, LLC and Walton Family Holdings Trust | Distributions to beneficiaries and sales for investment, personal and charitable purposes cut the trust below its prior level. Walton Enterprises reported 3,523,409,231 voting shares, 44.21%, and the trust 520,735,838 shares, 6.53%. Jim C. Walton's pledged shares fell from 4,464,286 to 3,222,342. | 0001140361-26-007628 |
| 27 Mar 2026 | SC 13G/A No. 1 | The Vanguard Group, Inc. | Reports nil voting and nil dispositive power and certifies ownership of five percent or less of the class. | 0000102909-26-002689 |
The December 2024 Schedule 13D reports a restructuring. Walton Enterprises held the same 3,002,673,393 shares before and after; what changed is that four trusts replaced three individuals as managing members and the trust handed over its votes. The family has been selling steadily since: the trust reported 603,989,702 shares in December 2024, 520,735,838 in February 2026 and 513,524,456 at the April 2026 record date, a decline of 90,465,246 shares over sixteen months, and the filings attribute it to distributions to beneficiaries and sales for personal and charitable objectives. Walton Enterprises' own holding has not moved. Chapter 7 follows the same selling through the Section 16 record.
The Vanguard filing records a change of reporting entity. Vanguard first crossed five percent in a Schedule 13G filed 13 February 2024 covering 137,513,258 shares, 5.11% of the class as it then stood, before the three for one forward split Walmart effected on 23 February 2024. The March 2026 amendment takes The Vanguard Group, Inc. to nil, and from the same quarter the position appears across nine affiliated Form 13F managers totalling 422,399,856 shares. The largest of them, Vanguard Capital Management LLC at 286,350,346 shares, is 3.59% of the class, below the five percent reporting threshold. The Vanguard complex in aggregate still holds 5.34%.
No activist has filed a Schedule 13D on Walmart in the two year window. The only 13D on the register belongs to the family, and it states that the reporting entities hold the stock as an investment with no plans that would result in any of the actions listed in Item 4.
7 Insider Activity
No Walmart insider bought a share on the open market in the twelve months to 2 September 2026. Across 205 Forms 3, 4 and 5, covering 274 transaction lines, there is not one transaction code P and not one option exercise. The buy to sell ratio, computed on open market transactions only, is undefined for want of a numerator: zero shares bought against 26,657,530 shares sold for $3,136.8m.
Of those 26.7 million shares, 26,565,448, or 99.7%, are the Walton Family Holdings Trust. Officers and directors sold 92,082 shares for $10.5m at their own discretion, across five transactions by four people among the 28 officers and directors who filed. A further 544,159 shares for $63.7m left under Rule 10b5-1 plans adopted before the sale. Against that, the issuer granted officers and directors 1,035,450 shares and withheld 1,074,992 shares worth $127.6m to pay tax on vesting. More Walmart stock was taken back by the company for withholding than the entire management team sold by any route.
For the stock, the selling is concentrated in the family holding, and management's own sales were almost entirely prescheduled, through a chief executive succession. The Trust disposed of 46,292,448 shares, 8.5% of its own stake, and the balance fell from 546,128,200 to 499,835,752, or 6.28% of the 7,958,079,155 shares outstanding printed on its 26 June 2026 Form 144.

Awards, withholding and gifts
Most insider share movement never touched the market. Officers and directors moved 4,286,135 shares in the window and 3,649,894 of them, 85%, went by award, withholding, gift or trust distribution rather than by trade. Awards vesting account for 1,035,450 shares, withholding at source for 1,074,992, gifts for 871,452 and trust distributions for 20,395,000. Counting any of them as insider conviction would invert the reading.

Walmart insiders hold no derivative securities at all. Not one Form 4 in the window carries a Table II line, so there are no options to exercise and no synthetic exposure to unwind. Compensation arrives as restricted stock and performance based restricted stock units, vests on fixed dates in January and March, and is taxed at vesting. That mechanism produces most of the volume.
The plan sales cluster the same way. Nine insiders sold 544,159 shares across 49 executions at an average $117.02, under the plans catalogued in Chapter 5. Doug McMillon sold nine monthly tranches of exactly 19,416 shares, the last on 28 May 2026, against a plan running to 155,328 shares, which is eight further tranches of the same size. Chris Nicholas sold 2,900 shares a month from April 2026, reaching 14,500 of his 34,800 maximum. Dan Bartlett's monthly tranche steps up from about 1,400 shares to 3,775 in July 2026 and 3,710 in August 2026, consistent with a dollar denominated plan replacing a share denominated one.
Suresh Kumar is the exception that carries information. His plan sells about 33,270 shares a month from 29 June 2026 to 31 December 2026 up to 199,610 shares, subject to a minimum stock price threshold, with any month missed carried into the next month the threshold is met. He has filed no Form 4 reporting a sale since 9 March 2026. Reported transaction prices fell from $133.77 in mid May 2026 to $105.35 on 26 August 2026 over the same stretch.
Table 25. Open market transactions, twelve months to 2 September 2026
Every code S and code P line filed in the window. Sales executed in several price bands on one day are shown as one transaction at the weighted average price the filer discloses. Basis reads Rule 10b5-1 plan where the Form 4 cover box is ticked and the footnote names the plan, and discretionary otherwise. There are no code P rows.
| Date | Insider | Role | Code | Basis | Shares | Price per share | Holding after |
|---|---|---|---|---|---|---|---|
| Officers and directors | |||||||
| 12 Sep 2025 | Suresh Kumar | Chief Technology Officer | S | Discretionary | 30,000 | $103.47 | 1,787,200 |
| 15 Sep 2025 | Dan Bartlett | EVP | S | Rule 10b5-1 plan | 1,610 | $103.71 | 645,968 |
| 18 Sep 2025 | John Furner | EVP | S | Rule 10b5-1 plan | 13,125 | $103.74 | 906,064 |
| 19 Sep 2025 | Kathryn McLay | EVP | S | Rule 10b5-1 plan | 4,000 | $103.83 | 1,048,455 |
| 25 Sep 2025 | Doug McMillon | President and CEO | S | Rule 10b5-1 plan | 19,416 | $103.21 | 4,373,576 |
| 1 Oct 2025 | John David Rainey | EVP | S | Rule 10b5-1 plan | 2,200 | $101.33 | 621,718 |
| 15 Oct 2025 | Dan Bartlett | EVP | S | Rule 10b5-1 plan | 1,550 | $107.46 | 644,418 |
| 16 Oct 2025 | John Furner | EVP | S | Rule 10b5-1 plan | 13,125 | $107.78 | 892,940 |
| 20 Oct 2025 | Kathryn McLay | EVP | S | Rule 10b5-1 plan | 4,000 | $107.75 | 1,044,455 |
| 23 Oct 2025 | Doug McMillon | President and CEO | S | Rule 10b5-1 plan | 19,416 | $107.18 | 4,354,162 |
| 3 Nov 2025 | John David Rainey | EVP | S | Rule 10b5-1 plan | 2,200 | $101.18 | 619,518 |
| 17 Nov 2025 | Dan Bartlett | EVP | S | Rule 10b5-1 plan | 1,630 | $102.58 | 642,788 |
| 19 Nov 2025 | Kathryn McLay | EVP | S | Rule 10b5-1 plan | 4,000 | $101.63 | 1,040,455 |
| 20 Nov 2025 | John Furner | EVP | S | Rule 10b5-1 plan | 13,125 | $104.75 | 879,815 |
| 25 Nov 2025 | David Chojnowski | SVP | S | Discretionary | 7,000 | $106.65 | 136,289 |
| 28 Nov 2025 | Doug McMillon | President and CEO | S | Rule 10b5-1 plan | 19,416 | $109.57 | 4,334,747 |
| 1 Dec 2025 | John David Rainey | EVP | S | Rule 10b5-1 plan | 2,200 | $111.23 | 617,318 |
| 15 Dec 2025 | Dan Bartlett | EVP | S | Rule 10b5-1 plan | 1,425 | $117.00 | 641,363 |
| 18 Dec 2025 | John Furner | EVP | S | Rule 10b5-1 plan | 13,125 | $114.91 | 733,841 |
| 19 Dec 2025 | Kathryn McLay | EVP | S | Rule 10b5-1 plan | 4,000 | $115.21 | 1,031,455 |
| 26 Dec 2025 | Doug McMillon | President and CEO | S | Rule 10b5-1 plan | 19,416 | $111.83 | 4,315,333 |
| 14 Jan 2026 | Daniel Danker | EVP | S | Rule 10b5-1 plan | 4,365 | $120.19 | 238,583 |
| 14 Jan 2026 | Donna Morris | EVP | S | Rule 10b5-1 plan | 9,384 | $120.19 | 536,312 |
| 15 Jan 2026 | Dan Bartlett | EVP | S | Rule 10b5-1 plan | 1,388 | $120.00 | 645,642 |
| 15 Jan 2026 | John Furner | EVP | S | Rule 10b5-1 plan | 13,125 | $119.99 | 727,155 |
| 22 Jan 2026 | Doug McMillon | President and CEO | S | Rule 10b5-1 plan | 19,416 | $119.17 | 4,274,856 |
| 2 Feb 2026 | John David Rainey | EVP | S | Rule 10b5-1 plan | 20,000 | $122.27 | 506,764 |
| 3 Feb 2026 | Donna Morris | EVP | S | Rule 10b5-1 plan | 76,181 | $123.79 | 402,072 |
| 17 Feb 2026 | Dan Bartlett | EVP | S | Rule 10b5-1 plan | 1,255 | $133.21 | 586,329 |
| 19 Feb 2026 | John Furner | President and CEO | S | Rule 10b5-1 plan | 13,125 | $129.10 | 591,084 |
| 20 Feb 2026 | Chris Nicholas | EVP | S | Discretionary | 34,082 | $122.00 | 533,466 |
| 20 Feb 2026 | Latriece Watkins | EVP | S | Discretionary | 10,000 | $121.46 | 108,294 |
| 26 Feb 2026 | Doug McMillon | Director | S | Rule 10b5-1 plan | 19,416 | $126.71 | 4,023,209 |
| 2 Mar 2026 | John David Rainey | EVP | S | Rule 10b5-1 plan | 20,000 | $127.79 | 486,764 |
| 16 Mar 2026 | Dan Bartlett | EVP | S | Rule 10b5-1 plan | 1,325 | $126.28 | 638,178 |
| 19 Mar 2026 | John Furner | President and CEO | S | Rule 10b5-1 plan | 13,125 | $121.96 | 687,287 |
| 26 Mar 2026 | Doug McMillon | Director | S | Rule 10b5-1 plan | 19,416 | $123.16 | 4,213,406 |
| 15 Apr 2026 | Dan Bartlett | EVP | S | Rule 10b5-1 plan | 1,335 | $124.63 | 636,843 |
| 16 Apr 2026 | John Furner | President and CEO | S | Rule 10b5-1 plan | 13,125 | $124.84 | 674,162 |
| 16 Apr 2026 | Chris Nicholas | EVP | S | Rule 10b5-1 plan | 2,900 | $124.72 | 596,008 |
| 23 Apr 2026 | Doug McMillon | Director | S | Rule 10b5-1 plan | 19,416 | $132.21 | 4,193,995 |
| 15 May 2026 | Dan Bartlett | EVP | S | Rule 10b5-1 plan | 1,250 | $133.77 | 635,593 |
| 21 May 2026 | John Furner | President and CEO | S | Rule 10b5-1 plan | 13,125 | $124.08 | 661,037 |
| 21 May 2026 | Chris Nicholas | EVP | S | Rule 10b5-1 plan | 2,900 | $123.92 | 577,853 |
| 28 May 2026 | Doug McMillon | Director | S | Rule 10b5-1 plan | 19,416 | $118.63 | 4,174,579 |
| 28 May 2026 | Latriece Watkins | EVP | S | Discretionary | 11,000 | $118.97 | 120,203 |
| 10 Jun 2026 | David Guggina | EVP | S | Rule 10b5-1 plan | 11,978 | $119.82 | 125,067 |
| 15 Jun 2026 | Dan Bartlett | EVP | S | Rule 10b5-1 plan | 1,385 | $119.83 | 633,784 |
| 18 Jun 2026 | Chris Nicholas | EVP | S | Rule 10b5-1 plan | 2,900 | $118.19 | 574,953 |
| 1 Jul 2026 | Dan Bartlett | EVP | S | Rule 10b5-1 plan | 3,775 | $109.64 | 630,009 |
| 16 Jul 2026 | Chris Nicholas | EVP | S | Rule 10b5-1 plan | 2,900 | $114.14 | 572,053 |
| 3 Aug 2026 | Dan Bartlett | EVP | S | Rule 10b5-1 plan | 3,710 | $113.10 | 626,299 |
| 20 Aug 2026 | Chris Nicholas | EVP | S | Rule 10b5-1 plan | 2,900 | $106.34 | 569,153 |
| 26 Aug 2026 | Daniel Danker | EVP | S | Rule 10b5-1 plan | 50,644 | $105.35 | 201,672 |
| Family entity | |||||||
| 16 Sep 2025 | Walton Family Holdings Trust | Ten percent owner | S | Discretionary | 2,389,000 | $103.45 | 535,663,200 |
| 21 Nov 2025 | Walton Family Holdings Trust | Ten percent owner | S | Discretionary | 4,145,744 | $105.96 | 530,951,456 |
| 16 Dec 2025 | Walton Family Holdings Trust | Ten percent owner | S | Discretionary | 261,000 | $115.31 | 527,359,456 |
| 19 Dec 2025 | Walton Family Holdings Trust | Ten percent owner | S | Discretionary | 872,000 | $114.26 | 525,964,456 |
| 23 Feb 2026 | Walton Family Holdings Trust | Ten percent owner | S | Discretionary | 1,200,000 | $125.86 | 524,676,456 |
| 24 Feb 2026 | Walton Family Holdings Trust | Ten percent owner | S | Discretionary | 3,734 | $127.01 | 524,672,722 |
| 25 Feb 2026 | Walton Family Holdings Trust | Ten percent owner | S | Discretionary | 65,537 | $127.17 | 524,607,185 |
| 26 Feb 2026 | Walton Family Holdings Trust | Ten percent owner | S | Discretionary | 21,770 | $127.12 | 524,282,415 |
| 27 Feb 2026 | Walton Family Holdings Trust | Ten percent owner | S | Discretionary | 1,701,466 | $127.75 | 522,580,949 |
| 2 Mar 2026 | Walton Family Holdings Trust | Ten percent owner | S | Discretionary | 314,572 | $128.10 | 521,418,377 |
| 3 Mar 2026 | Walton Family Holdings Trust | Ten percent owner | S | Discretionary | 682,539 | $128.16 | 520,735,838 |
| 4 Mar 2026 | Walton Family Holdings Trust | Ten percent owner | S | Discretionary | 67,796 | $128.00 | 519,618,042 |
| 9 Mar 2026 | Walton Family Holdings Trust | Ten percent owner | S | Discretionary | 1,389,794 | $124.23 | 518,228,248 |
| 11 Mar 2026 | Walton Family Holdings Trust | Ten percent owner | S | Discretionary | 1,389,792 | $123.82 | 516,838,456 |
| 24 Mar 2026 | Walton Family Holdings Trust | Ten percent owner | S | Discretionary | 299,237 | $122.33 | 516,504,219 |
| 25 Mar 2026 | Walton Family Holdings Trust | Ten percent owner | S | Discretionary | 2,979,763 | $122.96 | 513,524,456 |
| 22 May 2026 | Walton Family Holdings Trust | Ten percent owner | S | Discretionary | 1,591,500 | $120.00 | 511,932,956 |
| 26 May 2026 | Walton Family Holdings Trust | Ten percent owner | S | Discretionary | 532,340 | $119.21 | 509,849,616 |
| 27 May 2026 | Walton Family Holdings Trust | Ten percent owner | S | Discretionary | 254,178 | $119.05 | 509,595,438 |
| 28 May 2026 | Walton Family Holdings Trust | Ten percent owner | S | Discretionary | 207,649 | $119.01 | 509,387,789 |
| 2 Jun 2026 | Walton Family Holdings Trust | Ten percent owner | S | Discretionary | 1,771,333 | $113.32 | 507,616,456 |
| 16 Jun 2026 | Walton Family Holdings Trust | Ten percent owner | S | Discretionary | 4,424,704 | $121.09 | 502,305,752 |
The family is the supply, and Form 4 only shows part of it
Walton Enterprises, LLC files nothing here. It has lodged three Forms 4 in its history and the last, accession 0001127602-20-009852, records the contribution of 415,000,000 shares to the Walton Family Holdings Trust on 5 March 2020. The Trust is the family's Section 16 vehicle and the only family entity to file a Form 4 in the window, across 21 filings.

The Trust disposes through two channels of similar size. It sold 26,565,448 shares on the open market at an average $117.68, in 22 blocks concentrated in September, November, February, March, May and June. It also distributed 19,727,000 shares to beneficiaries for no consideration under transaction code J. Those distributions are the front end of a charitable pipeline that the Section 16 record does not follow to its end. The Form 144 filed on 26 June 2026, accession 0001958244-26-000409, sets out one full cycle: the Trust distributed 1,703,000 shares to James Walton on 24 June 2026, he contributed them to The Walton Family Foundation on 26 June 2026, and the Foundation gave notice of intent to sell all 1,703,000 the same day for a market value of $197,020,070. The Form 144 filed on 6 March 2026, accession 0001958244-26-000120, records the same pattern for 427,000 shares moving from the Trust through S. Robson Walton to The Rob Walton Foundation.
Walmart's CIK carries 65 Form 144 and Form 144/A notices in the window. Of those, 21 come from nine family linked vehicles that hold no Section 16 office and therefore file no Form 4: The Walton Family Foundation, Builders Vision Foundation, The Rob Walton Foundation, Alumbra Innovations Foundation, CRW 2024 WMT GRAT, the Alice L. Walton 2021 Charitable Trust, Town Branch Foundation, WPS2 Fund and Wartime History Museum. Their sales are invisible in any screen built on Forms 3, 4 and 5.
Table 26. Sales by family linked vehicles that file no Form 4
Read from the securities sold in the past three months tables of two Form 144 notices, accessions 0001958244-26-000120 and 0001958244-26-000409. Coverage is limited to the look back windows those two notices report, so the total below is a floor on family selling outside Section 16 and covers less than the full year.
| Seller | Sale date | Shares | Gross proceeds | Note |
|---|---|---|---|---|
| The Walton Family Foundation, Inc. | 15 Dec 2025 | 107,000 | $12.5m | |
| Town Branch Foundation | 18 Dec 2025 | 350,000 | $40.3m | Same date, size and proceeds as one other seller |
| The Walton Family Foundation, Inc. | 18 Dec 2025 | 350,000 | $40.3m | Same date, size and proceeds as one other seller |
| WPS2 Fund | 23 Dec 2025 | 523,000 | $58.2m | |
| The Walton Family Foundation, Inc. | 26 Dec 2025 | 88,000 | $9.8m | |
| Alumbra Innovations Foundation | 5 Mar 2026 | 25,000 | $3.1m | |
| The Walton Family Foundation, Inc. | 27 May 2026 | 43,000 | $5.1m | Same date, size and proceeds as one other seller |
| Alumbra Innovations Foundation | 27 May 2026 | 43,000 | $5.1m | Same date, size and proceeds as one other seller |
| Alice L. Walton 2021 Charitable Trust | 29 May 2026 | 619,000 | $71.7m | |
| CRW 2024 WMT GRAT | 3 Jun 2026 | 86,000 | $10.1m | |
| The Walton Family Foundation, Inc. | 25 Jun 2026 | 767,000 | $89.0m | |
| Reported total | 3,001,000 | $345.1m | ||
| The Rob Walton Foundation | 6 Mar 2026 | 427,000 | $52.9m | Proposed sale, accession 0001958244-26-000120 |
| The Walton Family Foundation, Inc. | 26 Jun 2026 | 1,703,000 | $197.0m | Proposed sale, accession 0001958244-26-000409 |
Two pairs in that table carry the same date, the same share count and the same gross proceeds under two different seller names, on 18 December 2025 at 350,000 shares and on 27 May 2026 at 43,000 shares. The notices do not say whether each pair is two sales or one sale reported against two names. Read the reported total as 3,001,000 shares if they are separate and 2,608,000 if they are not. Both readings are kept because the filings support both.
Table 27. Twelve month position change by insider
Awards, withholding, sales and transfers as filed, with the holding reported on the last Form 4 of the window. Gifts and transfers nets shares received against shares gifted or distributed. Steuart Walton shows nil there because he received 668,000 shares from the Trust in three distributions and gave the same 668,000 to charity within days of each.
| Insider | Role | Awards | Withheld for tax | Plan sales | Discretionary sales | Gifts and transfers | Holding at close | Change |
|---|---|---|---|---|---|---|---|---|
| Officers | ||||||||
| John Furner | President and CEO from 1 Feb 2026 | 133,078 | (140,258) | (118,125) | n/a | (132,850) | 661,037 | (258,152) |
| Doug McMillon | President and CEO to 31 Jan 2026 | 209,611 | (253,300) | (174,744) | n/a | n/a | 4,174,579 | (218,413) |
| Donna Morris | EVP | 70,620 | (63,309) | (85,565) | n/a | (65,178) | 457,557 | (143,432) |
| Kathryn McLay | EVP | n/a | (106,834) | (16,000) | n/a | (5,000) | 924,621 | (127,834) |
| Rachel Brand | EVP | n/a | (67,937) | n/a | n/a | n/a | 463,999 | (67,937) |
| John David Rainey | EVP | 115,776 | (116,166) | (46,600) | n/a | n/a | 576,928 | (46,990) |
| Seth Dallaire | EVP | 43,972 | (3,541) | n/a | n/a | n/a | 377,629 | 40,431 |
| Daniel Danker | EVP | 84,819 | (54,966) | (55,009) | n/a | n/a | 201,672 | (25,156) |
| David Chojnowski | SVP | n/a | (15,420) | n/a | (7,000) | n/a | 121,632 | (22,400) |
| Dan Bartlett | EVP | 67,144 | (66,361) | (21,638) | n/a | (424) | 626,299 | (21,279) |
| Suresh Kumar | Chief Technology Officer | 138,912 | (127,547) | n/a | (30,000) | n/a | 1,798,565 | (18,635) |
| Dwayne Milum | SVP and Controller | 7,635 | (1,021) | n/a | n/a | n/a | 49,152 | 6,626 |
| Chris Nicholas | EVP | 86,640 | (42,607) | (14,500) | (34,082) | n/a | 569,153 | (4,549) |
| Latriece Watkins | EVP | 23,745 | (5,528) | n/a | (21,000) | n/a | 115,882 | (2,728) |
| David Guggina | EVP | 20,227 | (10,196) | (11,978) | n/a | n/a | 124,842 | (1,931) |
| Directors | ||||||||
| Greg Penner | Director | 4,904 | n/a | n/a | n/a | n/a | 263,110 | 6,277 |
| Randall Stephenson | Director | 3,623 | n/a | n/a | n/a | n/a | 67,445 | 4,930 |
| Marissa Mayer | Director | 2,957 | n/a | n/a | n/a | n/a | 133,413 | 4,049 |
| Steuart Walton | Director | 3,180 | n/a | n/a | n/a | n/a | 82,621 | 3,668 |
| Sarah Friar | Director | 3,180 | n/a | n/a | n/a | n/a | 62,376 | 3,667 |
| Shishir Mehrotra | Director | 3,227 | n/a | n/a | n/a | n/a | 3,475 | 3,227 |
| Robert Moritz | Director | 2,979 | n/a | n/a | n/a | n/a | 14,032 | 3,050 |
| Cesar Conde | Director | 2,957 | n/a | n/a | n/a | n/a | 33,777 | 2,957 |
| Carla Harris | Director | 2,558 | n/a | n/a | n/a | n/a | 52,188 | 2,558 |
| Thomas Horton | Director | 1,935 | n/a | n/a | n/a | n/a | 59,848 | 1,935 |
| Timothy Flynn | Director | 1,003 | n/a | n/a | n/a | n/a | 156,289 | 1,328 |
| Brian Niccol | Director | 768 | n/a | n/a | n/a | n/a | 9,616 | 303 |
| Family entity | ||||||||
| Walton Family Holdings Trust | Ten percent owner | n/a | n/a | n/a | (26,565,448) | (19,727,000) | 499,835,752 | (46,292,448) |
The change column will not tie exactly to the columns beside it for every insider, and the forms name the reason. Chaining the reported balances across the window leaves 37 steps over 274 lines, adding to 4,801 shares with the largest single step at 1,248. Nonmanagement directors elect to defer receipt of their annual equity grant, several officers defer a portion of vested restricted stock, and one officer's balance is restated periodically to pick up shares held in the Walmart Inc. 2016 Associate Stock Purchase Plan. None of those movements is separately reportable, so a chained balance drifts. At 0.01% of the 50.6 million shares transacted, the drift changes no reading in this chapter.
The succession in the Section 16 record
The title lines on the Forms 4 track the handover to the day. Doug McMillon files as President and CEO on every form through January 2026 and as a director on every form after it. John Furner files as Executive Vice President through December 2025 and as President and CEO, and a director, from January 2026. Neither man bought a share around the announcement of 14 November 2025 or around the effective date of 1 February 2026. McMillon's plan tranche continued at 19,416 shares a month straight through both dates. Furner's continued at 13,125.
Furner's largest single movement is a gift. On 21 November 2025, one week after the board named him, he transferred 132,850 shares to a trust in which his spouse is trustee. That is a code G gift, reported at zero price, and it accounts for more than half his 258,152 share decline for the year. He still reported 661,037 shares on his last Form 4 of the window, on 21 May 2026.
Six Forms 3 were filed. Shishir Mehrotra reported 248 shares on joining the board on 8 January 2026. Four officers reported opening positions effective 1 February 2026, the first day of fiscal 2027: Seth Dallaire 487,728 shares, David Guggina 126,773, Latriece Watkins 120,275 and Dwayne Milum 42,526. Erin Nealy Cox filed a Form 3 on 13 April 2026 reporting no securities at all, with neither a Table I nor a Table II.
Discretionary selling by officers is confined to four names and five dates. Suresh Kumar sold 30,000 shares at $103.47 on 12 September 2025. David Chojnowski sold 7,000 at $106.65 on 25 November 2025. Chris Nicholas sold 34,082 at $122.00 on 20 February 2026, three weeks after taking over Walmart International. Latriece Watkins sold 10,000 at $121.46 on 20 February 2026 and 11,000 at $118.97 on 28 May 2026. Those five transactions are the whole of the unscheduled selling by Walmart's officers and directors in the year: 92,082 shares, or 0.001% of the shares outstanding. One notice of intent has no trade behind it in the Section 16 record. Rachel Brand gave notice on 20 February 2026, accession 0001958244-26-000093, of a proposed sale of 85,357 shares worth $10,498,057. No Form 4 in the window reports a sale by her, and her only Form 4 lines are 67,937 shares withheld for tax. A Form 144 reports a proposed sale.
What the record does not settle
Two things sit outside what Forms 3, 4, 5 and 144 can answer. Family selling outside Section 16 is only visible where a Form 144 look back table happens to capture it, so the $345.1m in Table 26 is a floor drawn from two look back windows rather than a twelve month figure. And Walmart insiders are paid in stock, hold no options, and are subject to stock ownership guidelines that the plan disclosures state are still met after each sale; a Walmart officer who wants more exposure receives it by vesting. The reading that survives both caveats is narrow: management's stake fell 874,431 shares over the year, almost all of it through vesting mechanics and prescheduled plans, and the family sold 46.3 million shares into a market that took them at an average $117.68.
8 Risk Factors
Walmart added no risk factor and dropped none. The FY2026 10-K carries the same 24 risk factors under the same four category headings as the FY2025 10-K, in the same order. Seventeen were reworded, seven are word for word identical. Tariffs move from a conditional threat to a realised one with a forward warning into fiscal 2027, agentic commerce and AI enter as a competitive and cyber threat across five factors, drug pricing policy is named for the first time, and the litigation factor is stripped of every named matter and given a new self insurance paragraph. Item 1A shrank to 13,399 words from 14,189, a fall of (790) words or (5.6%), while the strategic block grew 10%. Both fiscal 2027 10-Q filings, for the quarters ended 30 April 2026 and 31 July 2026, state that no material change in the FY2026 risk factors has occurred, so Item 1A has not been updated for the $2.9bn tariff refund, the change of chief executive or the move of the listing.

The legal and regulatory block lost (711) words, and the litigation factor alone accounts for (706) of that. Operational lost (275), driven by a (370) word cut to the climate and natural disaster factor. Strategic gained 196 words, all of it AI and agentic commerce. Financial risks are unchanged to the word.

What the change map shows
Table 28. Item 1A risk factor change map, FY2026 10-K against FY2025 10-K
| # | Risk | Category | Status | What changed |
|---|---|---|---|---|
| 1 | Omnichannel execution and investment cost | Strategic | Reworded | Agentic platforms and AI driven search, discovery, advertising and purchasing are added as a channel shift that pulls traffic out of stores, and the caveat on a moderated pace of new store openings is dropped. |
| 2 | Consumer trends and preferences | Strategic | Reworded | Adds a duty to develop and scale AI powered search and discovery, and adds inaccurate, biased or flawed AI results and customer dissatisfaction to the trust erosion list. |
| 3 | Competition | Strategic | Reworded | Names emerging agentic shopping tools as competitors, flags faster AI development by rivals, and adds a new paragraph on protecting trademarks, copyrights, domain names, patents and trade secrets. |
| 4 | Macroeconomic conditions | Strategic | Reworded | Decreases in consumer disposable income become decreases in consumer purchasing power, including from reductions resulting from changes to government programs. |
| 5 | Strategic alliances | Strategic | Reworded | The ONE fintech venture is removed as the worked example; the risk otherwise reads the same. |
| 6 | Pandemics and epidemics | Operational | Reworded | Condensed. The list of travel bans, quarantines, shelter in place orders and business shutdowns is cut. |
| 7 | Natural disasters, climate and geopolitical events | Operational | Reworded | Climate content cut hardest: the physical and transition risk lists, the Hurricanes Helene and Milton example and the named conflict zones all go, and Walmart now says it bears the majority of adaptation costs. |
| 8 | Supplier risk | Operational | Reworded | Restructured into a list. Pandemic recovery disruption and port strikes drop out; the tariff and trade restriction sentence stays. |
| 9 | Own sold product quality and safety | Operational | Unchanged | |
| 10 | Marketplace product quality and safety | Operational | Unchanged | |
| 11 | Information and financial systems | Operational | Reworded | The catastrophic event list becomes a cross reference, and civil unrest and armed hostilities drop out of the causes of systems damage. |
| 12 | Customer facing technology platforms | Operational | Reworded | The heading adds failure to keep pace with competitors, and the body states there is no assurance AI investment delivers the benefits or that Walmart adopts AI as fast as rivals. |
| 13 | Privacy and cybersecurity | Operational | Reworded | Two new sentences on AI: it automates attack techniques and compresses detection time, and lets attackers run reconnaissance, write exploit code, harvest credentials and run extortion campaigns autonomously. |
| 14 | Health and wellness reimbursement | Operational | Reworded | New item in the pharmacy risk list: governmental focus on reducing drug prices, naming most favored nation pricing, maximum fair price negotiations and direct to consumer pharmacy delivery models. |
| 15 | Associates, wages and labour | Operational | Unchanged | |
| 16 | Independent contractors and service providers | Operational | Unchanged | |
| 17 | Market expectations for financial performance | Financial | Unchanged | |
| 18 | Foreign exchange | Financial | Unchanged | |
| 19 | International operations | Legal and regulatory | Reworded | The international share of consolidated net sales is restated to about 19% from about 18%; the Canada, Mexico and India antitrust reference carries over unchanged. |
| 20 | Tax and trade laws | Legal and regulatory | Reworded | Tariffs move from conditional to realised, with an explicit fiscal 2027 warning, and Pillar Two moves from pending to effective with new language on cash taxes and controversy costs. |
| 21 | Other laws and regulations | Legal and regulatory | Reworded | OnePay adds cryptocurrency and equity products with custody obligations; new exposure to dynamic and algorithmic pricing rules, membership cancellation rules and AI statutes; penalty ceilings under GDPR and PIPL are deleted; VIZIO is restated as a standing order rather than a new acquisition risk. |
| 22 | Litigation and legal proceedings | Legal and regulatory | Reworded | Every named matter moves to Item 3 and Note 9. In come novel product injury theories naming the acetaminophen and baby food multidistrict litigation, pricing and supplier cost antitrust cases naming batteries and soft drinks, and a new self insurance paragraph. |
| 23 | Delaware exclusive forum bylaw | Legal and regulatory | Unchanged | |
| 24 | Stakeholder expectations on social and environmental efforts | Legal and regulatory | Reworded | ESG is retired as a label in the heading and body, and the reference to opinions for and against diversity, equity and inclusion is replaced by various social and environmental initiatives. |
Status counts: 0 new, 17 reworded, 7 unchanged, 0 dropped, against 24 risk factors in each year.
The changes that move the stock
Tariffs stop being hypothetical. FY2025 said trade policy changes "could have an adverse effect". FY2026 says they "can impact, and have impacted, our business and profit margins", that Walmart "experienced the impacts noted above during fiscal 2026 as a result of incremental import tariffs", and that it expects the dynamic tariff environment to continue "including in fiscal 2027" with an effect it cannot predict and that "could be material". This is the first Walmart risk factor to concede a realised gross margin hit from tariffs and then extend the warning into the current year. Item 1A carries no number for any of it, not even for the $2.9bn of refunds and the 96 basis point gross margin gain that followed in the July 2026 quarter. A reader sizing tariff sensitivity has to work from the MD&A and the segment tables in Chapter 3.
AI moves from an efficiency story to a threat. FY2025 framed AI as an investment Walmart was making. FY2026 adds, for the first time, that "there can be no assurance that these investments will deliver the anticipated benefits, or that we will be able to adopt and leverage these technologies as quickly or effectively as our competitors". Agentic shopping platforms appear six times and are named as competitors, as a source of traffic diversion from stores, and as a reason Walmart must structure its offering "in a manner that allows us to maintain a direct relationship with our customers". That last clause is the disintermediation risk stated plainly: if a purchase agent stands between Walmart and the shopper, the advertising and membership businesses that carry the margin mix are the exposed part. Generative AI disappears as a term and plain AI rises to 16 mentions from 10.
AI also raises the cyber floor. The privacy and cybersecurity factor, already the longest in Item 1A at 2,204 words, gains two sentences saying AI compresses the time available to detect and respond to threats and enables autonomous reconnaissance, exploit generation, credential harvesting and extortion at scale. A growing patchwork of AI laws is added to the compliance load. Walmart still reports that incidents occurred during the year without a material adverse effect, now updated to fiscal 2026.
Drug pricing policy is named. The pharmacy risk list adds governmental focus on reducing drug prices, naming most favored nation pricing policies, maximum fair price negotiations and direct to consumer pharmacy delivery models. Walmart U.S. comparable sales for the six months ended 31 July 2026 were held back by a decrease in health and wellness attributed primarily to maximum fair price regulation on certain prescription drugs effective January 2026. The risk factor confirms the mechanism the quarterly results already show.
Consumer purchasing power replaces disposable income. The macroeconomic factor now flags reductions in purchasing power resulting from changes to government programs. For a business where grocery carries the United States comparable sale, benefit program changes hit the top line directly, and this is the first year Walmart writes it into Item 1A.
The litigation factor is rebuilt, and shorter. It falls to 680 words from 1,386. Every named matter of FY2025 goes: opioids, the driver platform and the Consumer Financial Protection Bureau suit against Walmart and Branch, the Flipkart foreign direct investment notice, the Competition Commission of India investigation, the COFECE decision against Walmex and the money transfer agent services litigation. All are still disclosed, in Item 3 and Note 9, and the fiscal 2027 second quarter 10-Q still carries opioids, Asda equal value claims, the money transfer agent services investigation, the driver platform, Mexico antitrust and India antitrust in Note 5. The driver platform matter has changed hands: Item 3 of the FY2026 10-K names Federal Trade Commission and State Attorneys General litigation filed 26 February 2026 in the Northern District of California, where FY2025 named the Consumer Financial Protection Bureau action filed 23 December 2024. Opioid cases in the multidistrict litigation fell to about 230 at 6 March 2026 from about 250 at 10 March 2025. What is new in Item 1A is forward looking: novel personal injury and economic loss theories from consumer products, naming the acetaminophen and baby food multidistrict litigation, and antitrust and consumer protection class actions over retail prices and supplier costs, naming batteries and soft drinks.
Self insurance enters Item 1A. The new paragraph states that workers compensation, general liability, auto liability, product liability and certain employee healthcare benefits are funded predominantly through self insurance, and that significant claims, regulatory change or a rise in health care costs could hit financial condition and results. This is a disclosure catching up with reported numbers: higher self insured general liability claims expense, driven by rising costs to resolve claims across retail and related industries, was a named driver of the increase in operating expenses as a percentage of net sales in both the first and second quarters of fiscal 2027 and cost roughly $0.9bn in fiscal 2026.
ESG is retired as a word. Eight uses in FY2025, none in FY2026, replaced throughout by social and environmental. The FY2025 sentence about opinions expressed for and against diversity, equity and inclusion is gone. The substantive risk of stakeholder dissatisfaction and of challenge by regulators, private organisations and individuals is retained in full. Climate mentions halve to four from eight, and the physical and transition risk taxonomy is deleted, which reduces the detail available to anyone modelling climate cost exposure from the filing alone.
What did not change, and what is missing
Seven factors are identical: own sold product quality, marketplace product quality, associates and wages, independent contractors, market expectations for financial performance, foreign exchange and the Delaware exclusive forum bylaw. Financial risks did not move at all.
Walmart discloses no risk factor for the loss or transition of key personnel, in either year, and the FY2026 10-K filed 13 March 2026 adds none despite the announcement on 14 November 2025 that Doug McMillon would retire and John Furner would succeed him. The move of the listing from the New York Stock Exchange to Nasdaq on 9 December 2025 draws no risk factor either. Neither omission is unusual for a company of this size, and neither is a defect, but a reader looking to Item 1A for management transition or listing risk will not find it.
FY2026 Item 1A quantifies almost nothing. It contains two figures, the 82% of consolidated net sales from the United States segments and the 19% from Walmart International. FY2025 contained seven, including the €20m or 4% of global turnover ceiling under GDPR, the RMB 50m or 5% of China revenue ceiling under PIPL, and the 15% Pillar Two rate. Those ceilings were removed and no figure replaced them. The consequence is that no exposure in Item 1A can be sized from Item 1A. Every number in this chapter that carries a currency sign comes from MD&A or the financial statement notes.
9 Stock Price, Scenarios & Sensitivity
At $106.54 the stock already pays for the operating improvement it is being asked to deliver. That price is 37.6 times the midpoint of the fiscal 2027 adjusted earnings guide of $2.80 to $2.87, 37.9 times trailing adjusted earnings of $2.81 and 39.0 times fiscal 2026 reported diluted earnings of $2.73. Market capitalisation is $845.3bn on the 7,933,746,241 shares reported on the cover of the second quarter Form 10-Q. The stock is 20.6% below its highest daily close of $134.20 on 19 May 2026 and 9.3% above its twelve month low of $97.50. Across a three year scenario built on stated inputs, the implied value per share at fiscal 2029 runs from $67.13 to $150.78. The base case lands at $111.29, a 2.8% annualised total return over the 2.4 years to 31 January 2029, and the single input that moves it most is the terminal multiple.
Where the stock stands

The five year record is a 129.3% gain from a September 2021 month end price of $46.46, 18.4% a year. The last twelve months carry the reversal. The stock made its highest daily close on 19 May 2026, two days before the first quarter release, and each of the last three results days was received worse than the one before it.
Table 29. Reaction of the last trade to each results release, twelve months to 2 September 2026
| Date | Release | Prior close | Close | Move |
|---|---|---|---|---|
| 19 Feb 2026 | Fiscal 2026 results and the $30.0bn repurchase authorisation | 126.62 | 124.87 | (1.4%) |
| 21 May 2026 | First quarter fiscal 2027 results | 130.85 | 121.34 | (7.3%) |
| 20 Aug 2026 | Second quarter fiscal 2027 results and the raised guide | 114.30 | 103.84 | (9.2%) |
The August fall came on a raised guide. What the market took from it was the second half arithmetic set out in Table 13: applying the raised growth guide to the company's own fiscal 2026 adjusted operating income base of $31,000m leaves $16,113m to $16,578m for the second half against $15,989m a year earlier, growth of 0.8% to 3.7%, after first half adjusted operating income grew 13.6% and first half adjusted earnings per share grew 13.2%. The guide asks for almost none of that to continue.
Management gives the reason. The $2,900m of tariff refunds received under the IEEPA process in the July quarter, equal to 0.41% of fiscal 2026 revenue and to about 0.5% of annual United States net sales, were credited to cost of sales and are being reinvested in price in the second half. The chief financial officer asked investors to read the second and third quarters together. That is a judgement about the durability of the first half margin, and it is the judgement the scenarios below have to price.
Table 30. Multiple paid on adjusted earnings at each fiscal year end, and at the price date
| Fiscal year | Price at year end | Adjusted EPS | Multiple |
|---|---|---|---|
| FY2024 | 55.08 | 2.22 | 24.8x |
| FY2025 | 98.16 | 2.51 | 39.1x |
| FY2026 | 119.14 | 2.64 | 45.1x |
| At 2 September 2026 | 106.54 | 2.81 trailing | 37.9x |
The multiple went from 24.8 times to 45.1 times in two years while adjusted earnings grew 9.0% a year. Most of the five year return is rerating, and it has already partly reversed to 37.9 times. The three scenarios differ on where it settles.
Three year scenarios
The horizon is fiscal 2029, the year ending 31 January 2029, three fiscal years beyond the audited fiscal 2026 figures and 2.4 years beyond the price date. Every case runs the same mechanics and differs only on the five inputs that vary in the top block of Table 31. Revenue compounds at the stated rate from fiscal 2026 total revenue of $713,163m. The adjusted operating margin walks in equal steps from the fiscal 2026 base of 4.35% to the stated fiscal 2029 target. Adjusted operating income converts to adjusted net income at 68.3%, the fiscal 2026 relationship between adjusted earnings of $2.64 on 8,022 million diluted shares and the $31,000m adjusted operating income base, held constant in every case so that tax, interest and minority interest are not a hidden lever. Shares retire at the stated annual repurchase spend divided by the $106.54 price, held flat as a modelling convention. Implied value per share is fiscal 2029 adjusted earnings multiplied by the stated terminal multiple. Dividends over the horizon are half the declared fiscal 2027 rate of $0.99 plus the full fiscal 2028 and fiscal 2029 rates at the stated growth.
Table 31. Three year scenarios to fiscal 2029, inputs and outcomes. Every input is a number, so each case can be rebuilt from this table alone
| Best | Base | Worst | |
|---|---|---|---|
| Assumptions | |||
| Revenue CAGR, FY2026 to FY2029 | 5.5% | 4.3% | 2.8% |
| Adjusted operating margin, FY2029 | 5.10% | 4.60% | 4.15% |
| Terminal multiple on FY2029 adjusted EPS | 40x | 34x | 24x |
| Repurchase, $m a year | 10,000 | 9,000 | 6,000 |
| Dividend per share growth a year | 10% | 7% | 4% |
| Adjusted operating income to net income conversion | 68.3% | 68.3% | 68.3% |
| Result | |||
| FY2029 revenue, $m | 837,426 | 809,174 | 774,762 |
| FY2029 adjusted operating income, $m | 42,709 | 37,222 | 32,153 |
| FY2029 diluted shares, m | 7,740 | 7,769 | 7,853 |
| FY2029 adjusted EPS, $ | 3.77 | 3.27 | 2.80 |
| Implied value per share, $ | 150.78 | 111.29 | 67.13 |
| Dividends over the horizon, $ | 2.78 | 2.69 | 2.60 |
| Total return over the horizon | 44.1% | 7.0% | (34.6%) |
| Annualised over 2.4 years | 16.3% | 2.8% | (16.1%) |
The base case is an estimate, not a forecast, and it is calibrated against the guide the company has already issued. Its fiscal 2027 adjusted earnings of $2.84 sit inside the $2.80 to $2.87 range. The best case reaches $2.98, which needs a 3.9% beat of the top of the current guide in the first of the three years. The worst case reaches $2.69, a 3.9% miss of the bottom. The three year repurchase spend of $30,000m, $27,000m and $18,000m all fit inside the $30.0bn authorisation announced on 19 February 2026, of which $25,100m remained at 31 July 2026; the best case exhausts it exactly.
Three things break the base case. The terminal multiple is the first: at 34 times the base sits below the 37.6 times the stock trades on at the price date and below the 45.1 times paid at the fiscal 2026 year end, but well above the 24.8 times paid at the fiscal 2024 year end, and nothing in the filings fixes where it settles. The second half of fiscal 2027 is the second: a second half at the bottom of the 0.8% to 3.7% guided range starts the margin walk lower than the base assumes. The tariff refund is the third: $2,900m credited to cost of sales in one quarter does not repeat, so fiscal 2028 laps it inside the margin line.
The horizon is also the first three full years under John Furner. The scenarios hold capital allocation policy at the pattern the filings show. A change of that policy sits outside them.
What the best case requires
Five things have to hold together, and each is measurable in the filings.
Higher margin income has to keep outgrowing merchandise. Global advertising revenue was $6,400m in fiscal 2026, up 46%, and grew 38% again in the second quarter of fiscal 2027; membership fee income grew 17% in the same quarter. The best case asks for a fiscal 2029 adjusted operating margin of 5.10%, 75 basis points above the fiscal 2026 base of 4.35%. That has to come from mix, because the merchandise gross margin is where the tariff refund is being spent.
eCommerce has to keep carrying the comparable sales line, profitably. Walmart U.S. eCommerce net sales reached $99,600m in fiscal 2026 from $47,800m in fiscal 2022, 20.1% a year, and grew 23% again in the second quarter of fiscal 2027. Chapter 1 shows that the whole of the fiscal 2026 Walmart U.S. comparable sales gain came from the digital channel. The open variables are delivery density and cost per order.
The capital going into automation has to earn its return. Capital expenditure was $26,642m in fiscal 2026, 3.7% of revenue, guided to about 4.0% of net sales for fiscal 2027. Walmart's own disclosed return on investment fell to 15.1% in fiscal 2026 from 15.5% in fiscal 2025, and free cash flow covered only 0.96 times the payout in the same year, as Table 9 shows. The best case requires the incremental capital to earn above the current 15.1% return.
The repurchase helps least of the five. Ten billion dollars a year retires 93.9 million shares at $106.54, about 1.2% of the diluted count, and uses the whole $30.0bn over three years. Against the base case's $9,000m a year it adds $0.01 to fiscal 2029 earnings per share, 2.8% of the $0.50 gap between the two cases. The other 97% is operating.
Price investment has to buy share that stays. The $2,900m refund was credited to cost of sales and reinvested in price. If it holds traffic through fiscal 2028 the margin walk starts from the higher base the first half showed; if it does not, the second half guide is the run rate.
Core assumptions and what drives demand
The revenue assumption rests on volume through a fixed physical base: 10,955 retail units in 19 countries serving about 280 million customers a week, with comparable sales up 4.3% at Walmart U.S. and 2.9% at Sam's Club U.S. in fiscal 2026.
Table 32. Headwinds management quantifies, and the period each falls in
| Headwind | Size | Period | Source |
|---|---|---|---|
| Pharmacy deflation under maximum fair price regulation, Walmart U.S. comparable sales | 125 bps | Q2 FY2027, and management's estimate for the year | Earnings release and call |
| Flipkart Big Billion Days timing shift, net sales growth | 100 bps | Q3 FY2027 | Earnings release |
| Incremental fuel related cost above the original guidance assumption | $2,000m | FY2027 | Earnings call |
| Tariff refund credited to cost of sales, reinvested in price | $2,900m | Q2 FY2027 | Form 10-Q |
Currency turned from a $2,800m drag on fiscal 2026 net sales to a $3,900m tailwind in the first half of fiscal 2027. The guide is stated in constant currency, so the scenarios above, which are stated in reported dollars, carry that swing as an unmodelled variable.
One disclosure limit affects every margin assumption here. The $31,000m fiscal 2026 adjusted operating income base is the company's own figure, disclosed rounded to a tenth of a billion. It sits $1,175m above reported operating income of $29,825m, while the itemised reconciliation in Table 7 adds back $1,157m to reach $30,982m. The $18m between those two is rounding, because $30,982m is $31.0bn at the precision Walmart publishes. On the starting margin that is 0.3 bps, 4.344% against 4.347%, and the 4.35% used here holds on either. What the filings do not settle is which of the two figures management guides fiscal 2027 growth from, because the guide is issued as a growth rate and never as a dollar amount, so the base cannot be recovered from it. The $900m of incremental self insured general liability claims expense that fiscal 2026 carried is not part of this arithmetic: Walmart names it as a driver of operating expenses and never adds it back, so it sits inside the reported and the adjusted figure alike.
Sensitivity

Table 33. One way sensitivity of implied value per share, every other input at the base case
| Variable | Low | High | Value at low | Value at high | Swing |
|---|---|---|---|---|---|
| Terminal multiple on FY2029 adjusted EPS | 24x | 40x | 78.56 | 130.93 | 52.37 |
| Adjusted operating margin, FY2029 | 4.15% | 5.10% | 100.40 | 123.39 | 22.98 |
| Adjusted operating income to net income conversion | 65.00% | 71.00% | 105.89 | 115.66 | 9.77 |
| Revenue CAGR, FY2026 to FY2029 | 2.80% | 5.50% | 106.56 | 115.18 | 8.62 |
| Repurchase, $m a year | 0 | 12,000 | 107.78 | 112.52 | 4.74 |
The inputs rank by how far they move the implied value. Moving the terminal multiple across the range the stock has been paid over three fiscal year ends changes the implied value by $52.37 a share. Moving the fiscal 2029 operating margin across the full 95 basis point range of the three cases changes it by $22.98. Revenue growth across the full 270 basis point range changes it by $8.62, and stopping the buyback entirely costs $3.51 against the base. Operating execution matters less to the outcome than what the market is willing to pay for it, which is the same conclusion the rating history in Table 30 points to. The multiple and the margin are therefore the axes of the grid below.

Fourteen of the thirty combinations clear the $106.54 price. At the fiscal 2029 margin the worst case assumes, 4.15%, the stock needs 37 times to stand still. At the base margin of 4.60% it needs 34 times. At the best case margin of 5.10% it needs 30 times. Every cell below 30 times is under the current price whatever the margin, including the 5.10% margin the best case works hardest to earn. A holder of the stock at $106.54 is underwriting a multiple in the thirties three years out, and the margin only decides how far into the thirties.
The opposite reading is defensible. The fiscal 2027 guide has been raised once already, from constant currency net sales growth of 3.5% to 4.5% and adjusted operating income growth of 6.0% to 8.0% in February to 4.0% to 5.0% and 7.0% to 8.5% in August, with adjusted earnings taken from $2.75 to $2.85 up to $2.80 to $2.87. Advertising at 38% growth and membership fee income at 17% are compounding several times faster than merchandise. On that reading the multiple stays in the high thirties, the margin walks to the top of the range, and the best case becomes the central outcome. Table 31 does not settle that question. It states what each answer is worth.
Sources
SEC filings retrieved through the SEC-API.io MCP server. Walmart Inc., CIK 0000104169; peer filings under the CIKs of each issuer named in Table 15.
Table 34. Filings used
| Document | Period or date | Accession |
|---|---|---|
| Walmart Form 10-K, fiscal 2026 | Year ended 31 Jan 2026, filed 13 Mar 2026 | 0000104169-26-000055 |
| Walmart Form 10-K, fiscal 2025 | Year ended 31 Jan 2025, filed 14 Mar 2025 | 0000104169-25-000021 |
| Walmart Form 10-K, fiscal 2024 | Year ended 31 Jan 2024, filed 15 Mar 2024 | 0000104169-24-000056 |
| Walmart Form 10-Q | Quarter ended 30 Apr 2026 | 0000104169-26-000102 |
| Walmart Form 10-Q | Quarter ended 31 Jul 2026 | 0000104169-26-000154 |
| Walmart Form 10-Q | Quarter ended 31 Jul 2025 | 0000104169-25-000137 |
| Form 8-K, Item 2.02 and exhibit 99.1 | Fiscal 2023 results, 21 Feb 2023 | 0000104169-23-000010 |
| Form 8-K, Item 2.02 and exhibit 99.1 | Fiscal 2024 results, 20 Feb 2024 | 0000104169-24-000019 |
| Form 8-K, Item 8.01 | Rule 10b5-1 plan, 5 Sep 2025 | 0000104169-25-000143 |
| Form 8-K, Item 8.01 | Rule 10b5-1 plan, 19 Sep 2025 | 0000104169-25-000151 |
| Form 8-K, Item 8.01 | Rule 10b5-1 plan, 22 Sep 2025 | 0000104169-25-000153 |
| Form 8-K, Item 5.02 | Controller appointment, 22 Oct 2025 | 0000104169-25-000168 |
| Form 8-K, Item 5.02 | Chief executive succession, 14 Nov 2025 | 0000104169-25-000172 |
| Form 8-K, Items 2.02, 3.01, 7.01 | Q3 fiscal 2026 results and Nasdaq transfer, 20 Nov 2025 | 0000104169-25-000177 |
| Form 8-K, Item 8.01 | Rule 10b5-1 plan, 29 Dec 2025 | 0000104169-25-000238 |
| Form 8-K, Item 5.02 | Board appointment, 8 Jan 2026 | 0000104169-26-000008 |
| Form 8-K, Item 5.02 | Segment leadership, 16 Jan 2026 | 0000104169-26-000023 |
| Form 8-K/A, Item 5.02 | Chief executive compensation, 16 Jan 2026 | 0000104169-26-000024 |
| Form 8-K/A, Item 5.02 | Separation agreement, 30 Jan 2026 | 0000104169-26-000028 |
| Form 8-K, Item 2.02 and exhibit 99.1 | Fiscal 2026 results and guidance, 19 Feb 2026 | 0000104169-26-000032 |
| Form 8-K, Item 8.01 | Rule 10b5-1 plans, 13 Mar 2026 | 0000104169-26-000057 |
| Form 8-K, Item 8.01 | Rule 10b5-1 plan, 27 Mar 2026 | 0000104169-26-000067 |
| Form 8-K, Items 8.01 and 9.01 | Senior unsecured note offering, 30 Apr 2026 | 0001193125-26-194086 |
| Form 8-K, Item 2.02 and exhibit 99.1 | Q1 fiscal 2027 results, 21 May 2026 | 0000104169-26-000095 |
| Form 8-K, Items 5.03 and 5.07 | Charter amendment and annual meeting, 5 Jun 2026 | 0000104169-26-000111 |
| Form 8-K, Item 2.02 and exhibit 99.1 | Q2 fiscal 2027 results and raised guidance, 20 Aug 2026 | 0000104169-26-000145 |
| Form DEF 14A | Record date 10 Apr 2026, meeting 4 Jun 2026 | 0001193125-26-173673 |
| Schedule 13D | Walton Enterprises and Walton Family Holdings Trust, 19 Dec 2024 | 0001140361-24-049960 |
| Schedule 13G/A No. 44 | Walton family group dissolution, 31 Jan 2025 | 0001140361-25-002729 |
| Schedule 13D/A No. 1 | Walton Enterprises and the Trust, 3 Mar 2026 | 0001140361-26-007628 |
| Schedule 13G/A No. 1 | The Vanguard Group, Inc., 27 Mar 2026 | 0000102909-26-002689 |
| Form 4 | Walton Enterprises contribution to the Trust, 5 Mar 2020 | 0001127602-20-009852 |
| Form 144 | Rachel Brand proposed sale, 20 Feb 2026 | 0001958244-26-000093 |
| Form 144 | The Rob Walton Foundation, 6 Mar 2026 | 0001958244-26-000120 |
| Form 144 | The Walton Family Foundation, 26 Jun 2026 | 0001958244-26-000409 |
| Amazon.com, Inc. Form 10-K | Year to 31 Dec 2025 | 0001018724-26-000004 |
| Costco Wholesale Corporation Form 10-K | Year to 31 Aug 2025 | 0000909832-25-000101 |
| The Kroger Co. Form 10-K | Year to 31 Jan 2026 | 0001104659-26-037723 |
| Target Corporation Form 10-K | Year to 31 Jan 2026 | 0000027419-26-000016 |
| Dollar General Corporation Form 10-K | Year to 30 Jan 2026 | 0001104659-26-032325 |
| BJ's Wholesale Club Holdings Form 10-K | Year to 31 Jan 2026 | 0001531152-26-000007 |
| Dollar Tree, Inc. Form 10-K | Year to 31 Jan 2026 | 0000935703-26-000025 |
Forms 3, 4, 5 and 144, Forms 13F and the Schedule 13D and 13G record were retrieved as filing sets rather than as single documents; the accessions cited in Chapters 6 and 7 identify the individual filings quoted. Cover page share counts for the peer set are listed in the chapter model files.
Sector figures come from the U.S. Census Bureau: Advance Monthly Sales for Retail and Food Services, July 2026, released 14 August 2026, and Quarterly Retail E-commerce Sales, second quarter 2026, released 18 August 2026.
The Walmart second quarter fiscal 2027 earnings call of 20 August 2026 is not an EDGAR document. It was read from published transcripts, and quoted wording was matched against two independent transcript publications before use. Figures drawn from the call rather than a filing are identified as such in the text.
Share prices, the twelve month range and the results day moves come from a market data feed and are not part of the filings above. Prices are the last trade recorded on the date stated, which may differ from that session's close.
Disclaimer
This document is a financial analysis derived from public filings. It is provided for information only. It is not financial advice, not a recommendation to buy, hold or sell any security, and not an offer or a solicitation of an offer to do either. It takes no account of the objectives, financial situation or particular needs of any reader.
Figures are read from the filings listed in Table 34 and from the other sources named above, and are reproduced as filed. Where a company measure sits outside GAAP it is identified as the company's own. No representation is given that the contents are complete or free of error.
The scenarios, sensitivities and implied values in Chapter 9 are illustrations built on the stated assumptions. They are not forecasts, not price targets and not statements of what will happen, and the outcomes they describe may not occur. Share prices and market data are historical and are not a guide to future performance.
Anyone acting on this document does so on their own judgement and should consider taking independent professional advice.